


EN
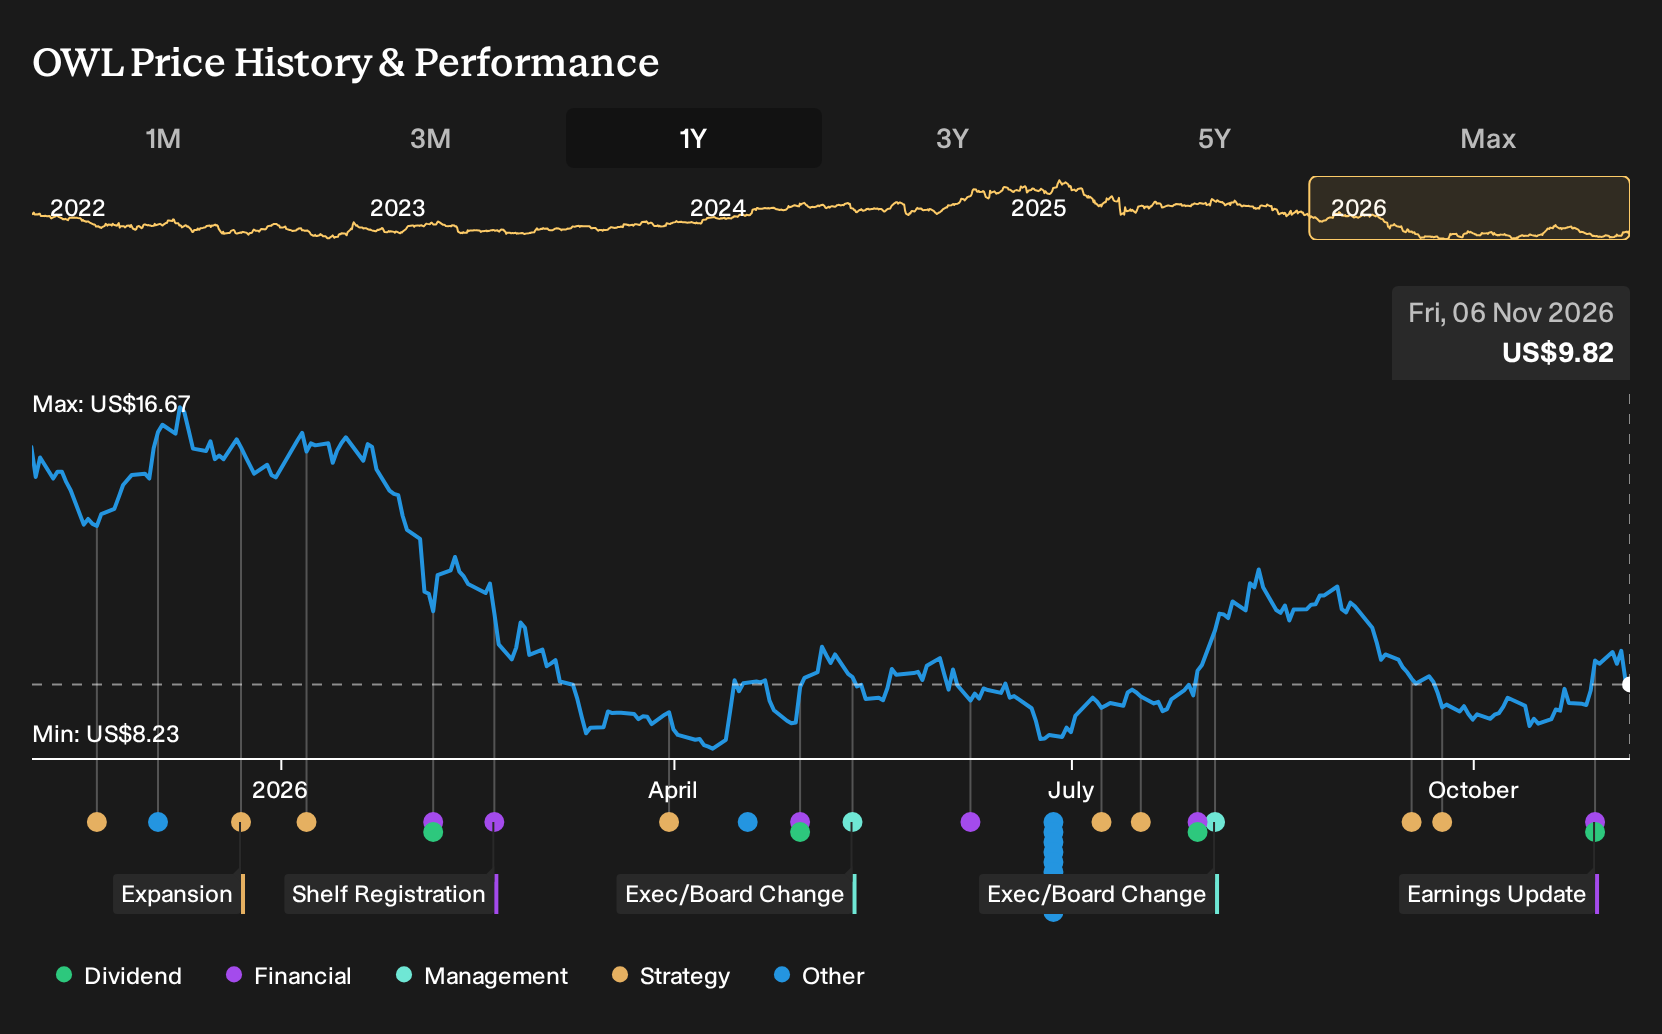
Why Blue Owl Capital Stock Is Up 6.2% And What's Next
- Blue Owl Capital reported third quarter 2026 revenue of US$806.53 million and net income of US$19.96 million, with basic and diluted EPS from continuing operations of US$0.03. The company also affirmed a quarterly dividend of US$0.23 per Class A share payable in November 2026.
- Higher revenue and net income, paired with an unchanged dividend, indicate that Blue Owl Capital is currently supporting both business expansion and regular cash returns from its fee based model.
- We will now look at how this stronger quarterly revenue performance might influence Blue Owl Capital's broader investment narrative for investors.
Scan fee-based peers that also blend cash distributions with business expansion by reviewing our hand picked 7 dividend fortresses alongside Blue Owl Capital's latest earnings and payout move.
Blue Owl Capital Investment Narrative Recap
To own Blue Owl Capital, investors need to be comfortable with a fee driven model that relies on fundraising, stable fee paying AUM and execution across private credit, real assets and GP stakes. The analyst consensus Narrative on Simply Wall St assumes that earnings can grow if undeployed capital is put to work. The latest quarter showed higher revenue and net income, which supports that view but does not remove execution risk.
The most important near term swing factor remains how fundraising and redemptions evolve in private credit and wealth channels, given past withdrawal pressure. The biggest risk is still pressure on fee paying AUM or legal and reputational damage from the BDC lawsuit. The third quarter beat does not materially change those core issues in the short run.
The dividend affirmation of US$0.23 per Class A share appears central to this update. It keeps Blue Owl Capital closely tied to an income oriented story, while analysts note that the dividend yield of 9.37% is not well covered by current earnings or free cash flow. That creates tension between payout expectations and reinvestment capacity.
For catalysts, investors are likely to monitor whether management can maintain this dividend while also funding growth in permanent capital, digital infrastructure projects and broader private wealth distribution. Any sustained mismatch between cash generation, legal costs, debt levels and the dividend commitment would likely intersect with the existing risk narrative around balance sheet flexibility and payout sustainability.
Analysts currently map out a path where Blue Owl Capital could reach US$3.5b in revenue and US$849.5m in earnings by 2029, which implies forecast revenue growth of 4.9% per year and an earnings increase of about US$754.9m from current earnings of US$94.6m.
Uncover why Blue Owl Capital's fair value indicates a 32% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One of the more optimistic angles on Blue Owl Capital focuses on real assets and data centers. Before this earnings print, the most bullish analysts were pencilling in revenue of about US$4.0b and earnings of roughly US$1.0b by 2029. You can treat today’s stronger quarter as a fresh data point that might reshape those expectations.
Explore 7 other Blue Owl Capital fair value estimates, including one that suggests as much as 73% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Blue Owl Capital research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Blue Owl Capital. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Blue Owl Capital's overall financial health at a glance.
Looking for more investment ideas beyond Blue Owl Capital?
Once you understand Blue Owl Capital, it can be useful to widen the lens and compare its profile with other companies that match your own income, quality, and risk preferences using the Simply Wall St Screener.
- If you value stability and lower volatility, you may want to look at companies that score well on balance sheet strength through our list of solid balance sheet and fundamentals (25 results).
- If your focus is on quality at a reasonable price, you can line up potential ideas with our valuation focused 40 high quality undervalued stocks.
- If you are looking for income plays that aim to combine yield with resilience, you can shortlist opportunities using our dividend focused 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com