


EN
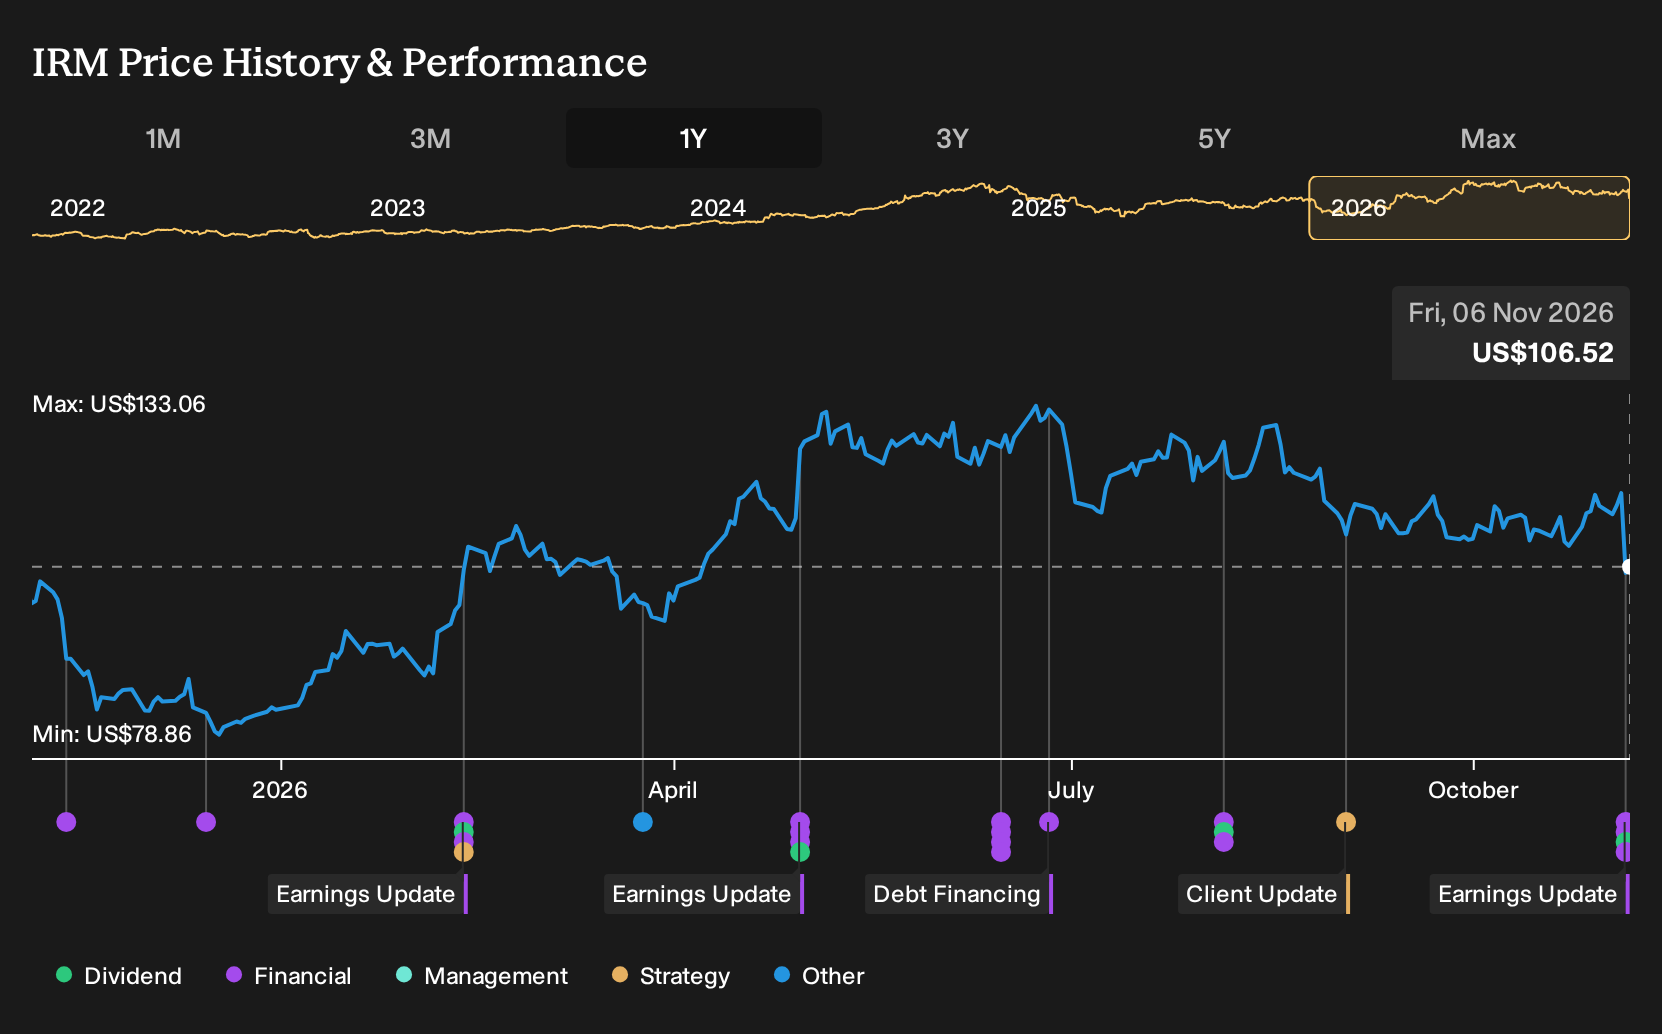
Iron Mountain Stock Is Up 15% Dividend Hike What's Changed
- Iron Mountain reported third quarter 2026 sales of US$1,149.51 million and net income of US$124.14 million, raised full year revenue guidance to a range of US$7.95 billion to US$8.02 billion, and approved a 15% higher quarterly dividend of US$0.993 per share for payment in early 2027.
- Data center leasing reached a record 102 megawatts and lifted Iron Mountain's data center revenue backlog to US$575 million, underscoring how newer infrastructure and asset lifecycle services are taking a larger role alongside the long running records management operation.
- We will now look at how Iron Mountain's investment narrative is affected by this guidance raise and record data center leasing performance.
Scan other data center and infrastructure plays showing similar momentum by checking our curated list of 53 AI infrastructure stocks.
Iron Mountain Investment Narrative Recap
To own Iron Mountain, you need to believe the shift from paper storage to data centers, asset lifecycle management and digital services can more than offset any eventual drag from legacy records. The analyst consensus Narrative on Simply Wall St leans on that mix of old and new. The latest quarter shows that thesis is still being tested in real time rather than reset.
Right now, the key near term catalyst is execution on data center capacity and AI focused demand, because large builds and long contracts shape future cash flow. The biggest risk remains the heavy capital needs and leverage that sit behind those projects, since delays or weaker utilization can quickly pressure interest coverage and dividend headroom.
The clearest new data point for that thesis is the raised 2026 revenue outlook to US$7.95b to US$8.02b, alongside guidance for US$1,980m of fourth quarter revenue. Those figures, plus the record 102 megawatts of leasing and US$575m backlog, give investors more concrete numbers to weigh against the earlier capacity and AI demand story.
Higher full year expectations matter because they land alongside a 15% dividend increase to US$0.993 per share, which ties cash returns more tightly to this expanded build out. If you are tracking catalysts, you are really watching whether the stronger revenue base and leasing momentum are enough to comfortably fund growth CapEx, interest costs and that larger dividend without stretching the balance sheet.
Iron Mountain's narrative projects US$10.2b revenue and US$926.2 million earnings by 2029. That profile assumes 9.3% yearly revenue growth and roughly a doubling of earnings from US$458.5 million today to the 2029 consensus level.
Uncover why Iron Mountain's fair value indicates a 33% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most cautious analysts focus on margin pressure rather than headline growth at Iron Mountain. They were pencilling in about US$9.0b of revenue and US$554.4 million of earnings by 2029, which is far below the consensus path. That more pessimistic story may shift after this guidance and dividend news, so explore both sides.
Explore 4 other Iron Mountain fair value estimates, including one that suggests it could be worth just $141.36!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Iron Mountain research is our analysis highlighting 4 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Iron Mountain. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Iron Mountain's overall financial health at a glance.
Looking for more investment ideas beyond Iron Mountain?
If Iron Mountain has you thinking about where to deploy the next dollar, it can help to scan a broader watchlist so you are not relying on a single story.
- If you are hunting for businesses that the market may be overlooking, use our screener to scan 19 high quality undiscovered gems that already show strong fundamentals.
- If resilience and balance sheet strength matter most to you, run a quick filter over our list of solid balance sheet and fundamentals (25 results) and focus on companies with the capacity to ride out tougher conditions.
- If you are building an income focused portfolio, shortlist potential candidates with our curated set of 7 dividend fortresses that pair higher yields with fundamental data you can interrogate in a few clicks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com