


EN
Community Trust Bancorp (CTBI) Has Investors Asking A Bigger Question
Community Trust Bancorp (CTBI) is in focus after sharply higher provisions for credit losses tied to a single commercial lending relationship, a legal investigation, and a subsequent share price drop drew fresh attention to the stock.
Despite the recent legal investigation and higher credit costs, Community Trust Bancorp’s share price has pulled back over the past month and quarter, with a 30 day share price return of 6.8% lower and a 90 day share price return of 10.8% lower as investors reassess risk. That short term pressure contrasts with a stronger picture on longer horizons, where total shareholder return over 1 year is 35%, around 99% over 3 years and about 87% over 5 years. This points to momentum that has built over time rather than faded.
Scan how Community Trust Bancorp compares with other regional financials facing renewed credit and legal pressure by reviewing our hand picked 31 resilient stocks with low risk scores in the same space.
Community Trust Bancorp has slipped on legal and credit worries while its longer term track record remains intact. Is this the moment to step in, or does patience for a cheaper entry make more sense before the valuation work starts?
Preferred Price-to-Earnings of 11.4x: Is it justified?
Community Trust Bancorp trades on a P/E of 11.4x, which sits close to the broader US Banks average of 11.3x and slightly above the modelled fair P/E of 10.9x from the SWS fair ratio framework.
The P/E ratio compares the current share price to earnings per share. For a regional bank like Community Trust Bancorp, it gives a quick read on how the market is pricing its profit stream, including factors such as credit costs, legal risks, return on equity and growth expectations.
CTBI’s current valuation looks modest relative to peers, since its 11.4x P/E is lower than the 12.1x peer average. However, the stock also screens as a little expensive versus the 10.9x fair P/E level that the SWS fair ratio suggests the market could gravitate toward if sentiment normalises.
Explore the SWS fair ratio for Community Trust Bancorp.
Result: Price-to-Earnings of 11.4x (ABOUT RIGHT)
Still, Community Trust Bancorp faces ongoing risks from the legal investigation and from any further credit issues tied to that concentrated commercial lending relationship.
Find out about the key risks to this Community Trust Bancorp narrative.
Another View on Community Trust Bancorp’s Valuation
The P/E discussion paints Community Trust Bancorp as only slightly rich versus its fair ratio. A different lens tells a stronger story. The SWS DCF model estimates a future cash flow value of $109.04 per share versus the current $69.11 price. This comparison points to a wide undervaluation gap.
That 36.6% discount suggests the market is pricing legal and credit headlines far more harshly than the long term cash generation implied by the DCF. It raises a key question for investors: Is the model too optimistic about future cash flows, or is sentiment overreacting to near term risk?
Look into how the SWS DCF model arrives at its fair value.
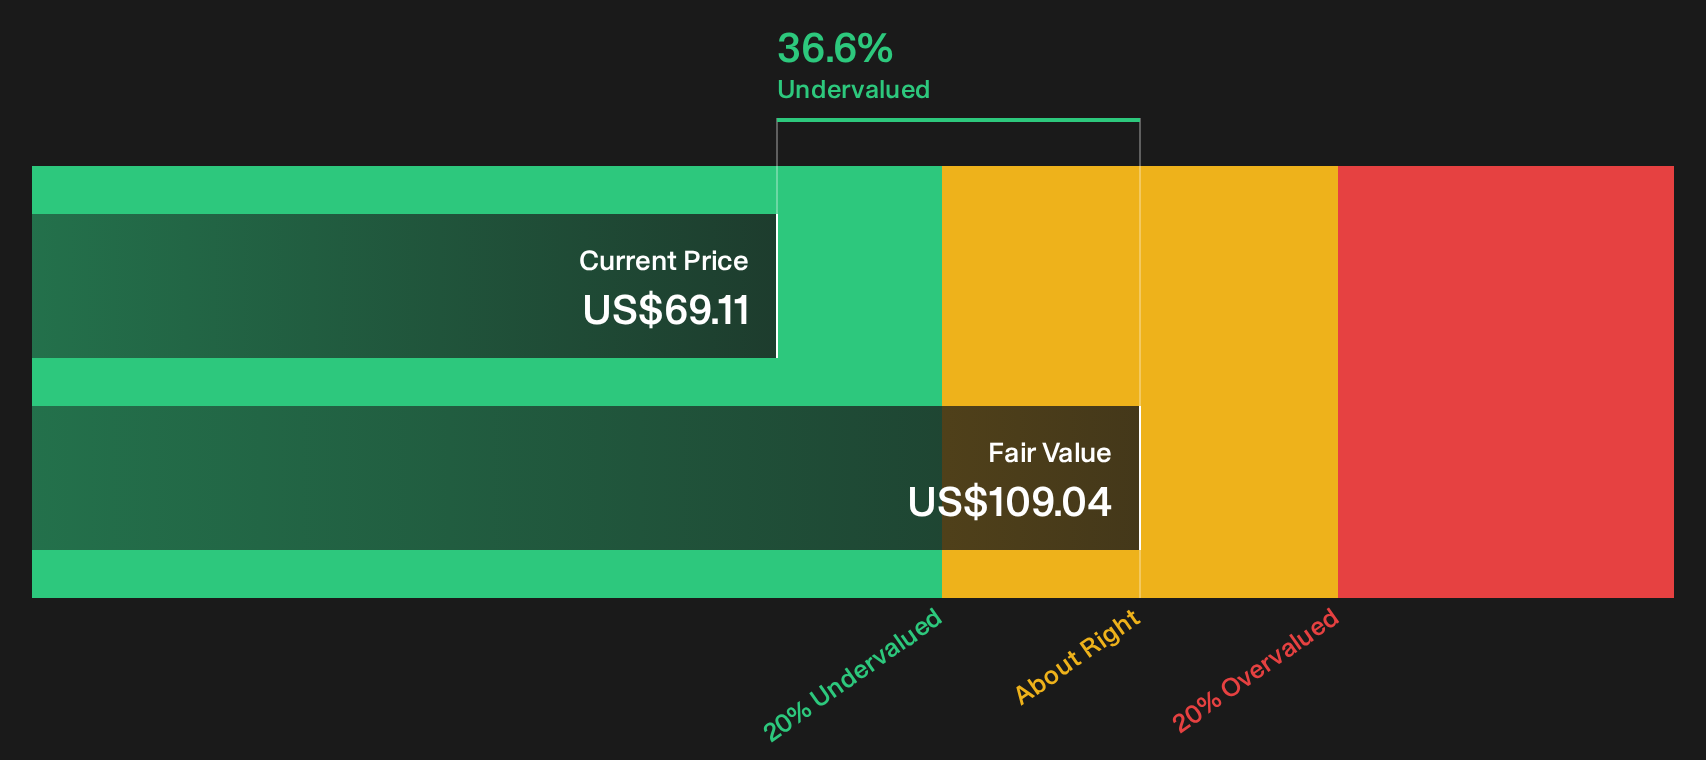
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Community Trust Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Community Trust Bancorp is clearly split, with legal and credit worries set against earlier gains and a modelled valuation gap that looks wide. If you want to move quickly and shape your own view, weigh both sides of the story with the 4 key rewards and 1 important warning sign
Looking for more investment ideas beyond Community Trust Bancorp?
Once you have a view on Community Trust Bancorp, broaden your opportunity set with a few focused stock ideas sourced from the Simply Wall Street Screener.
- Target resilient balance sheets and steady fundamentals by scanning our hand picked list of solid balance sheet and fundamentals (25 results) to keep financial risk in tighter check.
- Pursue potential mispricings by reviewing the curated 40 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Strengthen your income watchlist by running through a focused set of 7 dividend fortresses designed to highlight higher yielding payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com