


EN
Earnings Slump Might Change The Case For Investing In Boyd Gaming (BYD)
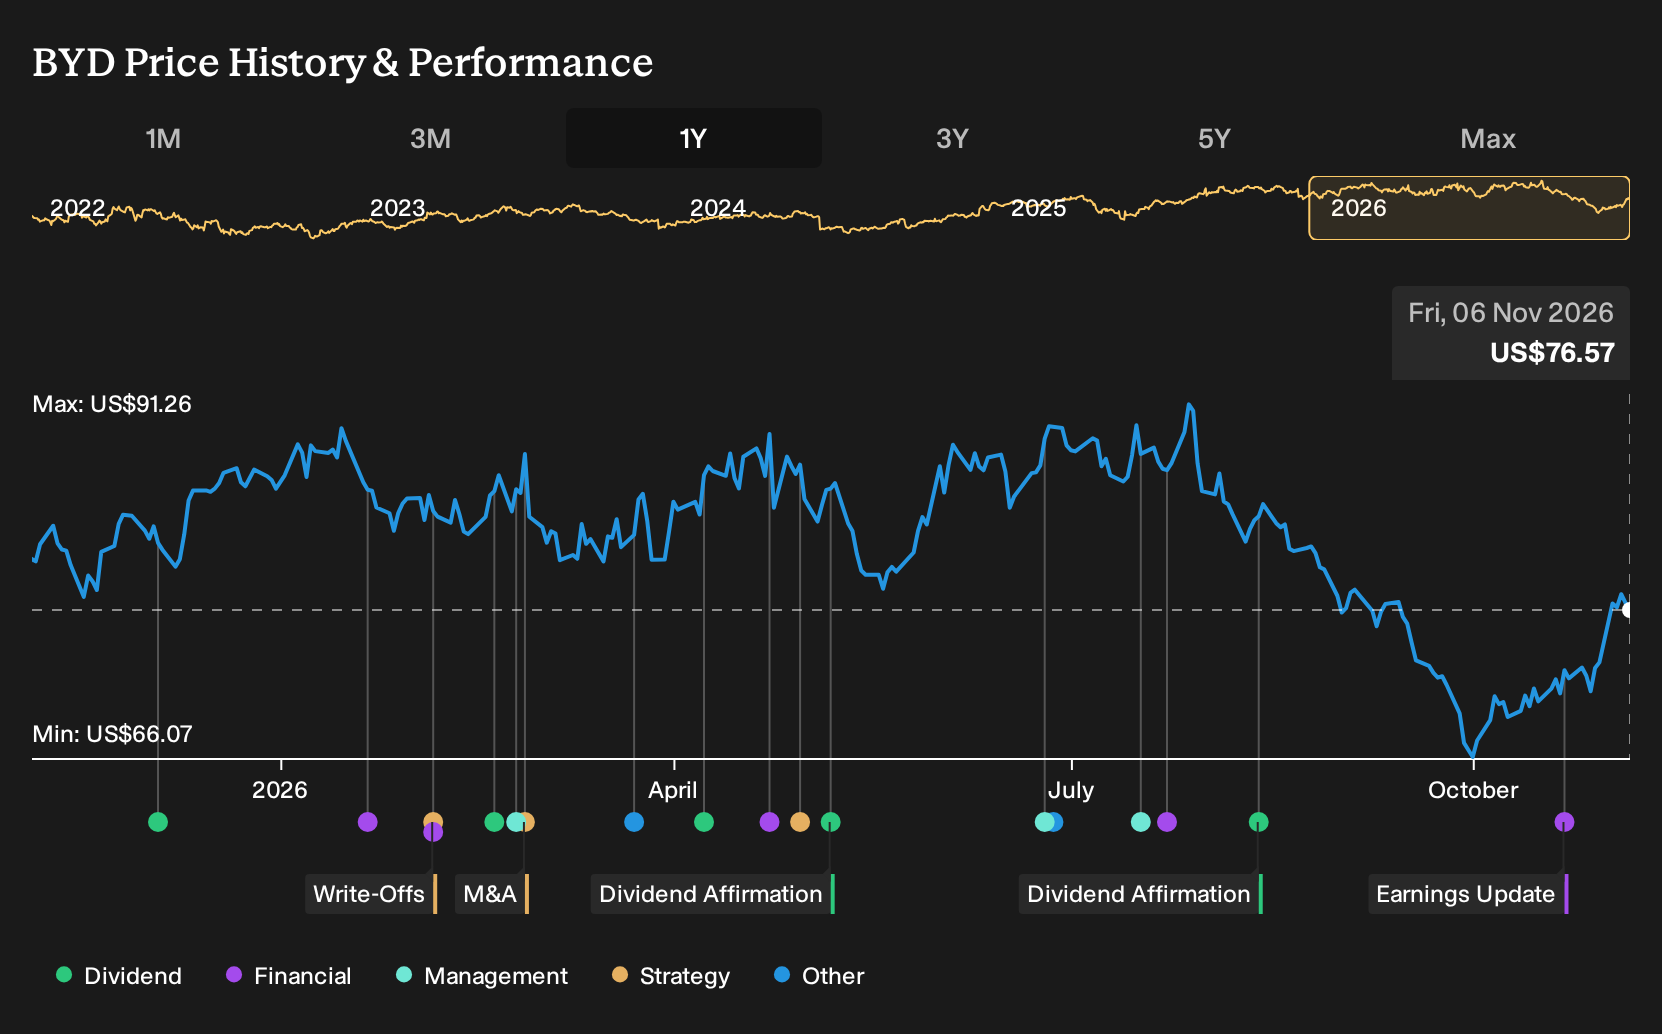
- Boyd Gaming recently reported quarterly results that showed a 1.4% decline in revenue and a 90.4% drop in earnings per share compared with a year earlier.
- The sharp earnings contraction, alongside only modest top line pressure, points to cost structure and mix issues that matter more than headline revenue trends.
- We will now look at how Boyd Gaming's steep earnings per share decline could reshape the longer term investment narrative for the group.
Compare Boyd Gaming's latest setback with other operators facing similar profit pressure by scanning our hand picked 40 high quality undervalued stocks, which may pair stronger earnings resilience with more attractive pricing.
Boyd Gaming Investment Narrative Recap
For Boyd Gaming, the core belief is that its locals, regional casinos and online operations can offset pressure in destination properties and keep profits supported over time. The latest quarter cut into that story. A 1.4% revenue dip alongside a 90.4% earnings per share decline highlights how sensitive the group is to cost mix, construction disruption and weaker high margin business.
The analyst consensus narrative on Simply Wall St leans heavily on returns from the multi year capex program, Boyd Interactive and managed tribal fees. The key near term swing factor is whether projects like Suncoast and Cadence Crossing ramp without further EBITDAR drag. The biggest near term risk remains ongoing construction and softer destination visitation limiting margins.
Recent commentary around projects such as the Suncoast modernization and Norfolk resort plans matters more now that earnings per share have dropped so sharply. Construction has already reduced quarterly EBITDAR by about US$3 million, so any delay or extended disruption makes the current earnings pressure harder to absorb and stretches the payback timeline on that spend.
On the flip side, completion of these refurbishments and new builds, together with Boyd Interactive and the Sky River managed partnership, still offers a path to more fee based and online EBITDAR that is less capital intensive. For you as a shareholder or prospective investor, execution on these projects and how cleanly they move from drag to contributor now sits at the center of the Boyd Gaming thesis.
Boyd Gaming's outlook indicates projected revenue of US$4.4b and earnings of US$526.7m by 2029. This is based on an assumed 2.7% annual revenue growth rate and an estimated earnings increase of about US$24.6m from US$502.1m today.
Uncover why Boyd Gaming's fair value indicates a 14% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
Four fair value estimates from the Simply Wall St Community span an extremely wide band, from about 0.39 up to almost 149, which signals how far opinions on Boyd Gaming can spread. When you set that against risks like prolonged construction disruption or softer destination demand, the case for checking multiple viewpoints becomes clear.
Explore 3 other Boyd Gaming fair value estimates, including one that suggests as much as 99% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Boyd Gaming research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Boyd Gaming. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Boyd Gaming's overall financial health at a glance.
Looking For More Investment Ideas Beyond Boyd Gaming?
If Boyd Gaming has sharpened your focus on risk, reward and execution, it can help to widen the lens and compare it with other companies filtered by the traits you care about most. The Simply Wall St Screener lets you jump straight to groups of stocks that match different quality, value and resilience themes.
- For investors hunting for stronger balance sheet support around future cash flows, start with a list of solid balance sheet and fundamentals (25 results) that filters for sturdier financial foundations.
- If capital preservation and smoother return profiles matter more to you than chasing every upside swing, zero in on companies from our 31 resilient stocks with low risk scores that screen well on lower risk characteristics.
- When you want to stay open to mispriced opportunities with healthier fundamentals, broaden your watchlist using a 19 high quality undiscovered gems that highlights underfollowed, higher quality candidates.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com