


EN
Karooooo (KARO) Gains Attention As Earnings Optimism Puts Valuation In Focus
Karooooo (KARO) is back on investors’ radar after a wave of optimism tied to favorable growth scores and upward revisions to current year earnings estimates, which point to rising confidence in its outlook.
Recent price action has cooled slightly, with the share price down 2.8% over the past week after a modest 3.1% one‑month share price gain. However, a 41.0% year‑to‑date share price return and a three‑year total shareholder return of about 1.8x suggest momentum in Karooooo is still broadly intact as earnings optimism builds into the current US$62.98 level.
Scan beyond Karooooo and line up other fast growing software and tech platforms using our hand picked 19 high quality undiscovered gems, which share a similar earnings momentum story.
Karooooo has already delivered a strong run. Yet at roughly US$63, with current earnings expectations still resetting higher, are investors looking at gains that have mostly played out, or at further upside that valuation can still justify?
Most Popular Narrative: 14% Undervalued
On the analyst consensus Narrative on Simply Wall St, Karooooo trades below an implied fair value of about $73, compared with the last close at $62.98. This points to a valuation gap that hinges on execution in subscriptions and margins.
Ongoing expansion of Karooooo’s mobility platform into large, underpenetrated regions such as Southeast Asia, the Middle East and Europe, where subscriber growth is running ahead of reported subscription revenue growth, can add substantial incremental ARR and support future subscription revenue and earnings.
Rising cross selling of AI camera video and Cartrack Tag, both still at relatively low penetration across the installed base yet already contributing to ARPU uplift and new subscriber wins, creates headroom for higher subscription revenue and improved unit economics.
See why 34 investors see Karooooo as 14% undervalued.
Result: Fair Value of $73.46 (UNDERVALUED)
Still, the Karooooo story can unravel if subscriber growth in lower ARPU regions fails to translate into matching subscription revenue, or if heavier sales and marketing spend drags on earnings for longer than expected.
Find out about the key risks to this Karooooo narrative.
Another View: Karooooo Through The P/E Lens
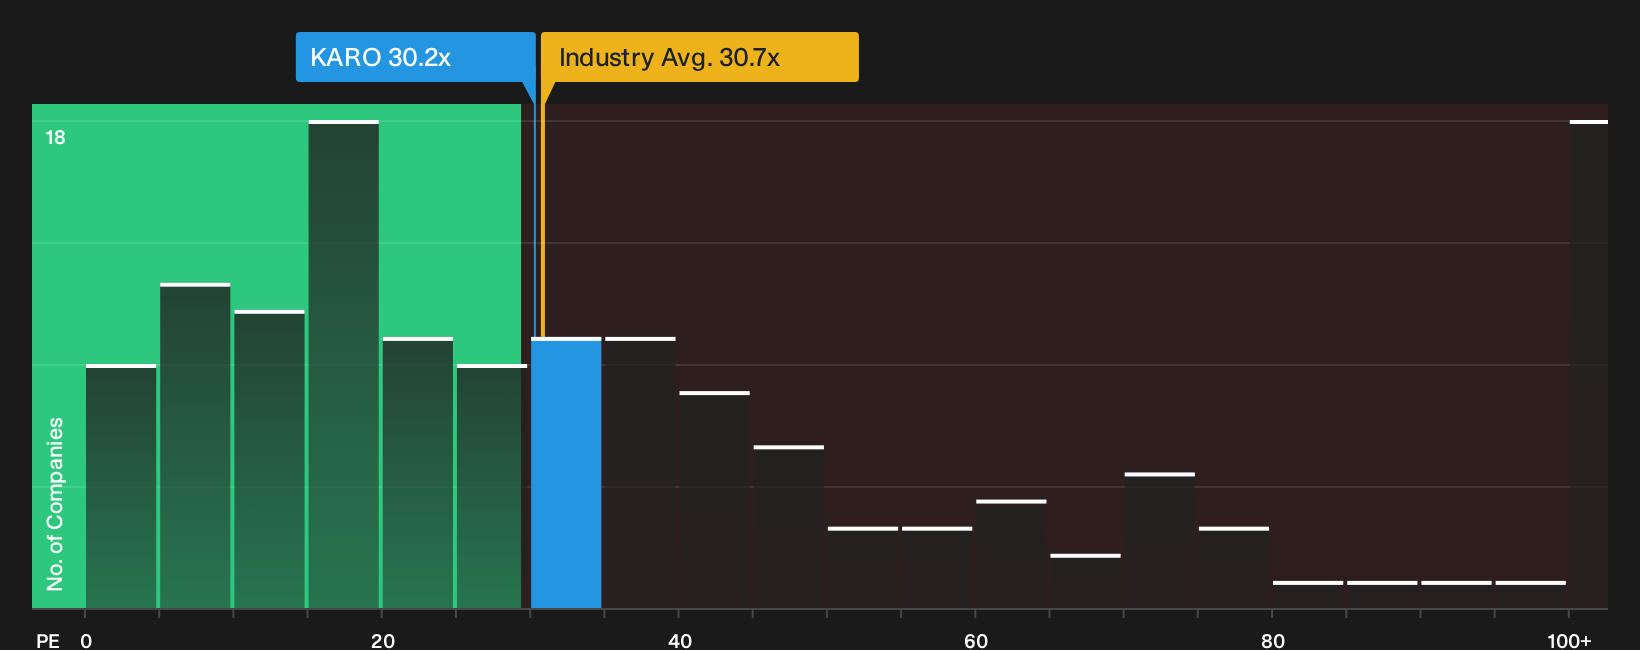
Karooooo looks different once you swap the fair value narrative for simple earnings multiples. The stock trades on a P/E of 30.2x, just below the US Software sector on 30.7x and well under peer levels at 53.2x, yet above its own fair ratio of 24.4x, which points to some valuation risk if sentiment cools.
That gap between today’s P/E and the lower fair ratio is what you need to judge. Is the premium justified by quality and growth, or is it a margin of error that can close quickly if expectations reset, especially with a value score of 2 as a reminder to stress test the upside story.
To pressure test that view against simple earnings multiples, walk through the valuation breakdown and see what the numbers imply about upside and downside risk in Karooooo’s current price See what the numbers say about this price — find out in our valuation breakdown.
Put that picture next to how the P/E stacks up against peers and the broader software sector to see whether the current tag on Karooooo feels stretched or still reasonable at a glance
Next Steps
If this Karooooo story appears finely balanced between optimism and caution, consider reviewing the details promptly so you can form your own stance using the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Karooooo?
Karooooo may already be on your radar, but fresh ideas often come from scanning the wider market and lining up stronger, cleaner opportunities side by side.
- Target resilient balance sheets and steady fundamentals by checking companies in the list of solid balance sheet and fundamentals (25 results).
- Hunt for potentially mispriced opportunities by reviewing the 40 high quality undervalued stocks before other investors catch on.
- Focus on consistency and capital protection by filtering candidates through the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com