


EN
Top 3 Canadian Insider Stocks To Watch In November 2026
Google’s rapid push into AI chips, with forecasts for its TPU sales to grow more than 11 times by 2028, has sharpened attention on businesses tied to data, software and automation. Investors are hunting for fast growing Canadian companies where insiders have significant skin in the game. This article highlights three such stocks and explains how strong internal ownership can align leadership with your interests.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders share in the upside. However, if you want the standouts, these 9 high growth high conviction stocks are the most outstanding.
Lightspeed Commerce (TSX:LSPD)
Lightspeed Commerce runs a cloud-based commerce and payments platform for retailers, restaurants and golf operators. This fits the screener’s focus on fast growing, software led business models with management leaning into that opportunity. The stock has a market value of about CA$1.9b.
The analyst consensus narrative on Simply Wall St frames Lightspeed as a payment centric software platform where higher adoption of its own checkout rails is central to the growth story and to management’s optimism about earnings power.
Ongoing lift in payments penetration, which reached 44% of GTV overall and 49% in the growth engines in Q1 fiscal 2027 with efficiency markets at 32%, provides scope for more high-margin transaction revenue as a greater share of customer volumes moves onto Lightspeed Payments.
The real swing factor is how one less visible shift in the mix of software, payments and financial services affects margins and cash generation.
That mix shift is exactly what the full narrative for Lightspeed Commerce unpacks, showing how payments penetration, capital allocation and competitive pressure could reshape Lightspeed Commerce’s earnings engine.
Ivanhoe Mines (TSX:IVN)
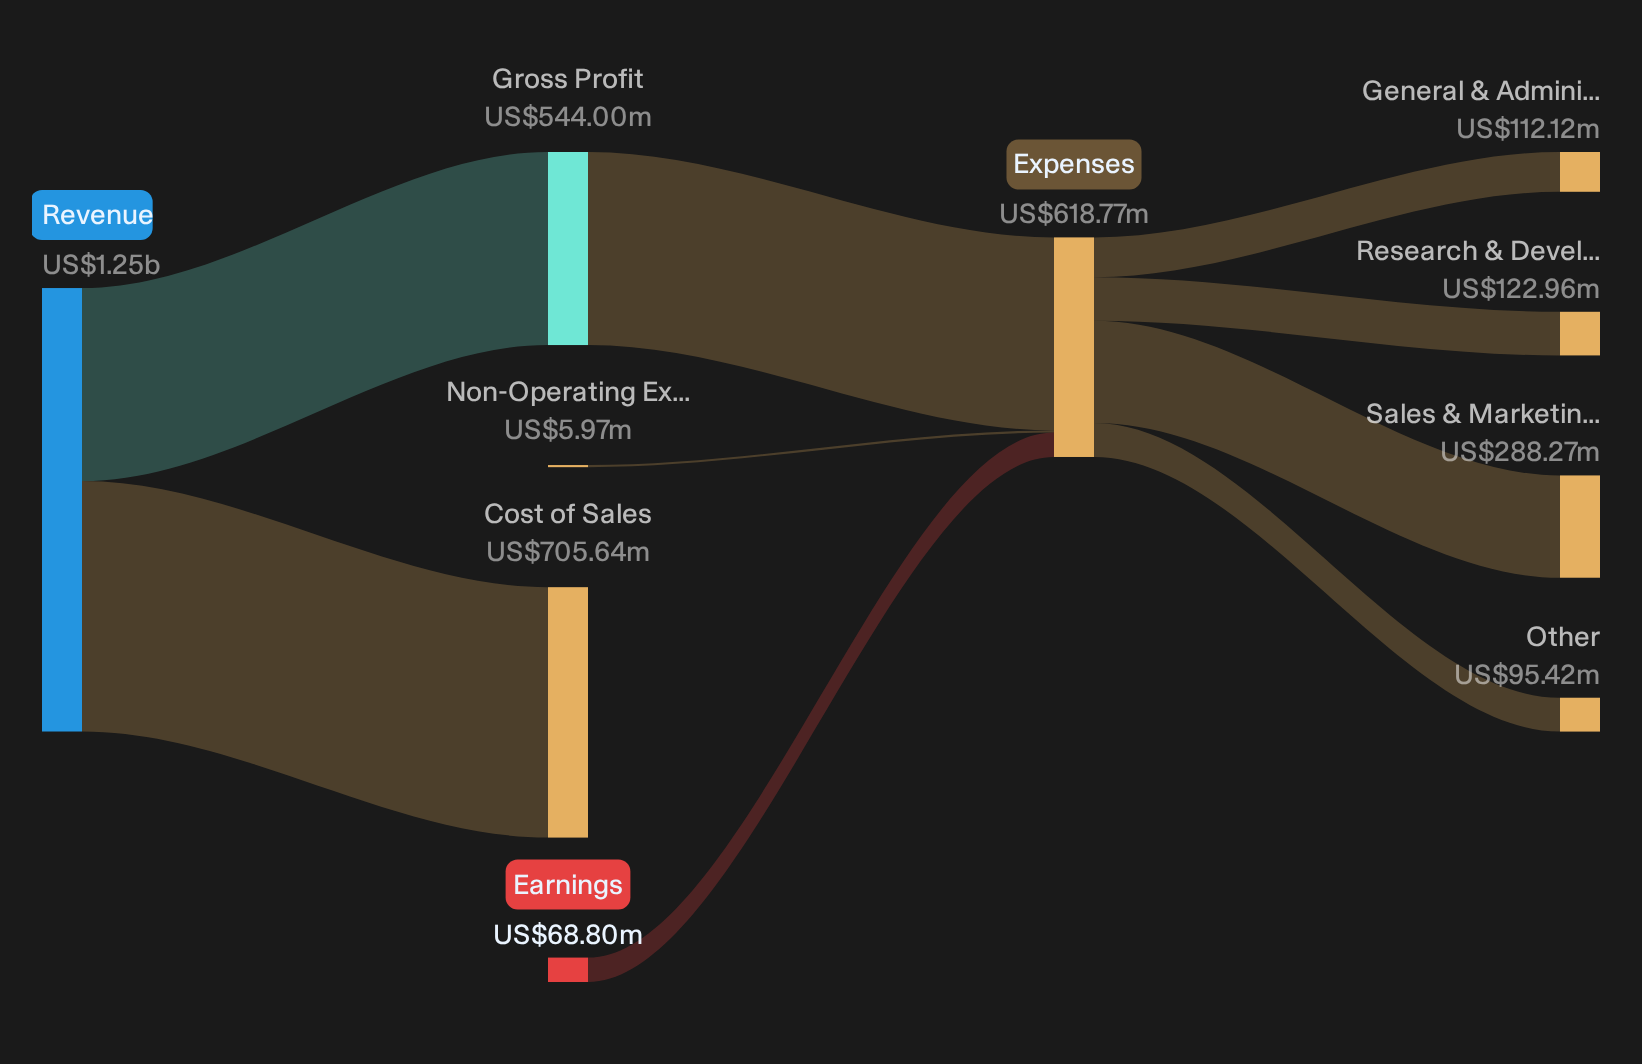
Ivanhoe Mines is a Vancouver based miner focused on copper, zinc and platinum group metals, with the fast growing Kamoa-Kakula Copper Complex anchoring its fit with the screener’s growth theme. Kipushi Properties generated about $700 million, and the stock is valued around CA$11.8b.
For Ivanhoe Mines, the fast growth story investors care about largely flows through Kamoa-Kakula, which Agricola, an investor in the Simply Wall St Community, describes as part of a bigger set of projects that management is working to scale over time.
Catalysts stacked (Phase 3/4 Kamoa ramp to >550 ktpa medium-term, Platreef Phase 2, Kipushi de-bottlenecking, smelter online, Project 95 recoveries, exploration).
What matters next is how one unresolved cost and funding pressure shapes the payoff from all that planned production growth.
That funding question is exactly what the full narrative for Ivanhoe Mines unpacks. It maps where capital strain could ease, where returns might accelerate, and which risks could still stall Ivanhoe Mines.

Cascades (TSX:CAS)
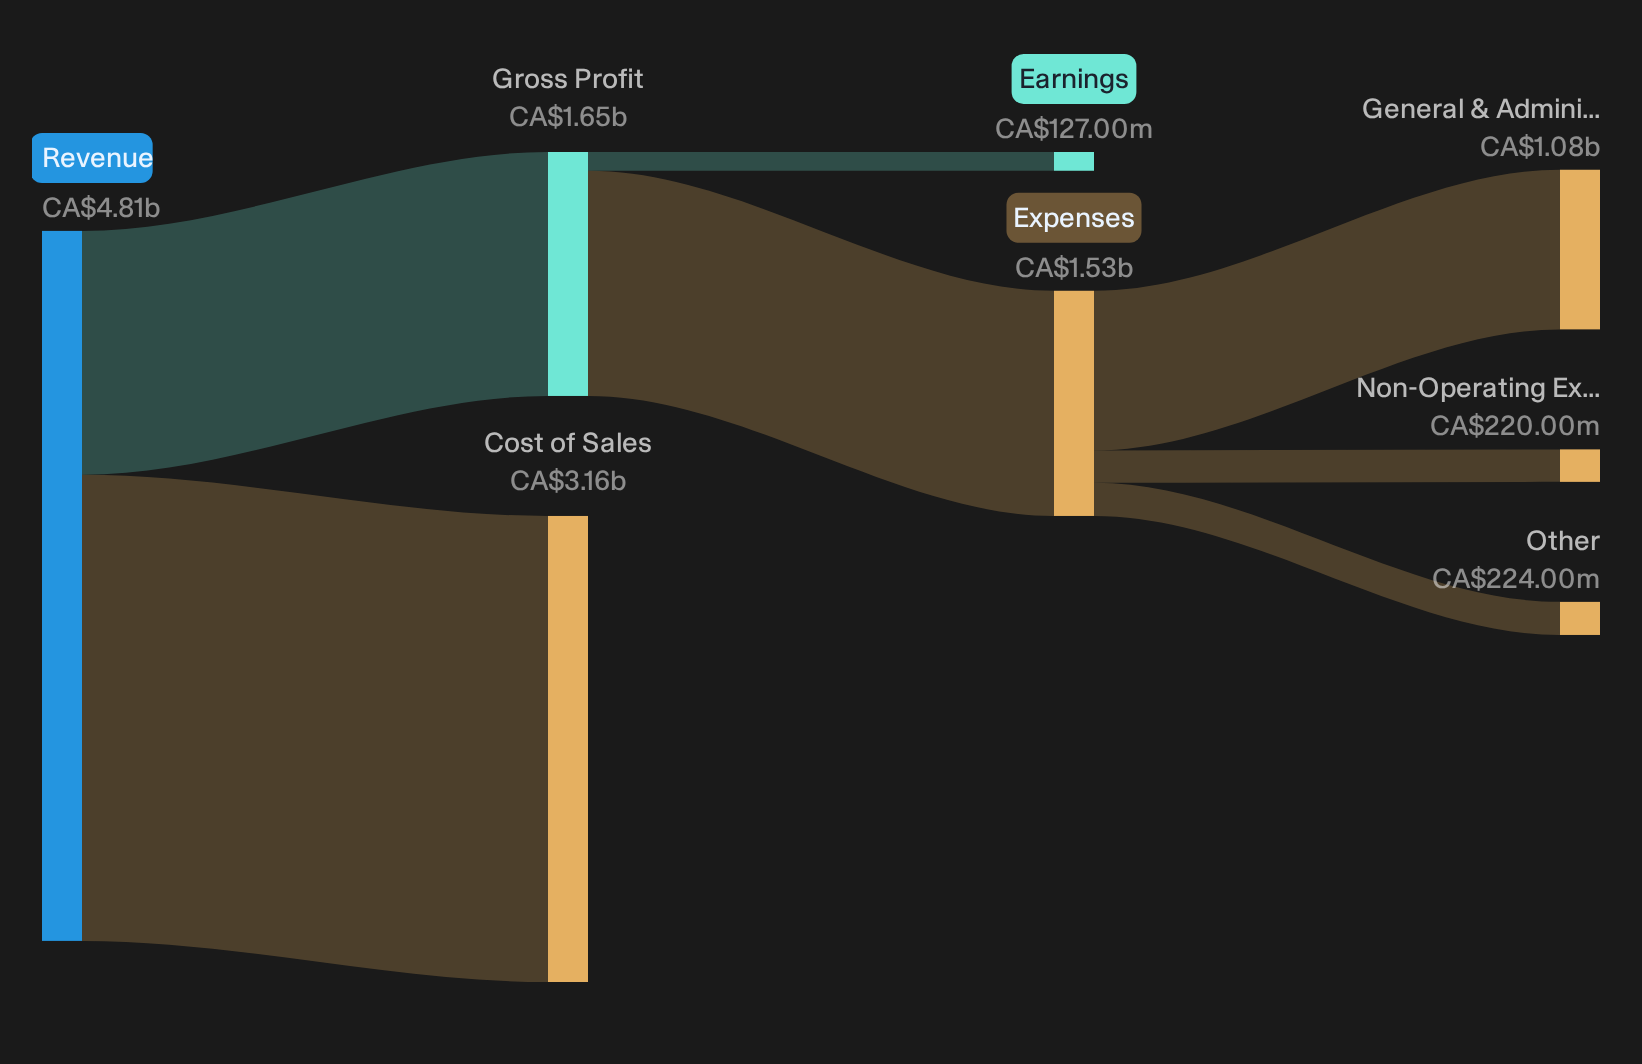
Cascades is a CA$1.6b packaging and tissue producer that leans into high growth e commerce and logistics demand through its specialized packaging solutions, particularly adjustable boxes and protective mailers, while keeping a broad base in recycled fiber products and related services.
The Packaging Products segment puts Cascades squarely in the Fast Growing Stocks With High Insider Ownership theme, since its e commerce and protective packaging lines plug directly into rising parcel volumes and the need for sturdier, greener shipping materials flagged in the bearish analyst Narrative on Simply Wall St.
Although the company is progressing on its cost reduction program and asset sales, persistent inflation in fiber and energy inputs and a tight transportation market could absorb a meaningful share of these savings, limiting net margin and free cash flow improvement.
Everything now turns on how one quiet shift in pricing power against those input costs shapes both the recovery in margins and the growth story.
That pricing power shift is where Cascades could surprise, and the full narrative for Cascades shows how input headwinds might be decoupling from long term earnings potential.
Seeking Alternatives Before Others Catch On?
Fresh momentum stories rarely stay quiet for long. Before the best entry points get caught in the rush and pricing flies away under the radar for now, consider acting early.
- Spot strong income plays early by scanning the 3 dividend fortresses, which aims to keep yields flowing even when prices start dropping or sentiment turns cautious.
- Track future-facing hardware momentum with the 53 AI infrastructure stocks before investor attention fully shifts toward the suppliers behind each AI breakout.
- Hunt early compounding potential through the 9 resilient stocks with low risk scores, curated to highlight businesses where calmer price action can still pair with firm operational progress.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com