


EN
Is Kratos Defense & Security Solutions (KTOS) Undervalued After Mixed Third Quarter Results?
Kratos Defense & Security Solutions (KTOS) just posted third quarter 2026 results that combined sharply higher revenue with a small net loss, a mix that quickly put profitability and cost trends under the spotlight.
The mixed Q3 update arrived after a tough stretch for Kratos Defense & Security Solutions shareholders, with the share price falling 55.73% year to date and the 1-year total shareholder return down 54.93%. However, the 3-year total shareholder return is up 100.8%, which points to long term holders still sitting on sizable gains despite the recent 90 day share price decline of 43.77% and 30 day slide of 17.14%.
Capitalize on the volatility around Kratos Defense & Security Solutions by comparing it with a curated 31 resilient stocks with low risk scores that have historically shown more resilient share price behavior during earnings-driven selloffs.After a 56% year to date slide capped by a loss making quarter on higher revenue, Kratos Defense & Security Solutions now forces a simple question: Does the current price fairly reflect that risk reward mix or not?
Most Popular Narrative: 63% Undervalued
Kratos Defense & Security Solutions closed at $35.10, while the analyst consensus Narrative on Simply Wall St places fair value at $94.44. This wide gap centers the discussion on whether future contracts and production ramps justify that difference, given the 7.94% discount rate used.
Kratos Defense & Security Solutions is building a larger hypersonic franchise, with hypersonic revenue around US$200m in 2025 and forecasts of roughly US$400m in 2026 and at least US$700m in 2027. This is supported by several hundred million dollars of recent funding, new programs such as Kraken and Nemesis, 120 solid rocket motors on order, and a multi year MACH TB budget profile of about US$7b, which could materially lift future revenue and earnings power.
See why 171 investors see Kratos Defense & Security Solutions as 63% undervalued.
Result: Fair Value of $94.44 (UNDERVALUED)
Still, the Kratos Defense & Security Solutions story depends on easing FX pressure on margins and turning heavy working capital use into healthier cash generation.
Find out about the key risks to this Kratos Defense & Security Solutions narrative.
Another View: What Multiples Say About Kratos Defense & Security Solutions
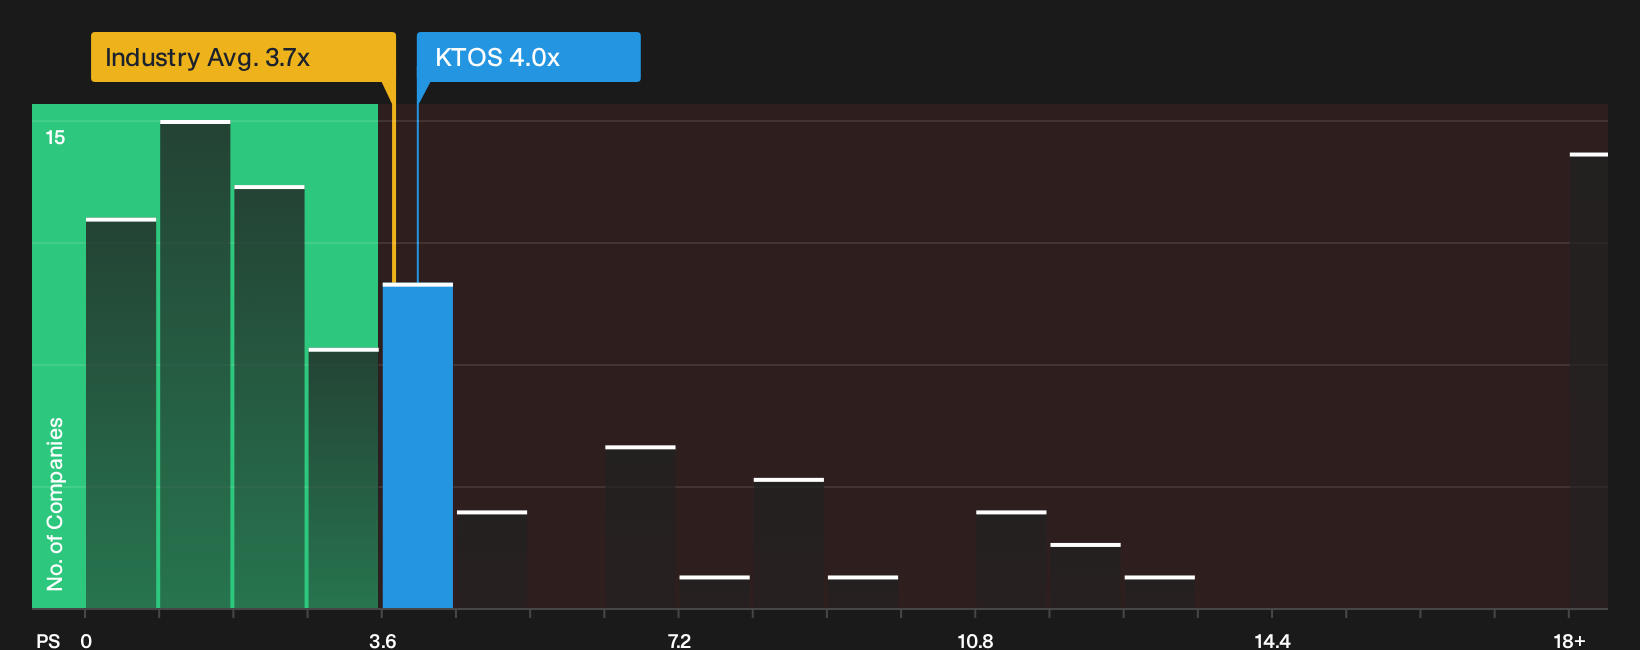
The SWS DCF model points to value, yet the market is not giving Kratos Defense & Security Solutions a free pass. The stock trades on a P/S ratio of 4x, richer than the US Aerospace & Defense industry at 3.7x and above a fair ratio of 2.6x. Is that a margin of safety or a premium for execution risk?
See what the numbers say about this price in our valuation breakdown, then compare that to the growth narrative investors are debating today: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Kratos Defense & Security Solutions can easily blur the signal, so move quickly and weigh both sides of the ledger for yourself with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Kratos Defense & Security Solutions?
If Kratos Defense & Security Solutions has your attention, do not stop your research here. Fresh ideas often come from comparing it with very different opportunities.
- Target stronger downside resilience by scanning a curated set of companies scored for sturdier profiles with 31 resilient stocks with low risk scores.
- Hunt for potential mispricings by reviewing a focused group of quality businesses trading on more modest expectations through 40 high quality undervalued stocks.
- Build your watchlist around income potential by zeroing in on companies with higher yields and sturdier payout histories using 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com