


EN
Should Fanatics Card Launch Require Action From American Express (AXP) Investors?
- American Express expanded its global basketball partnerships and rolled out a new Fanatics co-branded card that ties rewards to FanCash, while also broadening Membership Rewards so cardholders can convert points into sports-focused currency.
- This push into sports fandom, alongside firm demand for premium American Express products like refreshed Platinum cards, highlights how the business is leaning on experiential perks and loyalty mechanics to strengthen its fee and engagement engine.
- We will now look at how this Fanatics centered card push could reshape American Express's investment narrative around premium loyalty.
American Express Investment Narrative Recap
To stay on board with American Express, you need to believe in its premium, fee heavy, closed loop model and its ability to keep affluent cardmembers engaged despite rising reward and servicing costs. According to John_Eric, an investor in the Simply Wall St Community, the bigger swing factor remains how the pending anti money laundering enforcement and Category II rules eventually filter through to capital flexibility and growth.
The expanded NBA, WNBA, USA Basketball, and Fanatics tie ups speak directly to that engagement thesis in the near term, but they do not materially change the main short term catalyst, which is clarity on the enforcement outcome. The main operational risk still sits with higher compliance spend, potential operating constraints, and how those intersect with already high debt and funding that leans on wholesale borrowing.
The Fanatics American Express Card plus NBA ecosystem expansion is the announcement that aligns most closely with the current news. It ties Membership Rewards more tightly to sports fandom, adds new ways to earn and redeem, and uses in arena and in app benefits to keep heavy spenders inside the American Express universe for travel, tickets, and merchandise.
For catalysts, this kind of experiential partnership could help support fee income and billed business if cardmember usage stays strong, particularly as American Express expects slower expense growth to support operating leverage. John_Eric argues that the unresolved anti money laundering case and Category II capital demands still sit over the investment story, so execution on compliance and funding costs will likely matter more to the medium term outlook than any single co branded launch.
John_Eric bases the American Express fair value of $444.11 on a model that assumes 12.0% annual revenue growth and a future profit margin of 16.0%. He argues that this combination reflects a mature but still expanding premium franchise, balanced against higher compliance and capital demands.
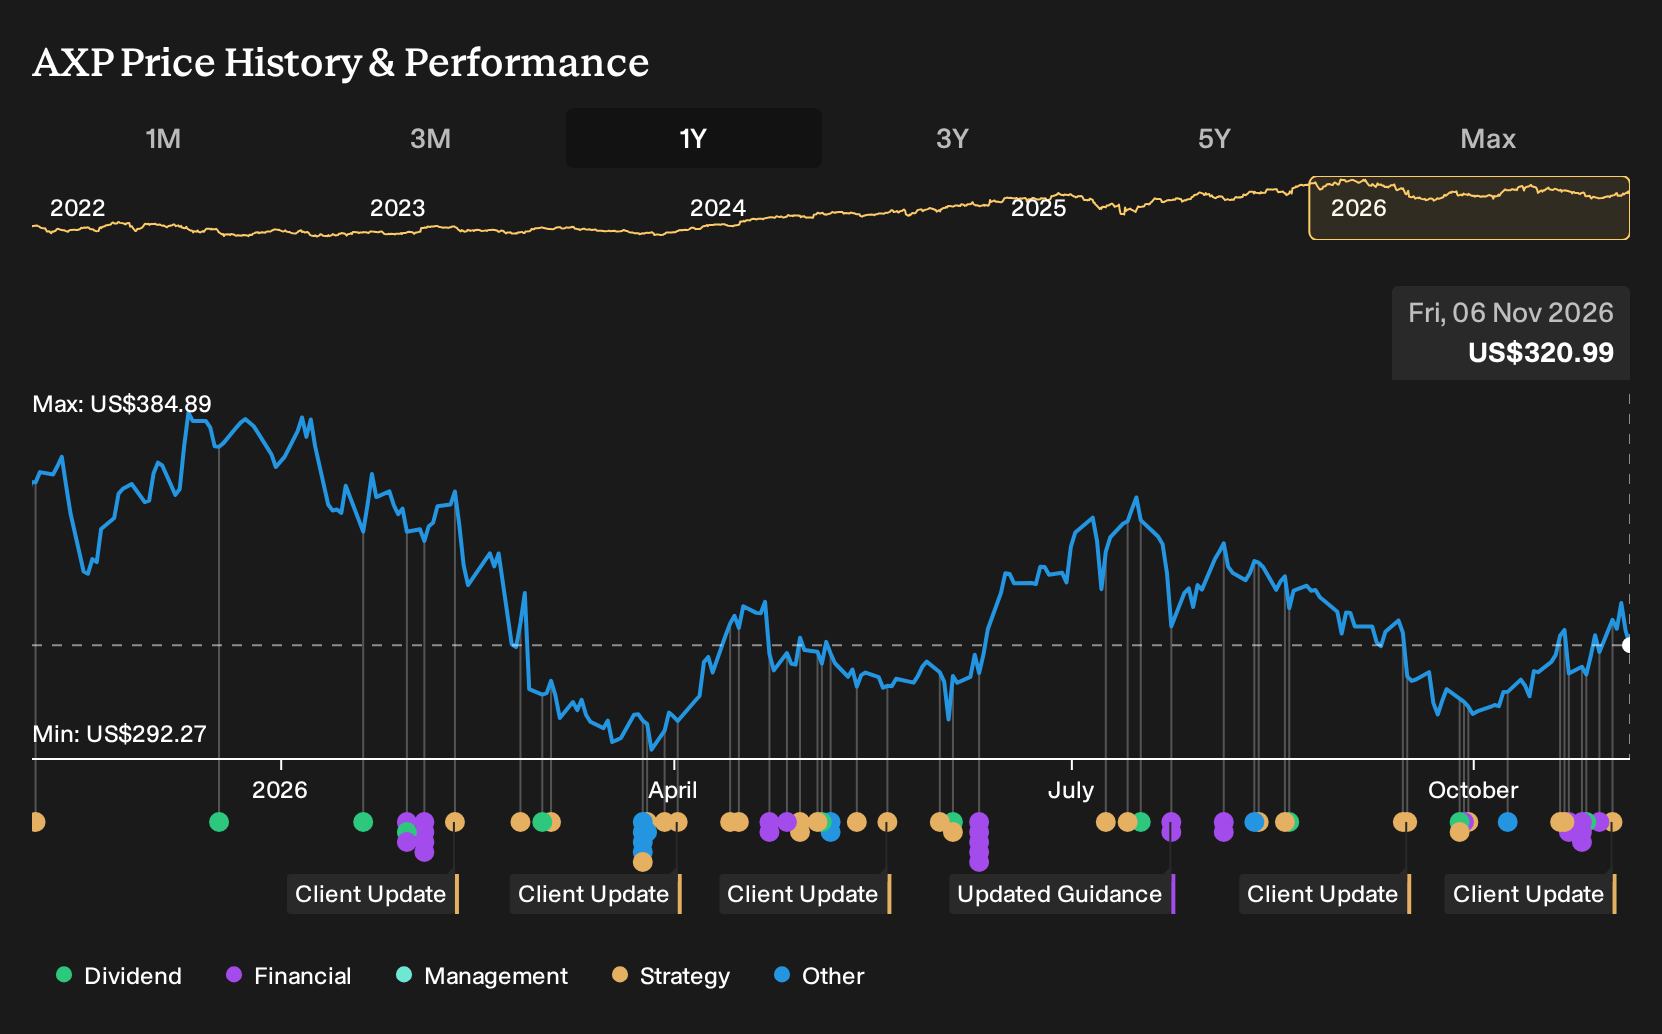
Uncover how American Express' fair value indicates a 38% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts focus less on the American Express compliance overhang and more on revenue acceleration. Before this NBA and Fanatics push, the bullish camp was already modeling about 12.2% annual top line growth and earnings reaching roughly US$16.7b by 2029. That is a far brighter story than the baseline, so it is worth comparing both views.
Explore 7 other American Express fair value estimates, including one that suggests potential upside of as much as 38% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own research and judgment.
- A great starting point for your American Express research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for American Express. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate American Express' overall financial health at a glance.
Looking for more investment ideas beyond American Express?
If the American Express story has sharpened your interest in fee driven models and strong customer loyalty, it can be helpful to compare it with other businesses that share some of those traits but sit in very different risk and return brackets. The Simply Wall St Screener gives you a quick way to surface candidates that match your preferred mix of quality, balance sheet strength, income or growth.
- If capital preservation and business resilience matter most to you, start with a set of companies that score well on stability and financial downside metrics through the 31 resilient stocks with low risk scores.
- For investors who want strong fundamentals and cleaner balance sheets to complement a core holding like American Express, filter for sturdier finances and consistent funding profiles using the list of solid balance sheet and fundamentals (25 results).
- If you are hunting for ideas that combine quality with a potential valuation gap, use the screener to surface companies flagged as promising but less widely followed through the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com