


EN
The Bet Jones Lang LaSalle Holders Made
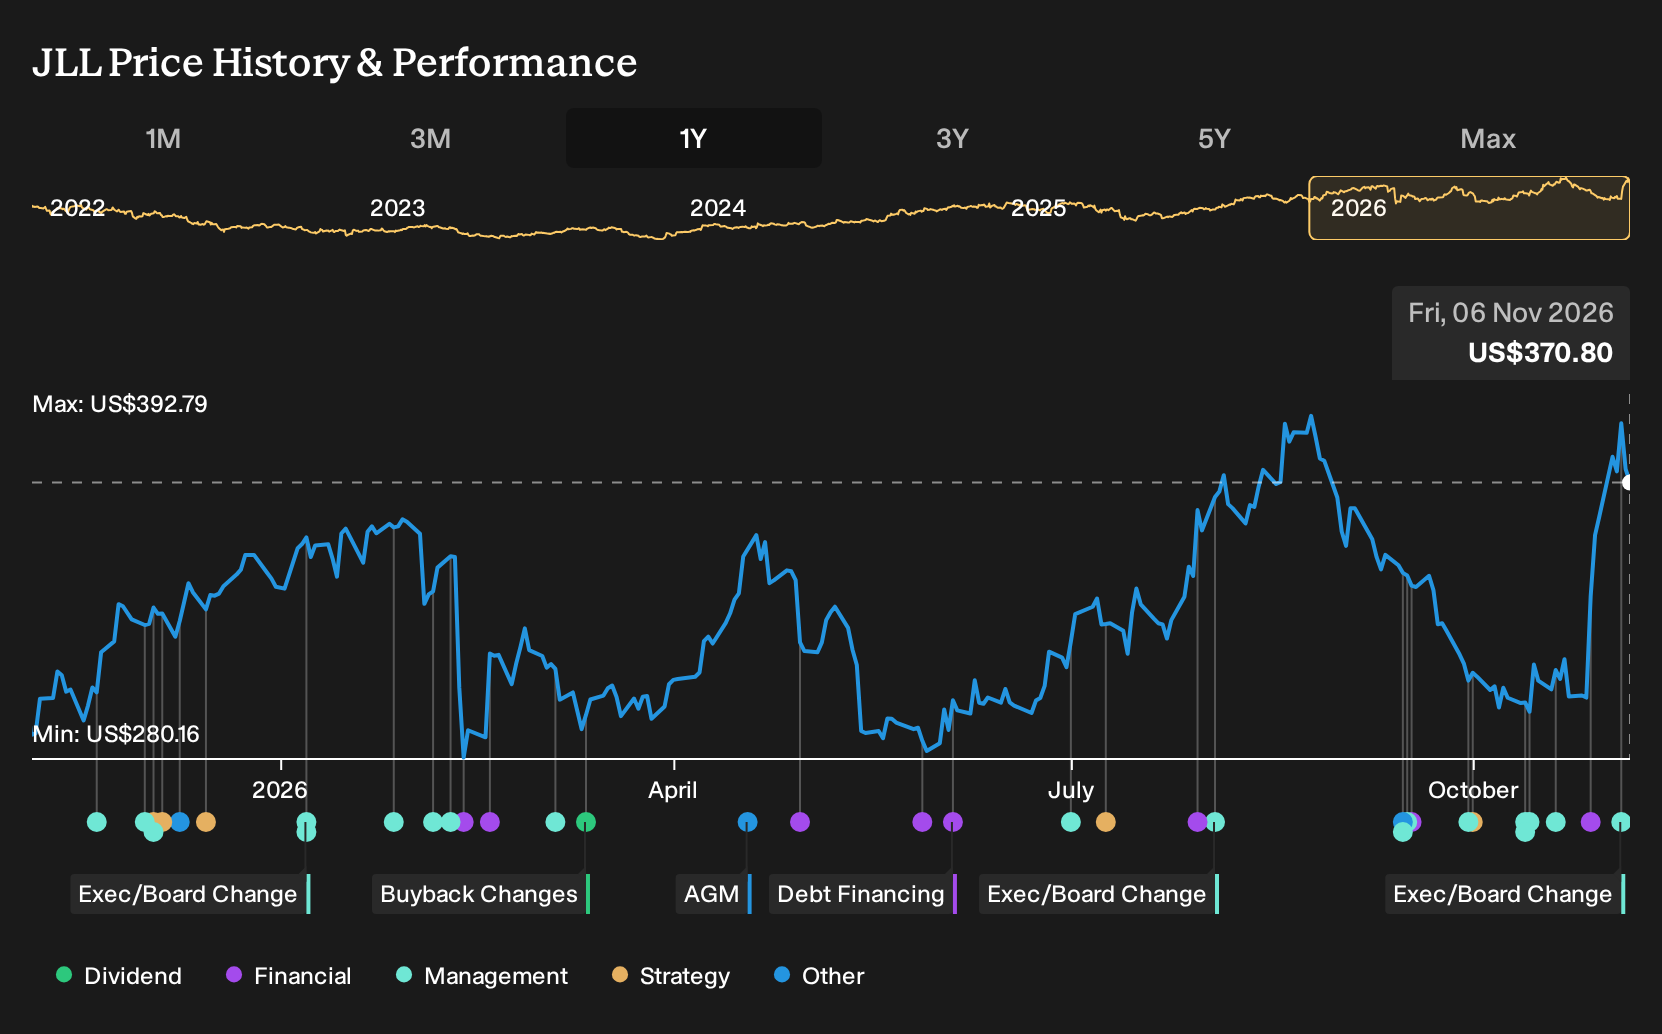
If you only glanced at headlines about remote work pressure on offices and AI disruption in real estate services, Jones Lang LaSalle might have looked like a risky place to park fresh capital. For Jones Lang LaSalle shareholders, the return over the past year was 23.7%, including dividends. If you had been weighing those bullish and bearish analyst narratives back in November 2025, what did the evidence really say about taking that risk?
The easy part of this move is behind Jones Lang LaSalle. Zero in on 40 high quality undervalued stocks for companies trading below our estimates.
The Two Stories Investors Had To Weigh On Jones Lang LaSalle
The shares cost US$288 at the start of the period, and Jones Lang LaSalle sat between two very different but plausible storylines about where the real estate cycle and office demand might go next.
On the optimistic side, one narrative saw a fair value of US$335. The price implied by those assumptions was built on revenue growth of 8.4% and profit margins reaching 3.3% over three years as recurring, tech enabled services deepened.
The more cautious view pointed to a fair value of US$236, based on pressure from remote work on office focused fees and the risk that higher rates could keep transaction activity subdued.
What The Results Changed For Jones Lang LaSalle
The headline development was JLL reporting record Q3 2026 results. Revenue reached US$7.3b and adjusted earnings per share hit US$6.85, while net income rose to US$319.8m and net margin improved from 3.4% in Q3 2025 to 4.4%. That shift in profitability supported the optimistic case that assumed better efficiency and higher margins.
The lesson is simple. When a story hinges on margin repair, track the actual net margin each quarter and compare it with the thesis, not just the top line or the share price.
What Jones Lang LaSalle’s Price Now Assumes
With Jones Lang LaSalle at US$371, the bearish analyst narrative on Simply Wall St sees its fair value as sitting below that quote, even while highlighting a large outsourced real estate services pool and expanding AI enabled workflows.
A buyer today is effectively counting on AI productivity, outsourcing and capital deployment to translate into stronger long run earnings. The key question is how the risk of fee pressure and shared efficiencies affects that assumption.
"Although Jones Lang LaSalle is tied into a real estate outsourcing market that management sizes at over US$1t and growing more than 5% annually, any slowdown in this outsourcing trend or client pushback on scope could limit the 10% annual REMS revenue growth seen since 2020 and cap future top line expansion and margin resilience."
That disagreement has a full argument behind it. → Uncover the lower Fair Value this Narrative argues for
How Could You Get There Earlier?
What if your next investment idea came before the headlines? Go straight to the companies whose prices and our estimates still disagree. Three places to start, with the names waiting behind the link.
- Company 1 - 49% below our estimate - runs an asset light hotel platform that scales through franchise partnerships and retail upsells.
- Company 2 - 40% below our estimate - handles air and ocean freight while automating customs, documentation and compliance for complex shipments.
- Company 3 - 41% below our estimate - supplies subsea production systems and secures integrated contracts spanning design through project decommissioning.
Three companies from the same screener. Open every one of the 25 solid balance sheet companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com