


EN
Will Raised Guidance Change Waters (WAT) Narrative
- Waters Corporation reported third quarter 2026 sales of US$1,767 million and net income of US$81 million, and issued full year guidance that targets total reported revenue between US$6,479 million and US$6,497 million.
- The launch of AI Powered Peak Integration in Empower Software points to Waters using automation and customer data to reshape how regulated labs handle chromatography workflows and staff time.
- This article examines how Waters' raised full year guidance, supported by AI Powered Peak Integration, fits into the broader investment narrative.
Scan beyond Waters and see how other lab automation and AI workflow specialists stack up in our hand picked 53 AI infrastructure stocks.
Waters Investment Narrative Recap
To own Waters, you need to believe the core lab instrumentation and software franchise can keep pulling through recurring consumables and service, while the enlarged portfolio from BD Biosciences and Diagnostic Solutions settles into a cleaner earnings profile. The analyst consensus Narrative on Simply Wall St leans on that idea of steadier, higher margin operations over time.
The latest quarter complicates that picture in the short term. Reported sales of US$1,767 million came with net income of US$81 million and a nine month loss of US$127 million, highlighting margin pressure and one off items. Raised full year guidance signals management confidence, yet BD integration, China weakness and recent dilution still sit as the key risks investors will keep testing against future results.
The AI Powered Peak Integration launch inside Empower Software looks most relevant here because it touches both growth and profitability levers. Waters is trying to make chromatography workflows far less manual, with customer pilots showing up to 95% fewer interventions, faster review times and lower user variability, all built on each lab's own data.
If customers adopt this premium tier at scale, it could support higher value software subscriptions and more entrenched instrument placements. That ties directly into the replacement and pharma reshoring themes in the analyst consensus Narrative on Simply Wall St. Execution risk stays real, from delivering validated deployments in 2027 to keeping models explainable and compliant, but Empower's role as a workflow hub gives Waters a tangible operational catalyst investors can watch quarter by quarter.
Waters' current analyst narrative points to US$8.2b revenue and US$1.5b earnings by 2029, built on assumed 13.3% yearly revenue growth and an earnings increase of about US$1.4b from US$98.6m today.
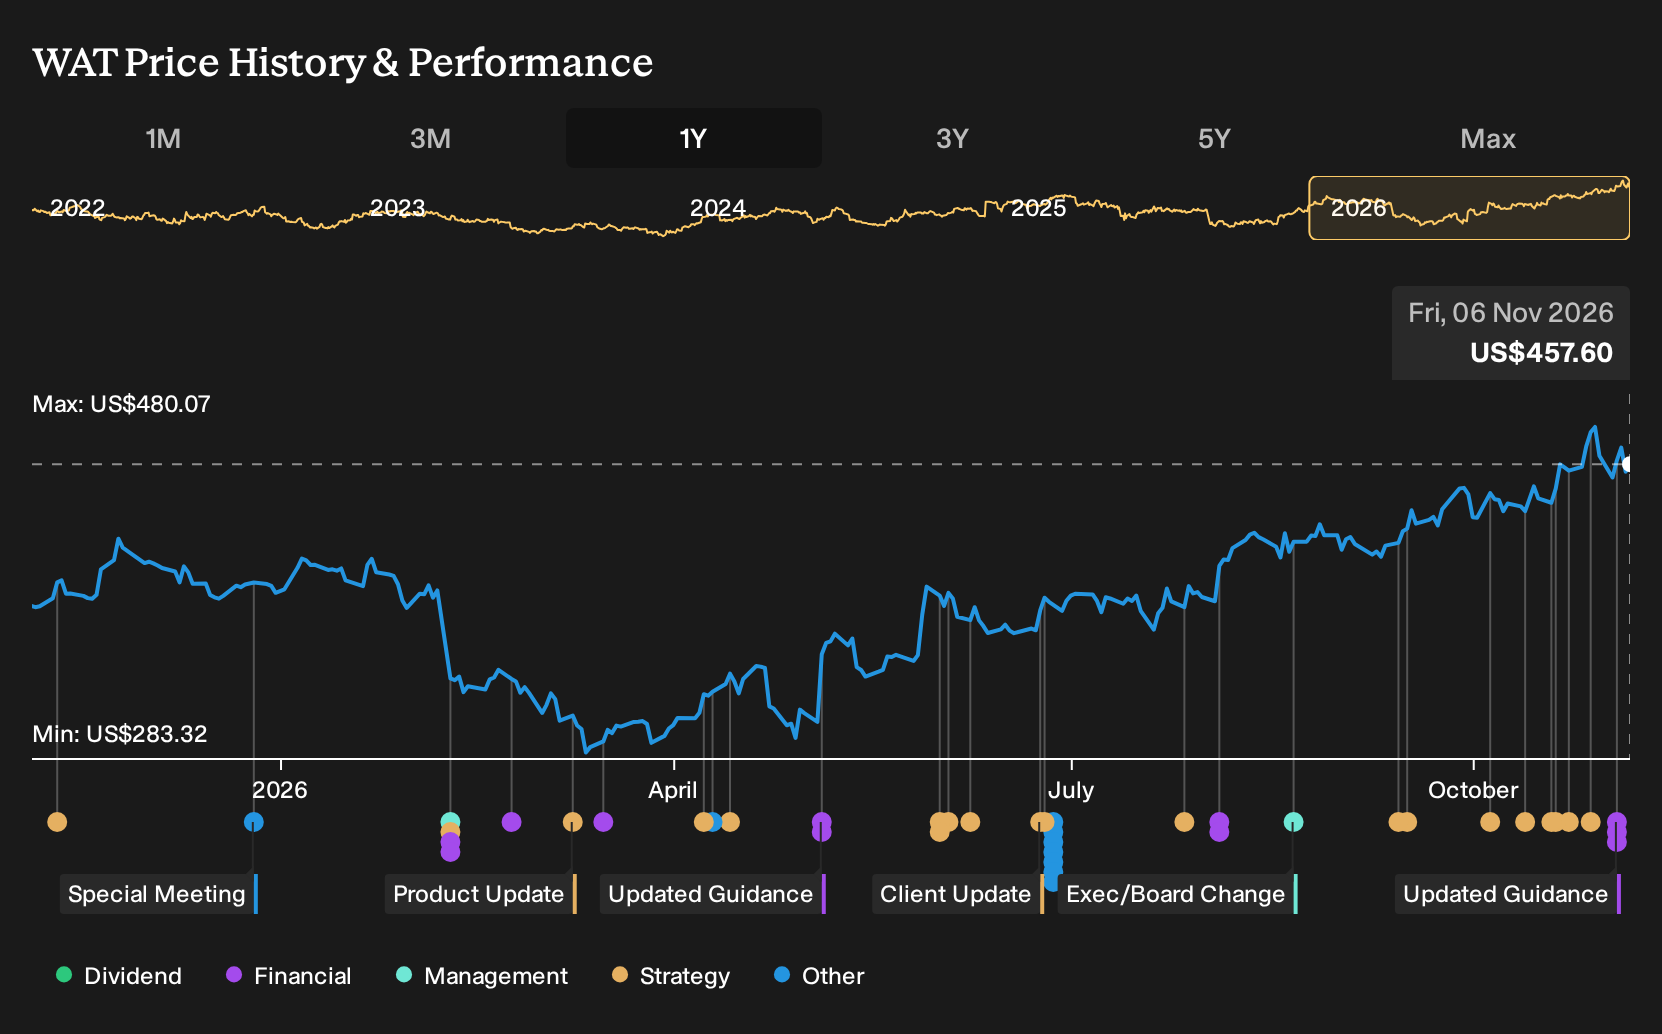
Uncover why Waters' fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One bullish twist on Waters leans heavily on AI-linked workflows as a long term earnings driver. Before this quarter, the most optimistic analysts were mapping out about US$8.7b of revenue and US$1.7b of earnings by 2029. You can use this raised guidance and the Empower AI launch to test how your own view lines up with those more aggressive forecasts.
Explore 3 other Waters fair value estimates, including one that suggests as much as 20% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Waters research is our analysis highlighting 1 key reward and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Waters. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Waters' overall financial health at a glance.
Looking for more investment ideas beyond Waters?
If you want to pressure test your view on Waters against other opportunities, a quick sweep through the Simply Wall St Screener can surface very different types of stocks that might suit your goals and risk tolerance.
- For investors who want potential mispricing on their side, review companies flagged in our 40 high quality undervalued stocks and see which ones deserve a closer look.
- If capital preservation comes first, scan through a 31 resilient stocks with low risk scores that focuses on businesses with more resilient profiles.
- Prefer dependable balance sheets over story-driven ideas, and want fundamentals to do more of the heavy lifting, then shortlist candidates from our list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com