


EN
Teleflex (TFX) Raises Outlook, Is It Still Below Fair Value?
Teleflex (TFX) just paired a raised adjusted earnings outlook with a strong third quarter, as higher sales volume, a tariff refund, and ongoing portfolio reshaping put its core Vascular, Interventional, and Surgical businesses in focus.
Teleflex’s recent guidance lift and portfolio reshaping work have arrived alongside a sharp reversal in performance. The 30 day share price return of 20.6% and 1 year total shareholder return of 41.3% contrast with a 3 year total shareholder return decline of 24.0% and a 5 year total shareholder return fall of 53.7%. This suggests that momentum has only recently rebuilt as investors reassess earnings power, buybacks, dividends, and the tuck in acquisition pipeline.
Scan Teleflex alongside other focused healthcare rebound stories by checking out the hand picked 35 healthcare AI stocks, which screen for quality and momentum in mission critical medical technologies.
After a 20.6% 30-day jump and a 41.3% 1-year gain, Teleflex now sits at a different entry point than it did for most of the past 5 years. Investors may be considering whether to lean in at current levels or wait for a reset as the valuation work starts to bite.
Most Popular Narrative: 7% Undervalued
Teleflex’s last close at $150.87 sits below the analyst consensus Narrative fair value of $161.82, which is built using an 8.02% discount rate and detailed revenue and earnings forecasts from the analyst consensus Narrative on Simply Wall St.
The multiyear restructuring program that targets about US$50 million in annual pretax cost savings by mid 2028, combined with plans to offset roughly US$90 million of stranded costs and move steady state adjusted operating margin from about 19% toward roughly 23%, provides a clear path to higher operating margins.
The integration work on the BIOTRONIK Vascular Intervention acquisition, including order to cash and sales channel adjustments that have weighed on current Interventional revenue guidance, still offers upside potential if Teleflex restores growth in these coronary and peripheral products and lifts both segment revenue and overall operating margin.
See why 8 investors see Teleflex as 7% undervalued.
Result: Fair Value of $161.82 (UNDERVALUED)
Still, the Interventional integration issues and the heavy reliance on cost savings to lift Teleflex margins could both derail the current undervaluation story.
Find out about the key risks to this Teleflex narrative.
Another View: Teleflex Through The P/E Lens
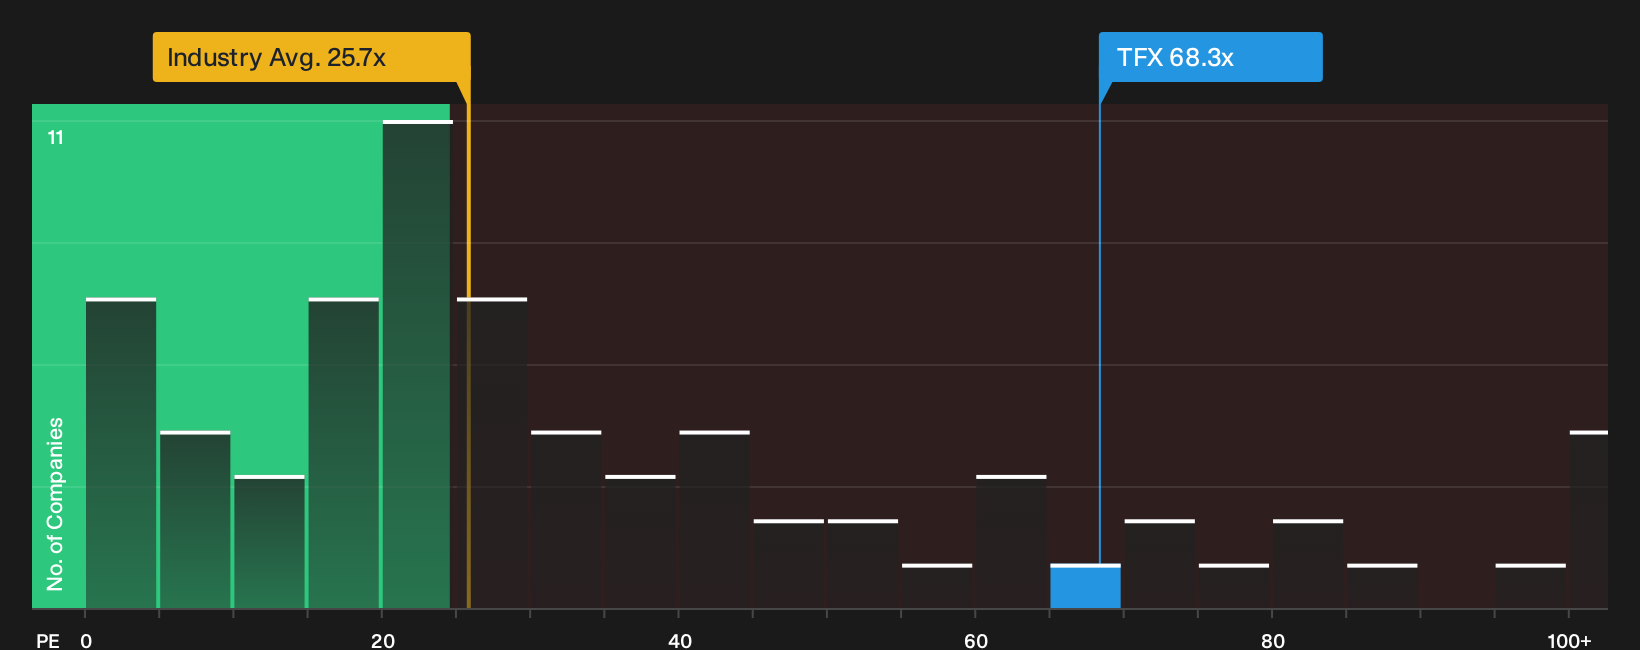
The story looks very different once Teleflex is viewed through its P/E ratio instead of the analyst fair value of $161.82. At a P/E of 68.3x, the stock trades well above the US Medical Equipment group at 25.7x and above the 52.8x fair ratio that our model suggests the market could move toward over time.
That gap points to clear valuation risk. For sentiment to stay here, investors would need to stay comfortable paying almost three times the industry multiple and meaningfully above the fair ratio, even though Teleflex only recently returned to profit and carries low current and forecast return on equity.
For a closer look at how this P/E premium stacks up against peers and the fair ratio, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Teleflex’s value story. That is exactly why you should check the data yourself, weigh both the upside and the red flags, and ground your next move in the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Teleflex?
If you stop at Teleflex, you risk missing other setups where quality, income, and lower risk line up in ways that might suit your portfolio better.
- Target resilient balance sheets and steady fundamentals by running your filters through the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by scanning the 40 high quality undervalued stocks before enthusiasm fully prices in the opportunity.
- Build a cash flow stream by focusing on income opportunities inside the 7 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com