


EN
Hanover Insurance Group (THG) Shares Moved, So What Is Behind The Latest Attention?
Q3 earnings and buyback activity put Hanover Insurance Group in focus
Hanover Insurance Group (THG) just paired its third quarter earnings release with an update on its ongoing share repurchase, giving investors fresh numbers on both business performance and capital returns.
Recent trading has reflected that mix of progress and questions. Hanover Insurance Group’s share price has gained strongly over the year, with a double digit year to date share price return of 35.65% and a 1 year total shareholder return of 36.5%. However, shorter term momentum has cooled slightly after a 1 day share price decline of 2.55% and a 7 day share price pullback of 2.21% following the Q3 update and confirmation of the buyback progress.
Scan how Hanover Insurance Group’s latest earnings and buyback compare with other insurers by checking a curated set of 31 resilient stocks with low risk scores in the sector.
After a 1 year total return of 36.5% and a share price almost level with analyst targets, the real question on Hanover Insurance Group is simple: Is meaningful upside still ahead, or has most of it already played out?
Most Popular Narrative: 2% Overvalued
Hanover Insurance Group closed at $242.90, slightly above the analyst consensus Narrative fair value of $238.25. This implies the stock already bakes in much of the expected execution on growth, profitability, and capital returns according to the analyst consensus Narrative on Simply Wall St.
Disciplined capital management, supported by an affirmed A financial strength rating, a long record of dividend growth, and a new US$700m share repurchase authorization expected to run for several years, is aligned with long-term targets for mid to high teens operating ROE and around 10% growth in operating EPS and book value. This can help sustain earnings per share and capital return metrics already reflected in the current valuation.
See why 8 investors see Hanover Insurance Group as 2% overvalued.
Result: Fair Value of $238.25 (OVERVALUED)
Still, Hanover Insurance Group’s narrative leans heavily on Specialty and Small Commercial growth targets, as well as on catastrophe losses staying within modeled ranges, both of which could be tested.
Find out about the key risks to this Hanover Insurance Group narrative.
Another View: Our DCF Model Flips The Script
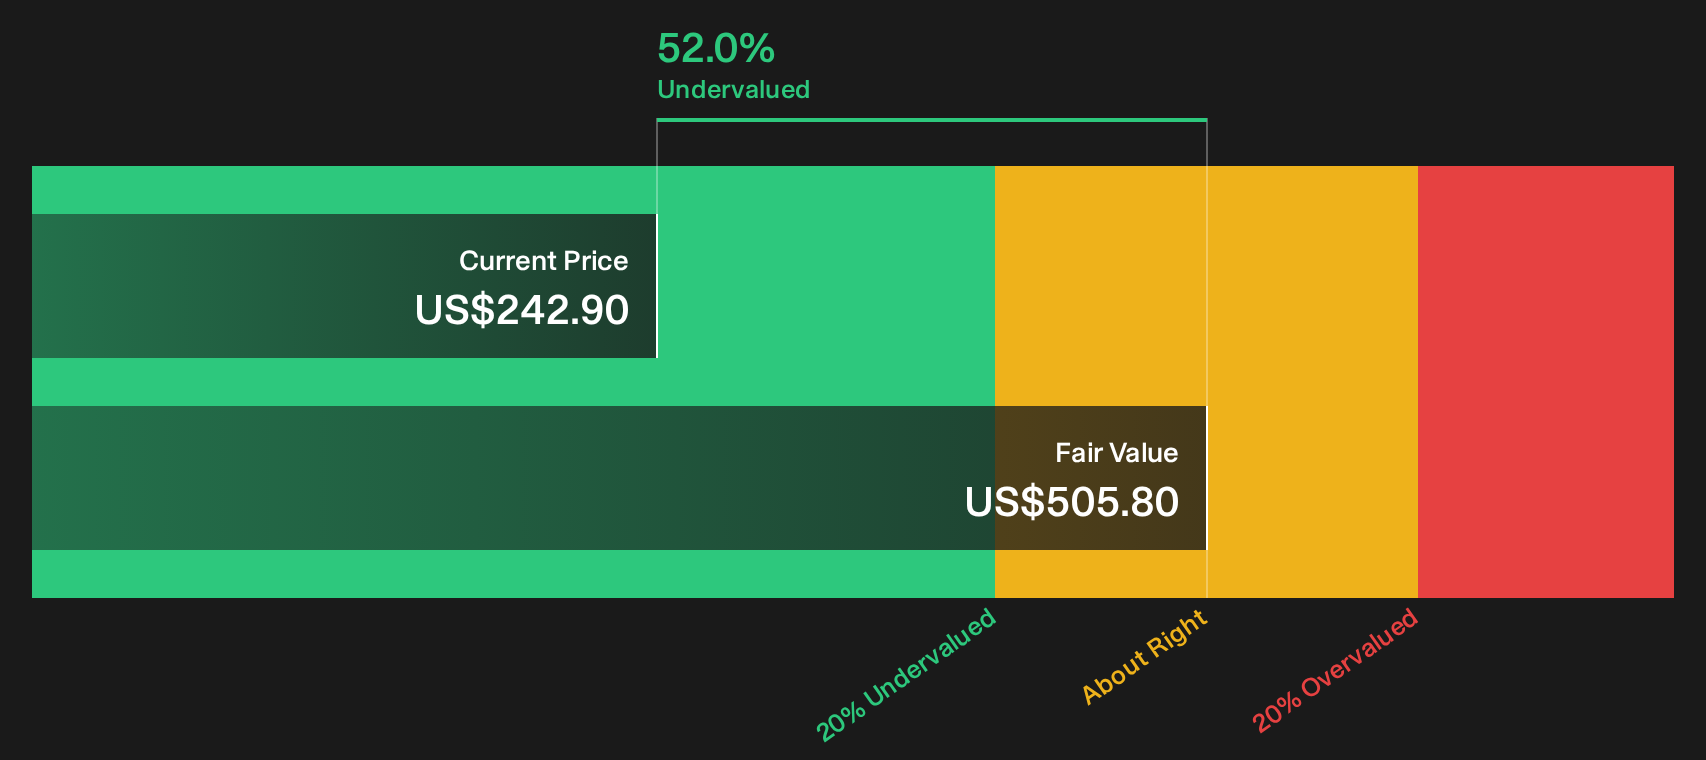
The analyst narrative tags Hanover Insurance Group as about 2% overvalued against a fair value of $238.25, yet the Simply Wall St DCF model points the other way. On that framework, THG at $242.90 trades around 52% below an estimated future cash flow value of $505.80, which frames the current price as far more conservative than the consensus target implies. Which lens do you trust more when the story on future cash generation and multiples pulls in opposite directions?
For a closer look at how this cash flow view is built step by step, it is worth unpacking the SWS DCF model in more detail, starting with Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Hanover Insurance Group for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Hanover Insurance Group can spark debate, so move quickly, review the underlying data and weigh both sides with 3 key rewards and 1 important warning sign
Looking for more Hanover Insurance Group style ideas?
If you stop with Hanover Insurance Group, you might miss companies that line up even better with your risk, income, or value goals, so keep hunting with the screeners below.
- Target resilient balance sheets and steady fundamentals by running your filters through a curated list of solid balance sheet and fundamentals (25 results) that keeps financial strength front and center.
- Hunt for strong businesses priced below their implied worth by scanning a focused 40 high quality undervalued stocks tailored for investors who care about quality and price discipline.
- Build an income focused watchlist by zeroing in on a select group of 7 dividend fortresses that aim to combine yield with staying power.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com