


EN
UFP Technologies (UFPT) Posted Robust Q3 Results, Is The Upside Already Priced In?
Fresh quarterly figures are in. UFP Technologies (UFPT) reported third quarter 2026 results on 3 November, giving investors an updated read on sales, profitability and earnings per share for the year to date.
The strong third quarter update follows a powerful run in the share price for UFP Technologies, with a year-to-date share price return of 35.84% and a 1-year total shareholder return of 29.39%. Recent trading has been more mixed, with the 7-day share price return of 6.87% and 30-day gain of 5.02% partly offset by a 90-day share price decline of 5.73%, indicating that short-term momentum has cooled even as the 3-year and 5-year total shareholder returns of 112.92% and 343.99% keep the longer-term picture positive at a latest share price of $303.47.
Extend your research beyond UFP Technologies and scan a curated set of resilient, financially solid businesses with our list of solid balance sheet and fundamentals (25 results) to see what else matches this quality profile.
The recent jump in UFP Technologies after its third quarter release puts a real timing question on the table. Is it worth paying up at around $303 now, or does it make more sense to wait for a better entry as the valuation settles?
Most Popular Narrative: 14.5% Undervalued
The analyst consensus Narrative on Simply Wall St pegs UFP Technologies at a fair value of $355, compared with a last close of $303.47. That gap anchors the current valuation debate and frames how investors might weigh MedTech exposure, acquisitions and execution risk.
The ongoing shift in UFP Technologies toward higher margin MedTech programs and away from slower non-medical segments such as automotive, combined with year-to-date 2026 MedTech sales growth of 11.7% for the top 5 customers, points to a mix change that could continue to support revenue and earnings.
See why 5 investors see UFP Technologies as 15% undervalued.
Result: Fair Value of $355 (UNDERVALUED)
Still, delays in shifting AJR production to the Dominican Republic, along with higher SG&A from back office and management spending, could pressure margins if growth underwhelms.
Find out about the key risks to this UFP Technologies narrative.
Another View: What UFP Technologies Looks Like On Earnings
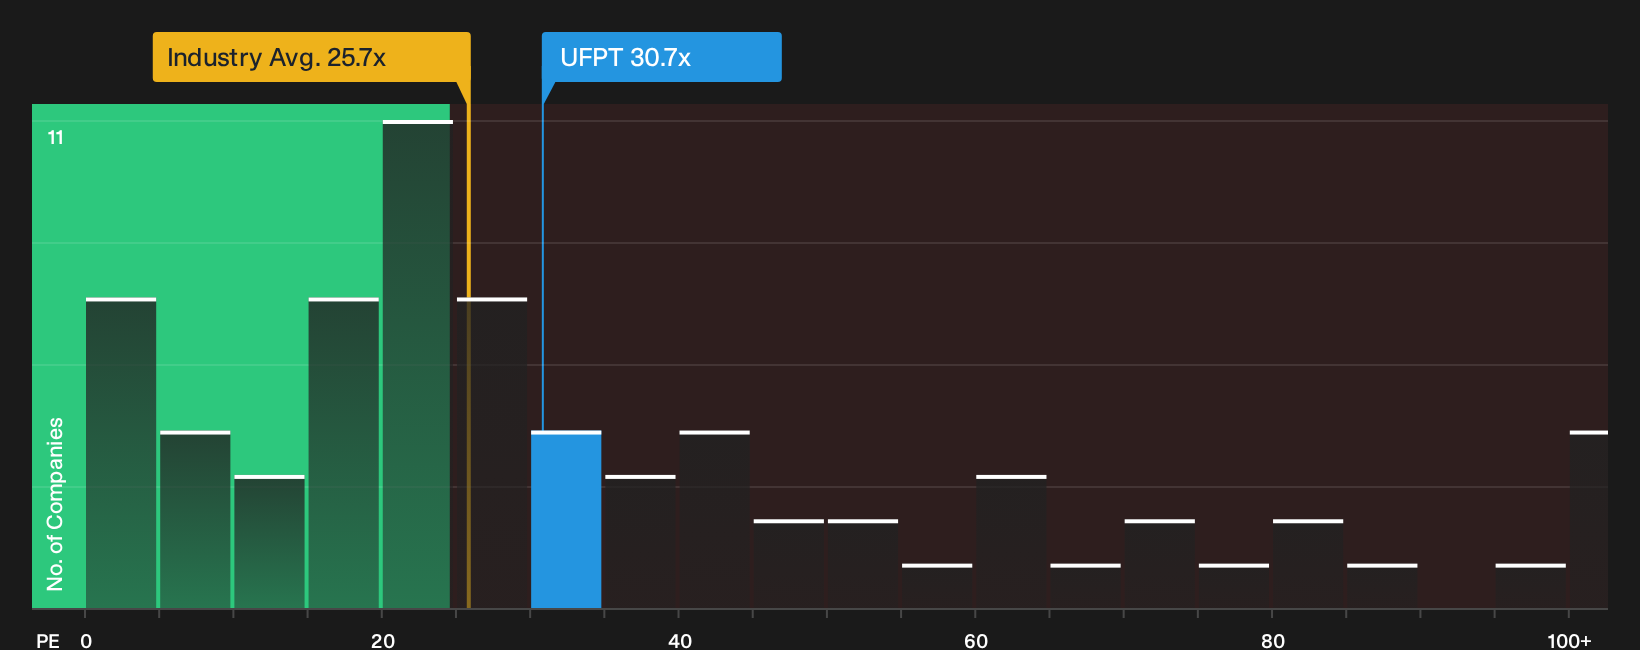
There is a very different message in the earnings multiple. UFP Technologies trades on a P/E of 30.7x, which is higher than the US Medical Equipment industry at 25.7x and above its own fair ratio of 26.1x. That richer tag leans toward valuation risk rather than a clear bargain and leaves the question of how much optimism is already priced in.
To see how this earnings based view stacks up against the broader valuation work, take a closer look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment around UFP Technologies is mixed, with both upside potential and real concerns in play, so move quickly and test the data against your own risk tolerance. To see how optimism and caution balance out, weigh the 2 key rewards and 1 important warning sign.
Looking for more UFP Technologies sized ideas?
If you stop with UFP Technologies, you risk missing other opportunities that fit your style and risk profile across quality, value and income.
- Target dependable balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results) that zeroes in on companies with financial resilience front and center.
- Hunt for potential value opportunities with pricing that may not fully reflect fundamentals by running the 40 high quality undervalued stocks and comparing what you find to UFP Technologies.
- Build a watchlist of income candidates by checking the 7 dividend fortresses that filters for higher yielding stocks with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com