


EN
What Unity Software Buyers Were Betting On
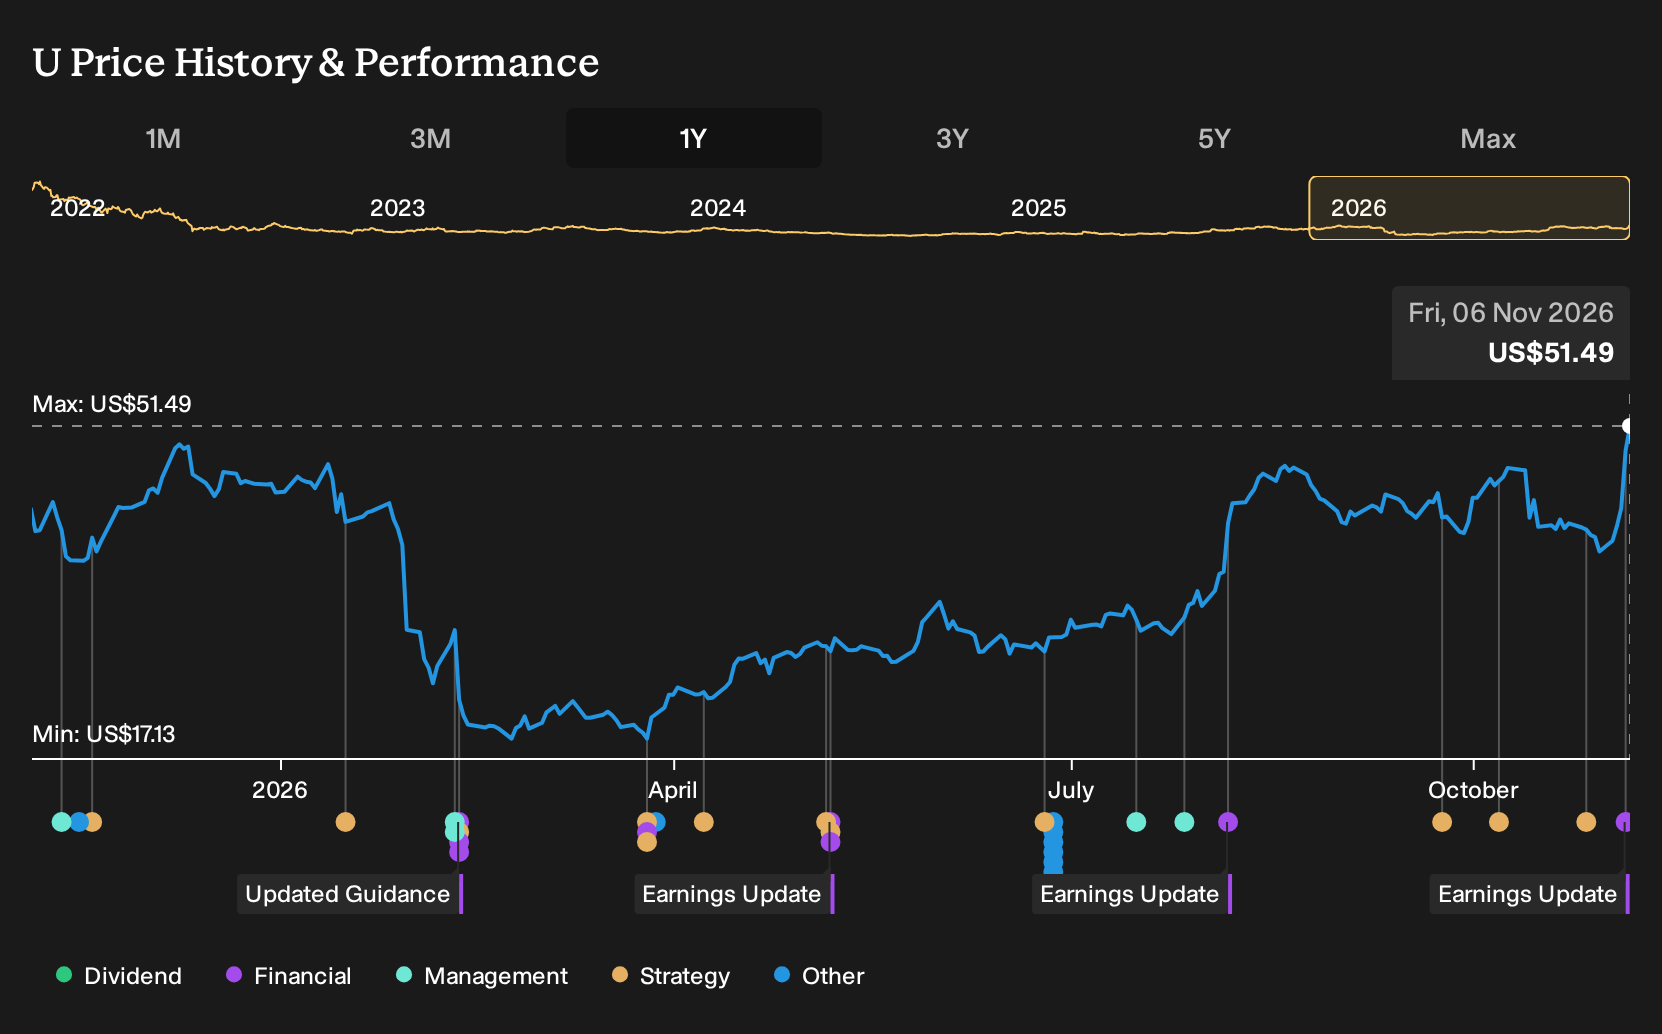
If you had focused only on Unity Software’s restructuring headlines and the shuttering of the ironSource Ads Network, it would have been easy to stay on the sidelines. Holding Unity Software over the past year would have returned 28.6%, including dividends. That outcome now raises a sharper question: If you were buying on 6 November 2025, before Q1 2026 beats and fresh AI deals, what exactly did you have to believe about this turnaround story?
This theme extends beyond Unity Software. See which of 40 AI small caps may still merit a closer look.
The Argument Unity Investors Were Really Weighing
The shares cost US$39.93 at the start of the period, which left Unity Software holders choosing between two very different futures for the same business.
The bullish story pointed to a Fair Value of US$44, a rough guide to what that scenario implied the stock could be worth if it played out, anchored on revenue growing 11.4% a year and profit margins eventually reaching 12.7%.
The more cautious view tied to a Fair Value of US$34.75 rested on slower 9.3% revenue growth and the risk that heavy AI and product spending kept profitability under pressure, even if margins later reached 12.9% and the shares traded on a 72.8x P/E.
What The Unity Software Results Put To The Test
The key development for Unity Software was the Q3 2026 report. Total revenue reached US$622.1 million, up from US$470.6 million a year earlier, and a US$126.4 million loss excluding extra items turned into a US$118.2 million profit. Net margin moved from a loss of 26.9% to a 19.0% gain. That combination supported the optimistic case more than the cautious one.
The lesson is about which claim to test first. When a turnaround pitch leans on margin repair, it can be useful to track net income and net margin side by side each quarter and see whether profitability actually arrives on the timetable the story implied.
What Unity Investors Are Being Asked To Believe Now
Unity Software now trades at US$51.49, above where it started the past year, and the bearish analyst Narrative on Simply Wall St places its own Fair Value below that level. The gap reflects a view that plenty of good news is already embedded in the quote.
The Narrative highlights AI advertising, creator tools and engine upgrades as real growth levers, yet also flags execution and cost pressure as live questions. To justify today’s price, a buyer would need confidence that Unity’s AI driven ad platforms can grow usage without letting cloud and R&D spending quietly erode long term margins.
"Unity Software's current numbers, including rapid growth in Vector, a higher-margin mix, and earlier GAAP profitability targets, imply a share price that already reflects successful execution on both the AI advertising flywheel and expanded creator monetization."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Which Company Could Surprise You Next?
The story behind this run has already been told. The next one could be taking shape somewhere else. Where could you start looking before it becomes the headline?
- Company 1 - 41% below our estimate - uses AI centric networking and data infrastructure to shift clients into recurring service models.
- Company 2 - 42% below our estimate - deploys cash recycling ATMs and branch-in-a-box setups that replace traditional teller footprints.
- Company 3 - 39% below our estimate - ramps higher density NAND nodes to push storage buyers toward premium enterprise drives.
That is three of the list. See every one of the 40 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com