


EN
Is Novavax (NVDA) Undervalued After A Smaller Loss And Sanofi Milestone?
Why Novavax stock is back in focus
Novavax (NVAX) moved back onto investor radar after third quarter results showed a much smaller net loss, alongside news of a US$125 million milestone payment tied to its Sanofi collaboration.
Recent trading reflects that shift in sentiment. The share price has climbed 51.2% year to date and the 1 year total shareholder return sits at 51.6%, yet the 5 year total shareholder return is still down 93.8%. This shows powerful short term momentum against a very weak long term record as investors reassess Novavax after the narrower loss and Sanofi milestone news.
Compare Novavax's renewed interest with other potential rebound stories by scanning our hand picked list of 19 high quality undiscovered gems featuring improving fundamentals and under the radar momentum.
Novavax now has a narrower loss and a fresh US$125 million milestone coming in, yet the share price already reflects a sharp rebound. Is this a stronger vaccine platform at a sensible valuation, or is the recent move running ahead of itself?
Most Popular Narrative: 25% Undervalued
On the analyst consensus Narrative on Simply Wall St, Novavax carries a fair value of $14.44 against a last close of $10.78, which frames the stock as materially discounted while still hinging on execution of its licensing model and cost reset.
The shift to a partner-led Matrix-M licensing model, with 4 of the top 10 global pharmaceutical companies now using licenses or MTAs across more than 30 infectious disease and oncology projects, supports the case that Novavax could grow higher margin royalty and milestone revenue over time.
What is behind 66 investors see Novavax as 25% undervalued.
Result: Fair Value of $14.44 (UNDERVALUED)
Still, the Novavax story can unwind quickly if partner milestones prove lumpy again or if cost cuts fail to offset uneven royalty-driven revenue.
Find out about the key risks to this Novavax narrative.
Another View: What Novavax’s Sales Multiple Is Telling You
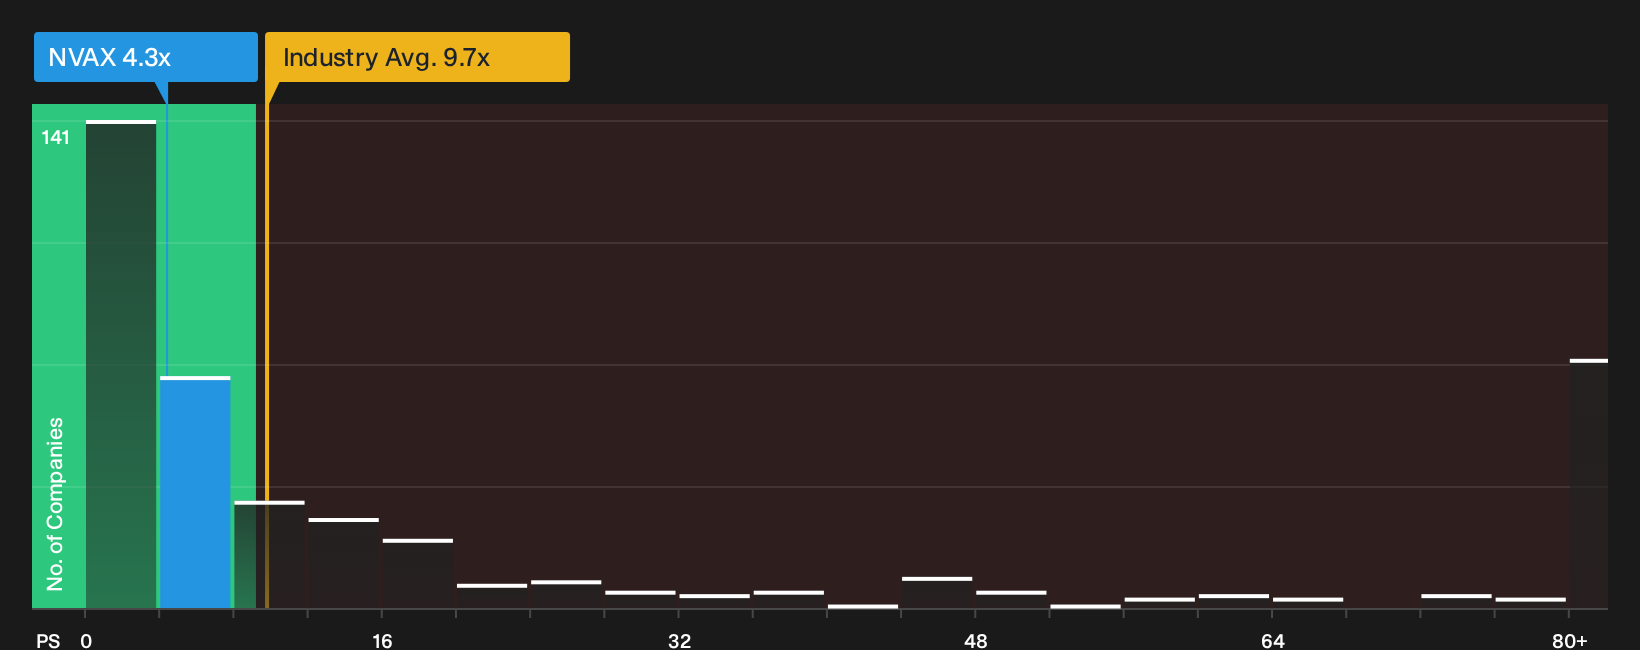
The DCF style fair value at $35.95 paints Novavax as heavily undervalued, around 70% below that future cash flow estimate. Yet the P/S ratio at 4.3x is well below peers on 36.9x, and the fair ratio of 1.5x suggests the market could compress that multiple further. Is this a margin story, or a valuation trap if revenue keeps shrinking?
For a closer look at how the current share price compares with sales based benchmarks and where that gap might close or widen, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Novavax story so far. Act while the data is fresh, examine the trade off yourself, and weigh the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Novavax?
Do not stop with Novavax. Use this momentum to refresh your watchlist, compare alternatives, and pressure test whether your capital is really in the best ideas.
- Target resilient balance sheets and steady fundamentals by scanning a list of solid balance sheet and fundamentals (25 results) that can help anchor your portfolio when sentiment swings.
- Hunt for quality at a discount with a focused sweep of 40 high quality undervalued stocks that pair strong business drivers with share prices that lag their fundamentals.
- Prioritise consistency and capital protection by reviewing a curated group of 31 resilient stocks with low risk scores designed to limit unpleasant surprises when conditions change.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com