


EN
Is First Quarter Earnings Strength Altering The Investment Case For Cardinal Health Stock (CAH)?
- Cardinal Health reported first quarter 2027 results for the period ended September 30, 2026, with sales of US$67,513 million, net income of US$554 million, and diluted EPS from continuing operations of US$2.38 compared with US$1.88 a year earlier.
- The year over year increase in earnings per share indicates higher profitability in the period, which gives investors more evidence to assess how Cardinal Health’s mix of distribution and service based businesses is translating into bottom line performance.
- This context helps frame how Cardinal Health's investment narrative may be influenced by its first quarter net income and EPS performance.
Cardinal Health Investment Narrative Recap
To own Cardinal Health, you need to believe the large pharmaceutical and medical distribution engine can keep supporting higher margin services like specialty pharma, Biopharma Solutions and at Home chronic care. The analyst consensus Narrative on Simply Wall St leans on that mix shift. The latest quarter’s higher EPS gives some comfort that the engine is still working, but does not fully change the core thesis.
In the short term, the key catalyst remains execution in those higher value segments while keeping product quality issues and recalls contained. The biggest current risk is that any further quality or regulatory setbacks, together with high debt costs or inflation in oil linked inputs for GMPD, chip away at margins and investor confidence.
The first quarter 2027 report, with US$67,513 million in sales and US$554 million in net income, is the most relevant update for that thesis. Solid profitability in this period helps support the idea that a higher mix of services and specialty activity can coexist with Cardinal Health’s large distribution base, even as one off items still affect reported figures.
For catalysts, investors are watching whether segments like Biopharma Solutions, Nuclear and Precision Health and at Home Solutions keep expanding their contribution to earnings, as outlined in the analyst consensus Narrative on Simply Wall St. Any sign that product quality issues, insider selling concerns or GMPD cost pressures start to offset those gains would weaken confidence that current earnings power can be maintained over time.
Cardinal Health's narrative projects US$301.7b revenue and US$3.1b earnings by 2029. This assumes 5.4% yearly revenue growth and an earnings increase of about US$1.3b from current earnings of US$1.8b.
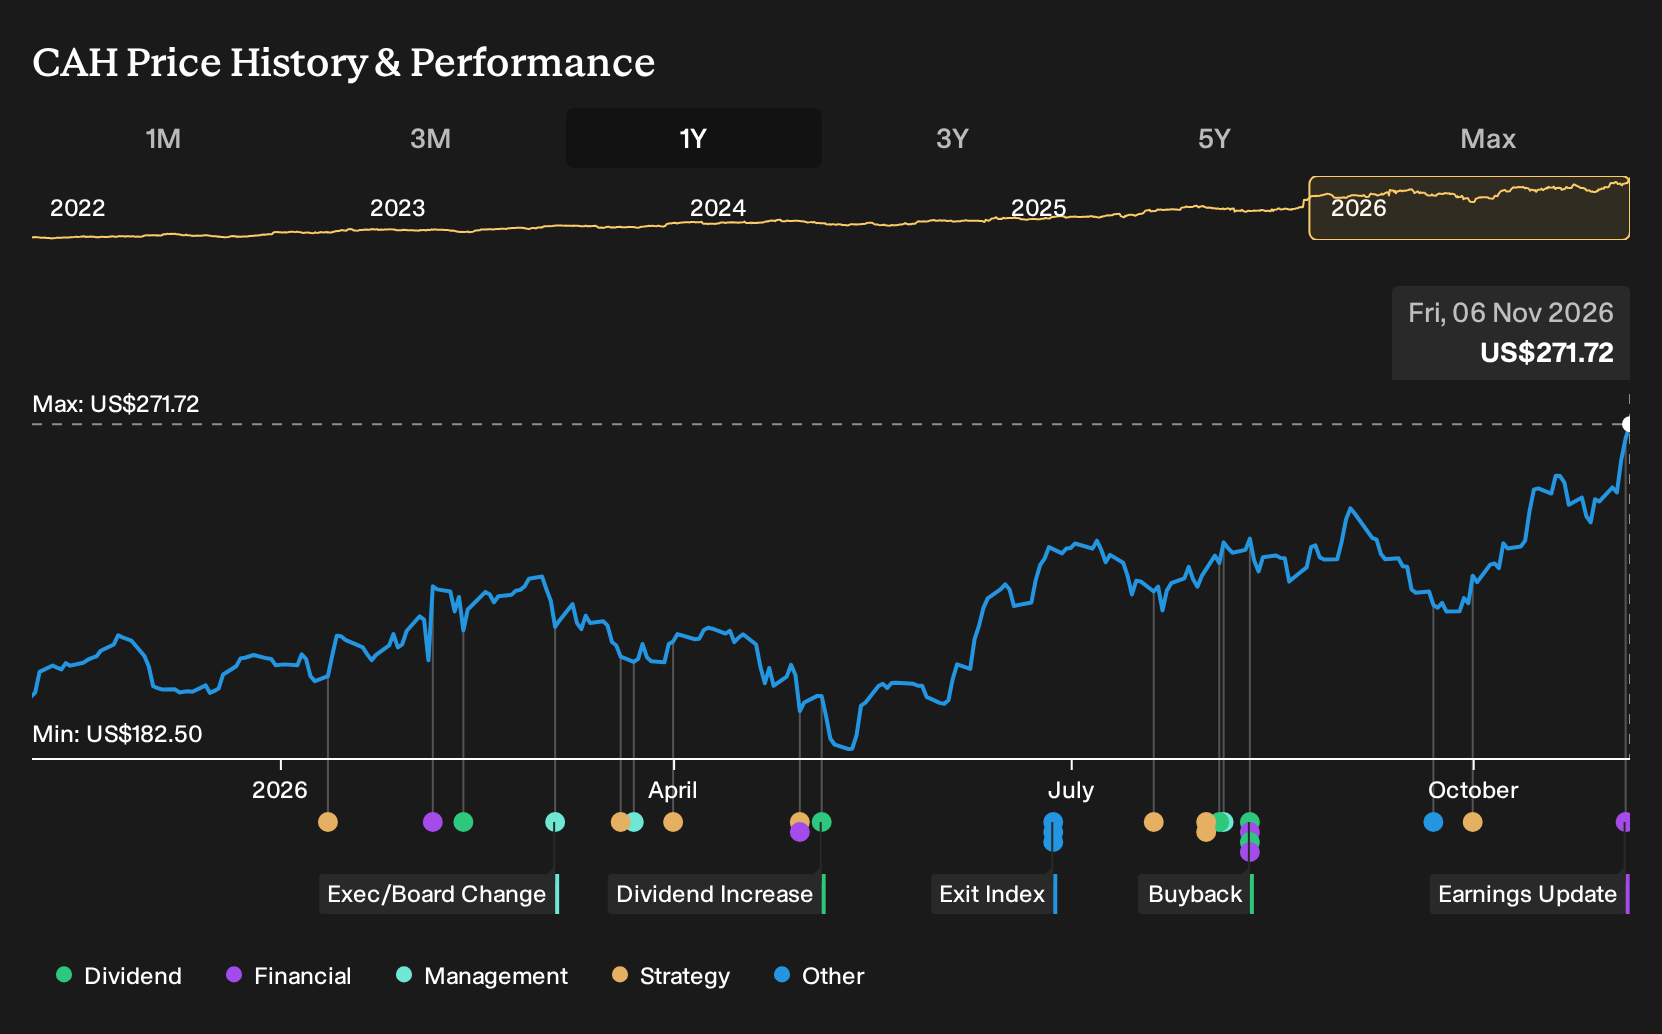
Uncover how Cardinal Health's fair value indicates a 7% potential upside to its current price that could narrow quickly if sentiment around Cardinal Health continues to improve.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community span roughly US$292 to about US$600 a share, so you are seeing a wide gap in how retail investors model Cardinal Health. When you set that against quality concerns from levothyroxine recalls and insider selling, it serves as a reminder that opinions can diverge sharply and invites you to compare several viewpoints before committing fresh capital.
Explore 2 other Cardinal Health fair value estimates, including one that suggests it could be worth just $291.53.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Cardinal Health research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Cardinal Health. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cardinal Health's overall financial health at a glance.
Looking for more investment ideas beyond Cardinal Health?
Once you have formed a view on Cardinal Health, it can help to compare it with other opportunities that offer different combinations of quality, risk and income potential. The Simply Wall St Screener is built for exactly that kind of side by side homework.
- If you want dependable balance sheets and sturdier fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that helps you focus on financial resilience first.
- If steadier income appeals to you, shortlist potential income plays using a curated set of 7 dividend fortresses that bring together yield and fundamental checks.
- If you are hunting for underappreciated stories, scan through a curated 19 high quality undiscovered gems where the financials may already support more attention than the market is giving.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com