


EN
Is Abbott Laboratories (ABT) Fairly Valued After Its FDA Win And Oncodetect Launch?
Abbott Laboratories (ABT) just picked up a unique FDA approval for its Amplatzer Paraclose PVL Occluder and rolled out its next-generation Oncodetect MRD test, expanding its presence in complex heart procedures and cancer monitoring.
Recent headlines in cardiology and cancer diagnostics have arrived against a mixed share price backdrop for Abbott Laboratories, with the stock at US$109.93 after a 10.37% 1 month share price return but a decline of 11.48% for the year to date. Over the last year investors have seen the share price fall enough for total shareholder return to decline 10.51%, yet a 22.23% total shareholder return over three years points to earlier gains that contrast with the weaker recent momentum. Short term moves, including a 3.23% drop on the day, suggest investors are still weighing new product approvals, clinical data and device recall headlines against the longer record of compounding returns.
Scan how Abbott Laboratories stacks up against other complex-care players by reviewing the hand-picked 35 healthcare AI stocks riding advances in cardiology, diagnostics and data-driven medicine.
Abbott Laboratories now trades about 7% below the average analyst target and at a steeper implied discount to some fair value estimates. After the recent slide, is that caution fully earned, or is it overly harsh on the new product momentum?
Most Popular Narrative: 9% Undervalued
On the Simply Wall St analyst consensus Narrative, Abbott Laboratories carries a fair value estimate of $120.26 compared with the last close at $109.93. That view ties the gap to future earnings power rather than recent share price volatility.
The main thing that has to go right is that Abbott Laboratories continues to convert its medical technology pipeline in areas like continuous glucose monitoring, electrophysiology and cancer diagnostics into sustained sales growth and margin expansion, while managing Nutrition legal and regulatory risks.
See why 198 investors see Abbott Laboratories as 9% undervalued.
Result: Fair Value of $120.26 (UNDERVALUED)
Still, Abbott Laboratories faces real pressure points, with ongoing Nutrition legal settlements and higher Libre expansion costs, both capable of squeezing the margin story that the narrative leans on.
Find out about the key risks to this Abbott Laboratories narrative.
Another View on Abbott Laboratories Valuation
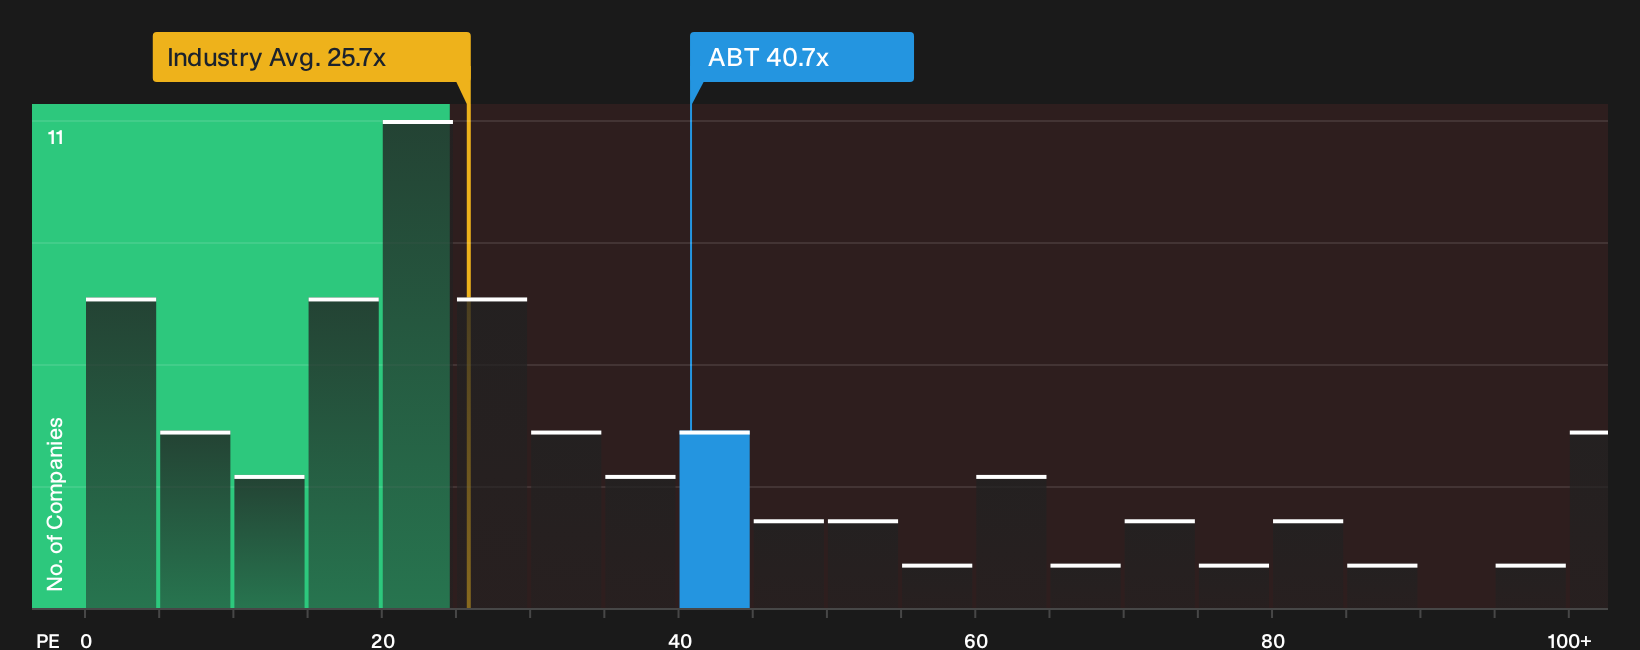
Multiples tell a different story for Abbott Laboratories. The stock trades on a P/E of 40.7x, which is higher than both the US Medical Equipment industry at 25.7x and its peer average at 38x, and only slightly above the fair ratio of 40.1x that the market could move toward. That points to less obvious upside and more pressure on execution to justify the current tag. How comfortable are you with paying this kind of premium for Abbott Laboratories today?
To see how that premium lines up against the underlying numbers and risks, take a closer look at the valuation breakdown, including the fair ratio context, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Abbott Laboratories can feel messy, so review both the upside and the concerns promptly and then decide what stacks up for you with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Abbott Laboratories?
Do not stop with Abbott Laboratories. Put this analysis in context by lining it up against other opportunities that match your goals and risk comfort.
- Target resilient opportunities by scanning a 31 resilient stocks with low risk scores that aims to prioritize balance sheet strength and steadier return profiles over headline excitement.
- Hunt for value by lining up companies in a 40 high quality undervalued stocks that focuses on strong fundamentals at prices that may not fully reflect them.
- Spot under-the-radar potential through a 19 high quality undiscovered gems that highlights quality businesses investors are not widely talking about yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com