


EN
Wall Street Sees More Than $100 for Uber. The Stock Is Under $70
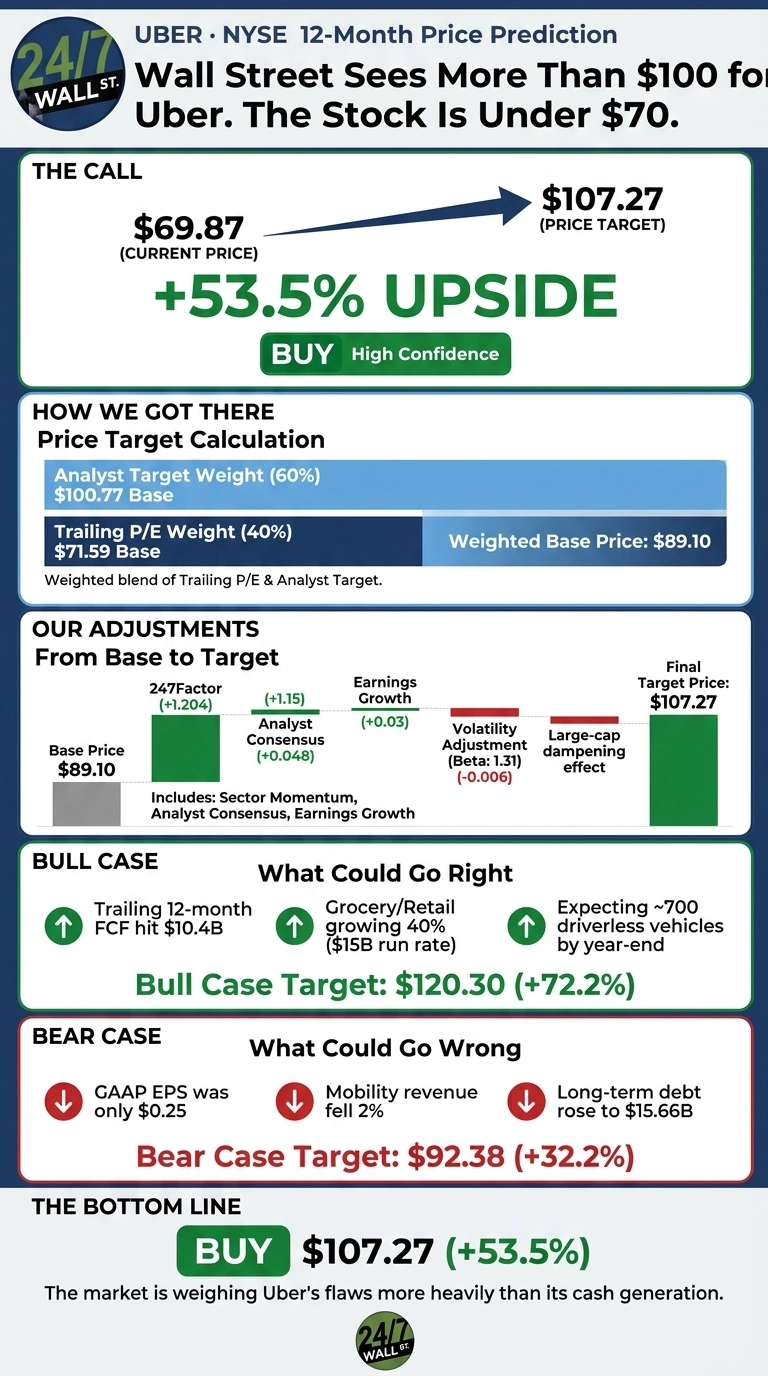
Uber Technologies (NYSE:UBER) closed at $69.87 on November 4. Wall Street’s consensus target is $100.77, about 44.2% above that close. The 24/7 Wall St. price target is $107.27 over the next 12 months, which means 53.5% upside.
 24/7 Wall St.
 Price Target Summary Metric Value Current Price $69.87 Price Target from 24/7 Wall St. $107.27 Upside/Downside 53.5% Model Rating BUY Confidence Level 70%
Uber earns a buy rating from the model with fairly high confidence. The analyst community leans the same way, with 9 Strong Buy and 32 Buy ratings against 8 Holds and 1 Sell.
The gap between price and target comes down to whether investors keep marking Uber down for weak reported revenue while bookings keep growing at 20% or more.
A Revenue Beat and an EPS Miss Set Up a ReboundShares rose 4.91% on earnings day and gained 7.05% over the week. Over a longer period, Uber is down 14.49% year to date and sits 26.6% below its 52-week high of $95.18, just 9.1% off its $64.04 low.
Third-quarter revenue reached $14.77B, up 9.7% and ahead of the $14.67B consensus. Non-GAAP EPS of $0.88 fell short of the $0.90 estimate. Gross Bookings rose 20% to $59.8B, and changes to the business model cut reported revenue growth by 8 percentage points. The CEO told CNBC that Uber is “investing significantly” to add drivers.
Why Bulls See $120 AheadThe bull case reaches $120.30, or 72.2% upside. Q4 guidance calls for non-GAAP EPS of $0.95 to $0.99, which would be growth of 34% to 39%. Trailing 12-month free cash flow hit a record $10.4B and paid for $4.28B of buybacks in the first nine months.
Grocery and retail now run at a $15B annual rate and are growing 40%. Uber also expects about 700 driverless vehicles on its network by year-end. As management put it, “We still are running into supply constraints rather than demand constraints.”
What Could Keep Uber Pinned Below $70The bear case comes to at $92.38, still 32.2% above the current price. The risks are real, though. GAAP EPS was only $0.25, reported Mobility revenue fell 2%, and Freight is still losing money. Long-term debt rose to $15.66B from $10.52B. A $484M legal reserve points to exposure on how drivers are classified as workers.
GAAP results took a $476M loss from revaluing equity stakes, and Mobility segment operating income still rose 27%.
Uber Trades Cheaper Than DoorDash and Richer Than LyftDoorDash (NASDAQ:DASH) competes head-on with Uber Eats. Shares trade at 88x trailing earnings after Q3 revenue grew 33.95%, a figure raised by the Deliveroo acquisition. Next to that, Uber’s multiple makes our target look conservative.
Lyft (NASDAQ:LYFT) is Uber’s direct U.S. ride-hail rival, and its Gross Bookings grew 23% in Q2. Its P/E is distorted by a $2.90B tax benefit, so price to free cash flow gives a cleaner comparison. Uber’s premium on that measure looks earned, given its profits across several business lines.
Company Trailing P/E Price/FCF Uber 14 14.6 DoorDash 88 37.6 Lyft 2 6.4 Uber’s Discount Looks OverdoneMy 24/7 Wall St. price target for Uber is $107.27, with a buy model rating and 70% confidence. Cash flow is the deciding factor: $10.4B in trailing free cash flow at a 14 P/E.
I’d grow more constructive if driver supply keeps improving and Q4 EPS lands within guidance. I’d turn cautious if bookings growth slips below 18% or legal reserves keep climbing. Below $70, the market is weighing Uber’s flaws more heavily than its cash generation.
Year Price Target from 24/7 Wall St. 2026 $74.46 2027 $105.39 2028 $140.42 2029 $174.53 2030 $192.73Uber needs to keep executing on its current strategy for these projections to hold. Large swings up or down could come from how fast autonomous vehicles scale or from rulings on driver classification.