


EN
How Raised Earnings Guidance Will Impact OGE Energy Stock Investors
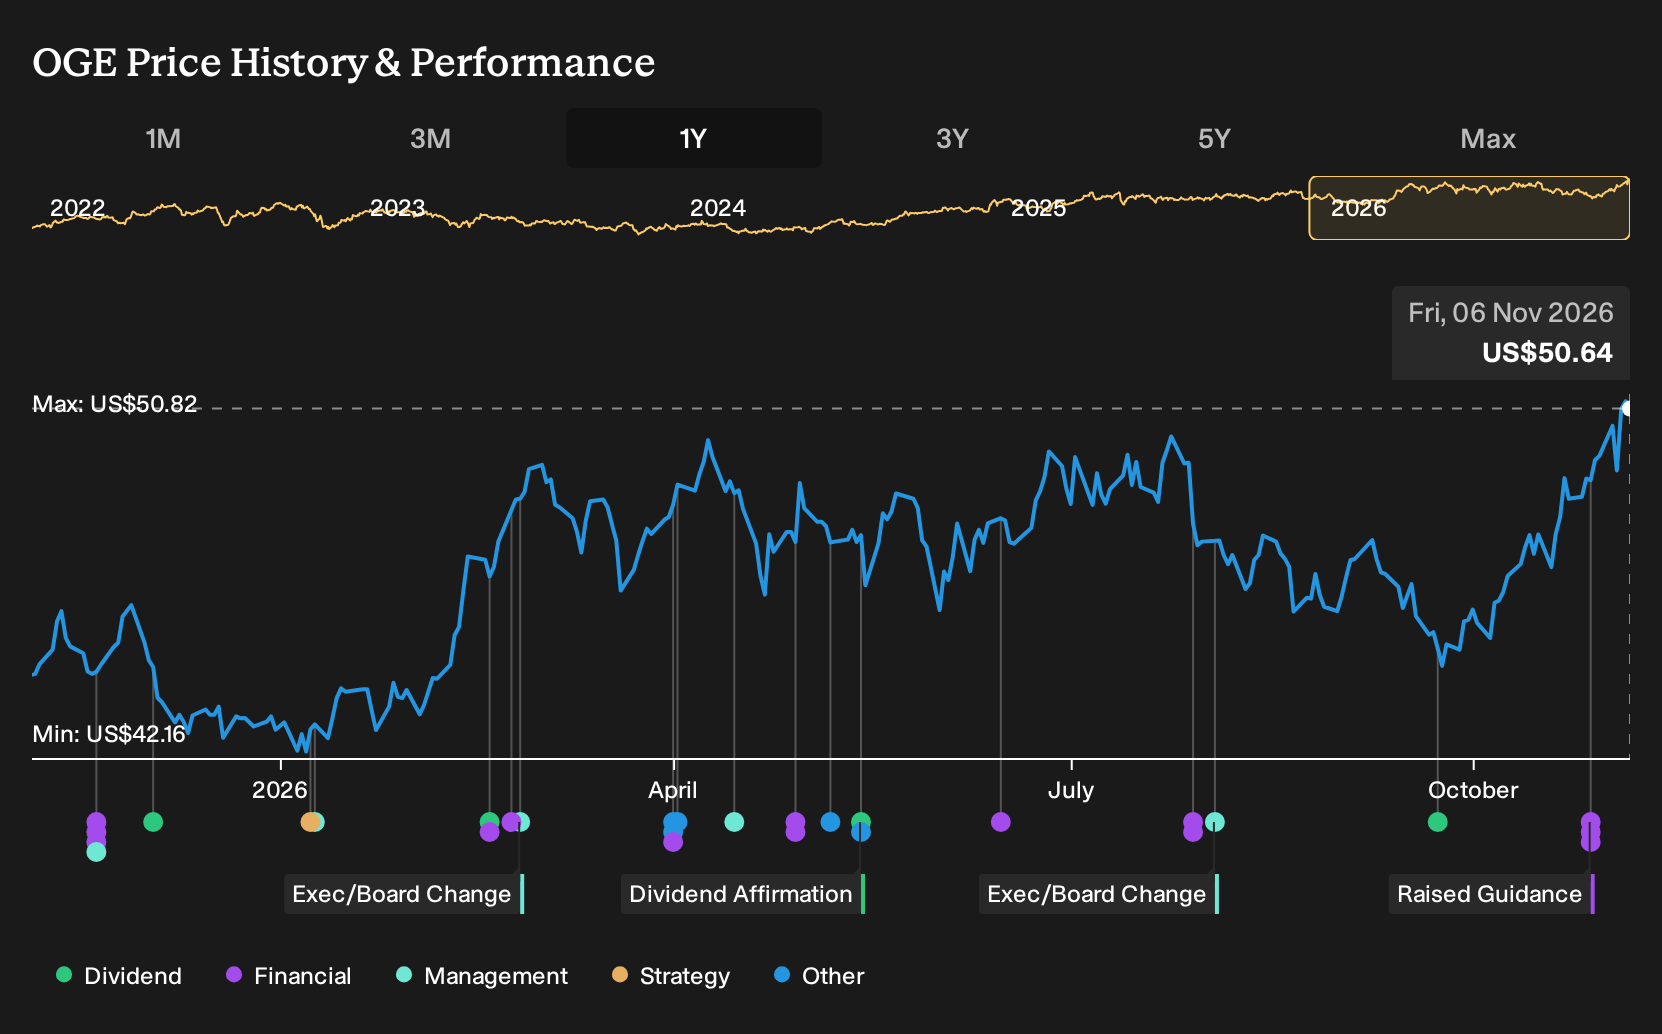
- OGE Energy raised its 2026 consolidated earnings guidance to US$2.62 to US$2.68 per average diluted share after warmer than normal weather, while third quarter 2026 results showed higher sales, revenue and net income compared with the prior year period.
- The follow-on US$750 million at-the-market equity offering gives OGE Energy additional capacity to fund its capital program, while nine-month 2026 earnings from continuing operations per share remained above the prior year level.
- We will look at how OGE Energy's raised full-year earnings guidance reshapes the existing investment narrative around large-scale load growth.
Scan how OGE Energy's weather driven earnings update compares with utilities and other income names by jumping into our curated list of 7 dividend fortresses
OGE Energy Investment Narrative Recap
For an investor to stay with OGE Energy, the core belief is that large load demand, especially from data centers, justifies the planned US$7.3b 2026 to 2030 investment program described in the analyst consensus Narrative on Simply Wall St. The raised 2026 earnings guidance, helped by warmer weather, supports that demand story but does not change the need for consistent execution on new capacity.
The immediate upside catalyst still sits in converting the current pipeline of large load negotiations into contracted usage while keeping regulators comfortable with bill impacts. The biggest risk remains pressure on capital recovery and returns, especially after prior disputes around natural gas units and with a high debt load already flagged for investors.
The at the market US$750m follow on equity offering is tightly linked to this guidance update. Management now has more flexibility to fund the multiyear build out of generation and transmission assets that underpin the higher earnings power analysts are modeling, while trying to keep the balance sheet aligned with its target FFO to debt ratio of about 17%.
For you as a shareholder, that equity program cuts both ways. It supports the capital plan that drives future rate base, yet repeated share issuance could dilute earnings per share if industrial and oilfield load stays soft or if new large customers ramp more slowly than expected. Execution on data center contracts and regulatory approvals will largely decide which side of that trade off dominates.
OGE Energy's current earnings of US$551.9 million are projected by analysts to reach US$642.7 million by 2029. This implies an earnings increase of about US$90.8 million, alongside forecast revenue of US$4.0b in that same year, built on an assumed 5.7% yearly revenue growth rate.
Uncover why OGE Energy's fair value aligns with its current price.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community span from about US$36 to more than US$101,000 per share, which shows how far private investors can spread on OGE Energy. Those views were set before the raised 2026 earnings guidance and equity issuance, so you can weigh weather driven upside against funding, regulatory and large load execution risks.
Explore 2 other OGE Energy fair value estimates, including one that suggests as much as 200326% upside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your OGE Energy research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for OGE Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate OGE Energy's overall financial health at a glance.
Looking for more investment ideas beyond OGE Energy?
Once you have a view on OGE Energy, it can help to line it up against other potential opportunities using the Simply Wall St Screener.
- If capital preservation matters most to you, check out a curated group of stocks with steadier profiles through the 31 resilient stocks with low risk scores.
- For investors who want quality at a reasonable price, compare OGE Energy with other potential value opportunities using the 40 high quality undervalued stocks.
- If you are hunting for companies with strong finances that may be flying under the radar, broaden your watchlist with the 19 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com