


EN
How M And S Store Rollout Will Impact Vusion Stock Investors
- Marks & Spencer reported that it has deployed Vusion's Bluetooth-based Connected Store and EdgeSense smart rail platform to additional UK stores, targeting more efficient product information management, faster product location for staff and a digital base for future in-store upgrades.
- The Marks & Spencer rollout shows a large retailer leaning on Vusion to hardwire store infrastructure into a connected platform, which can be important for future software, data and value-added services adoption across the same footprint.
- We will examine how Vusion's investment narrative is influenced by Marks & Spencer's broader Connected Store rollout commitment and its wider digitalization initiatives.
Scan how Vusion’s Connected Store rollout compares to other retail tech plays by reviewing a hand-picked list of 91 robotics and automation stocks shaping in-store automation and efficiency.
Vusion Investment Narrative Recap
For a shareholder in Vusion, you need to believe the business can turn its Connected Store and IoT footprint into durable software and data revenue while managing a slower revenue forecast of 3.6% per year and earnings that are projected to decline by 12% per year. According to basicFit26, an investor in the Simply Wall St Community, the key question is whether the platform effect from hundreds of millions of devices can keep the model attractive.
The Marks & Spencer rollout marginally supports that platform view, because it shows a large retailer building more store processes on Vusion infrastructure. The more pressing near term issue remains execution risk, especially on large deployments and the shift toward higher margin software. Any delay in converting new sites into higher value services would keep profitability under pressure.
This M&S news sits closest to what basicFit26 calls the next generation smart store opportunity, where Vusion combines IoT, computer vision and data analytics to lift revenue per store. The Connected Store and EdgeSense rails are effectively that smart store concept in live deployment, with flashing labels and location aware tools embedded in day to day operations.
For catalysts, M&S adds evidence that retailers are willing to standardize store infrastructure on Vusion. This matters for future software, VAS and retail media monetization on the same rails. The risk side does not change much. Large rollouts still need to be executed cleanly, and the transition toward recurring SaaS income still has to show through in the income statement to offset forecast earnings pressure.
In that narrative, basicFit26 reaches a fair value of €229.19 per Vusion share by pairing projected revenue growth of 25.0% a year with a future profit margin of 9.7%, and then applying valuation multiples that align with other higher growth, higher margin, technology-driven platforms.
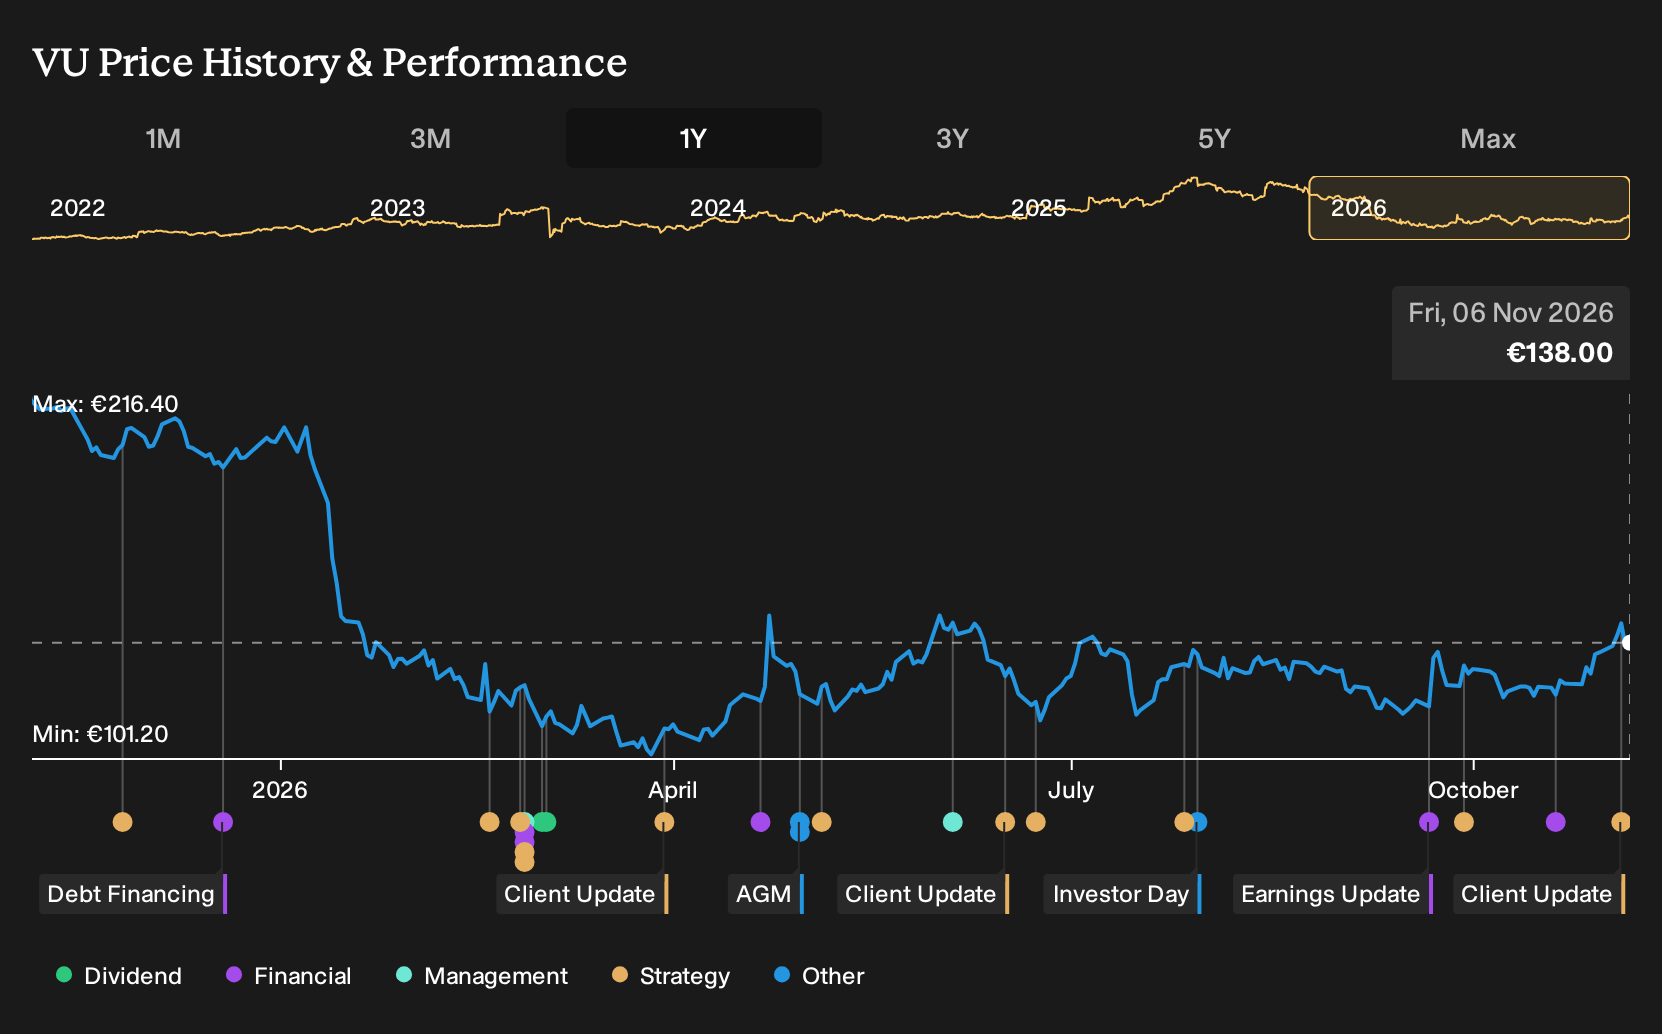
Uncover how Vusion's fair value indicates a 66% potential upside to its current price that may not be sustained for long.
Exploring Other Perspectives
One contrasting angle focuses on what happens after current projects mature. The most pessimistic analysts were assuming Vusion’s revenue would grow only 1.1% a year and that earnings could fall from €284.9 million to €143.8 million. Those forecasts pre date the Marks & Spencer rollout, so you can watch how views may adjust from here.
Explore 3 other Vusion fair value estimates, including one that suggests it could be worth just €208.57!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Vusion research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Vusion. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Vusion's overall financial health at a glance.
Looking For More Investment Ideas Beyond Vusion?
If the Vusion story has sharpened your thinking on retail tech and recurring revenue, it can help to line it up against other potential opportunities using the Simply Wall St Screener. That way you can compare different balance sheet profiles, income streams and risk levels before deciding where to focus next.
- If capital preservation sits high on your priority list, scan a 207 resilient stocks with low risk scores that may offer steadier profiles than more volatile growth plays.
- For readers hunting for quality at a reasonable price, filter the market with a 222 high quality undervalued stocks that blends stronger fundamentals with more modest expectations.
- When income is a key goal, check out a 226 dividend fortresses that concentrates on established payouts with higher stated yields.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com