


EN
Nippon Electric Glass (TSE:5214) Ends Its Buyback, Is The Stock Still A Bargain?
Nippon Electric Glass (TSE:5214) has just wrapped up a sizeable share repurchase, completing a buyback program alongside fresh nine month earnings and updated full year guidance that give investors new data to assess the stock.
At a share price of ¥4,615, Nippon Electric Glass has seen its 7 day share price return fall 12.61% and its year to date share price return decline 25.80%. However, the 3 year total shareholder return of 70.60% and 5 year total shareholder return of 103.99% point to a much stronger longer term story.
Scan beyond Nippon Electric Glass and see how it stacks up against 24 high quality undervalued stocks with solid cash flows and balance sheets that could appeal to long term investors.
Nippon Electric Glass has just retired nearly 5% of its equity following a period of weaker share price performance and softer earnings. Does that shift the risk reward toward buyers, or does it keep caution in charge?
Preferred P/E of 14.8x: Is it justified?
Nippon Electric Glass trades on a P/E of 14.8x, and that earnings multiple sits below the peer average but above the broader Japanese electronic industry, which sends a mixed signal at ¥4,615.
The P/E ratio compares what investors are paying today for each unit of current earnings, so it helps you judge whether expectations built into Nippon Electric Glass are rich or restrained relative to its profit base.
Analysts mark the stock as good value against peers on this measure, with its 14.8x P/E below a peer average of 18x. Yet the same multiple screens as expensive versus the JP Electronic industry average of 13.2x, which suggests the market is pricing in better earnings quality or resilience than the typical sector player and could still re-rate closer to an estimated fair P/E of 16.8x if that view holds.
Explore the SWS fair ratio for Nippon Electric Glass.
Result: Price-to-earnings of 14.8x (ABOUT RIGHT)
Still, softer recent share price performance and a single glass focused revenue stream leave Nippon Electric Glass exposed if end demand or pricing weakens further.
Find out about the key risks to this Nippon Electric Glass narrative.
Another view on Nippon Electric Glass using cash flows
Price hints at one story, cash flows hint at another. Nippon Electric Glass trades at ¥4,615, while the SWS DCF model points to a future cash flow value of ¥4,974.85, which marks the stock at about 7.2% below that estimate. Is the gap a margin of safety or a value trap in disguise?
Look into how the SWS DCF model arrives at its fair value.
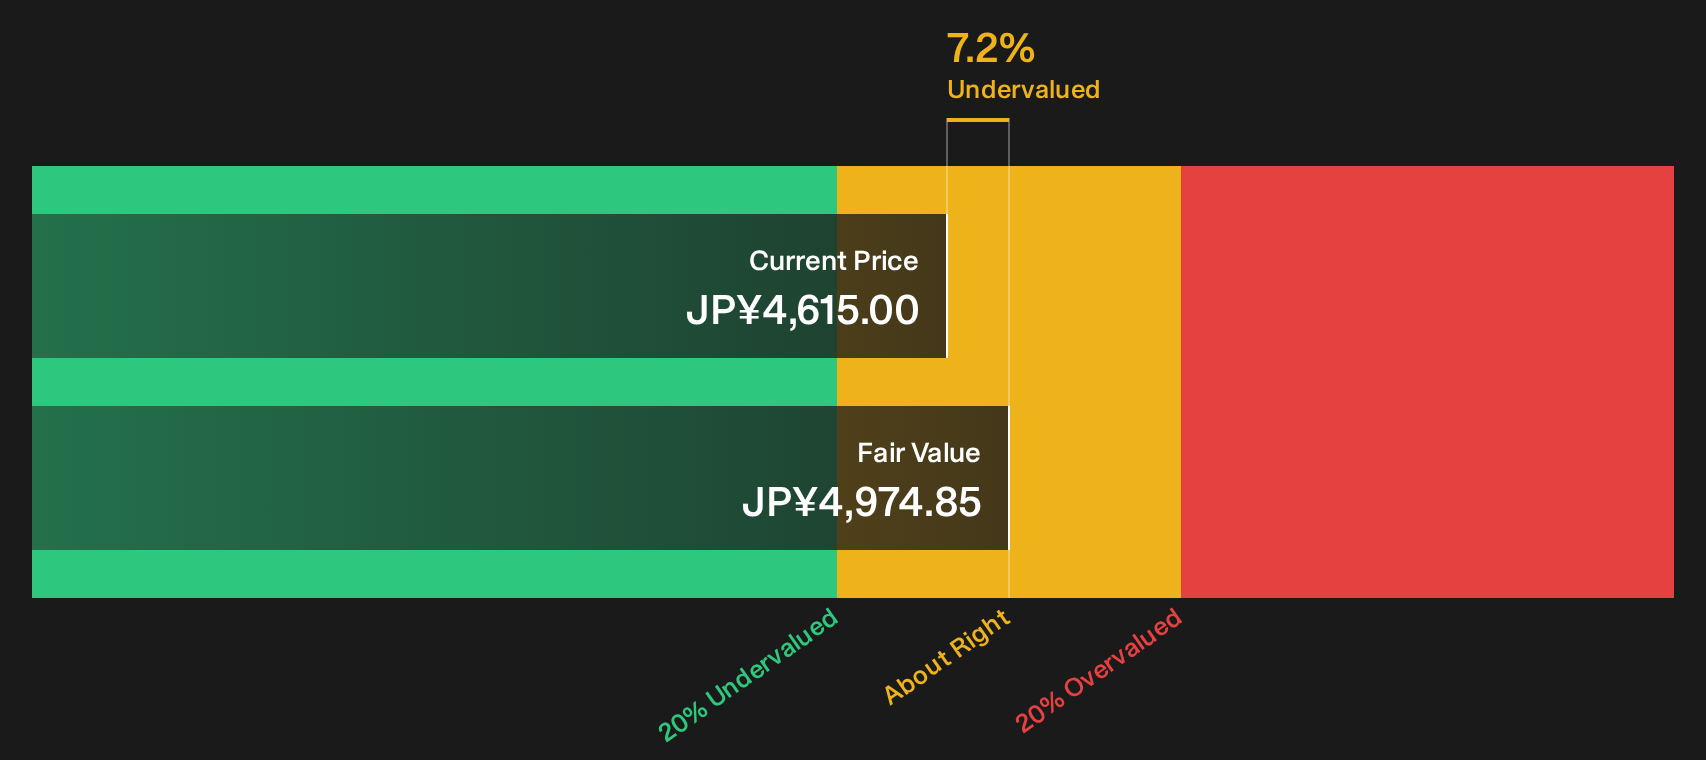
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Nippon Electric Glass for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 24 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Nippon Electric Glass often lead to strong views on both risk and upside potential, so it can be useful to move quickly and test the numbers yourself. To weigh those cross currents in one place, start with the balance of 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Nippon Electric Glass?
If Nippon Electric Glass has sharpened your focus on valuation and quality, do not stop here. Fresh ideas often come from comparing it with very different opportunities.
- Target resilient potential by scanning a curated group of companies with robust risk profiles through the 20 resilient stocks with low risk scores.
- Zero in on dependable income by reviewing a focused set of businesses offering strong payout profiles via the 35 dividend fortresses.
- Hunt for future leaders early by combing through a carefully filtered pool of under-the-radar opportunities using the 76 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com