


EN
How Investors Are Reacting To IAG Shares As Drivers Skip Safety Tech
- Insurance Australia Group research shows that many drivers with advanced driver assistance systems do not use them regularly, with only 57% doing so. This is prompting insurers such as Zurich Australia to start explicitly pricing features like Tesla's Full Self Driving into motor premiums.
- The finding that safety technology adoption lags the hardware installed in cars raises practical questions for Insurance Australia Group about real world risk, pricing accuracy and how technology driven underwriting models reflect actual driver behaviour.
- We will look at how Insurance Australia Group's investment narrative intersects with insurers rethinking risk as many drivers disable ADAS features.
Scan how other insurers and motor related businesses are being priced for technology risk by zeroing in on 6 resilient stocks with low risk scores that aim to balance premium stability with controlled downside.
Insurance Australia Group Investment Narrative Recap
To own Insurance Australia Group, you need to be comfortable with a general insurance business that leans heavily on retail scale, technology driven efficiency and reinsurance to hold its margins. The analyst consensus narrative on Simply Wall St hinges on management containing pricing competition, claims volatility and tech execution risk so that a 15% reported insurance margin ambition remains realistic.
Right now, the biggest swing factor is whether customer growth and retention hold up as premiums remain under scrutiny and affordability stays front of mind. The ADAS usage research does not materially change that near term catalyst, but it does highlight how important real world driving behaviour has become for pricing, loss ratios and the risk of mispriced motor books.
Recent commentary around the contested RAC Insurance acquisition in Western Australia is closely linked to these catalysts. That deal sits alongside the already completed RACQ Insurance acquisition, which brought in A$1.3b of premium in ten months, as a key plank in Insurance Australia Group’s plan to improve scale, spread fixed costs and extract reinsurance and technology benefits.
For an investor, the RAC transaction process matters because it goes to both growth and execution risk. If the WA transaction proceeds on acceptable terms, it can reinforce the thesis of larger personal lines scale, together with tech and AI investment of about A$400m in FY27, which analysts see as important ingredients for keeping reported insurance margins in the 14% to 16% range over time.
Insurance Australia Group’s current analyst narrative points to A$12.0b of forecast revenue and A$1.2b of forecast earnings by 2029. This is based on expectations of a 14.5% yearly revenue decline and an earnings increase of about A$200m from A$1.0b today.
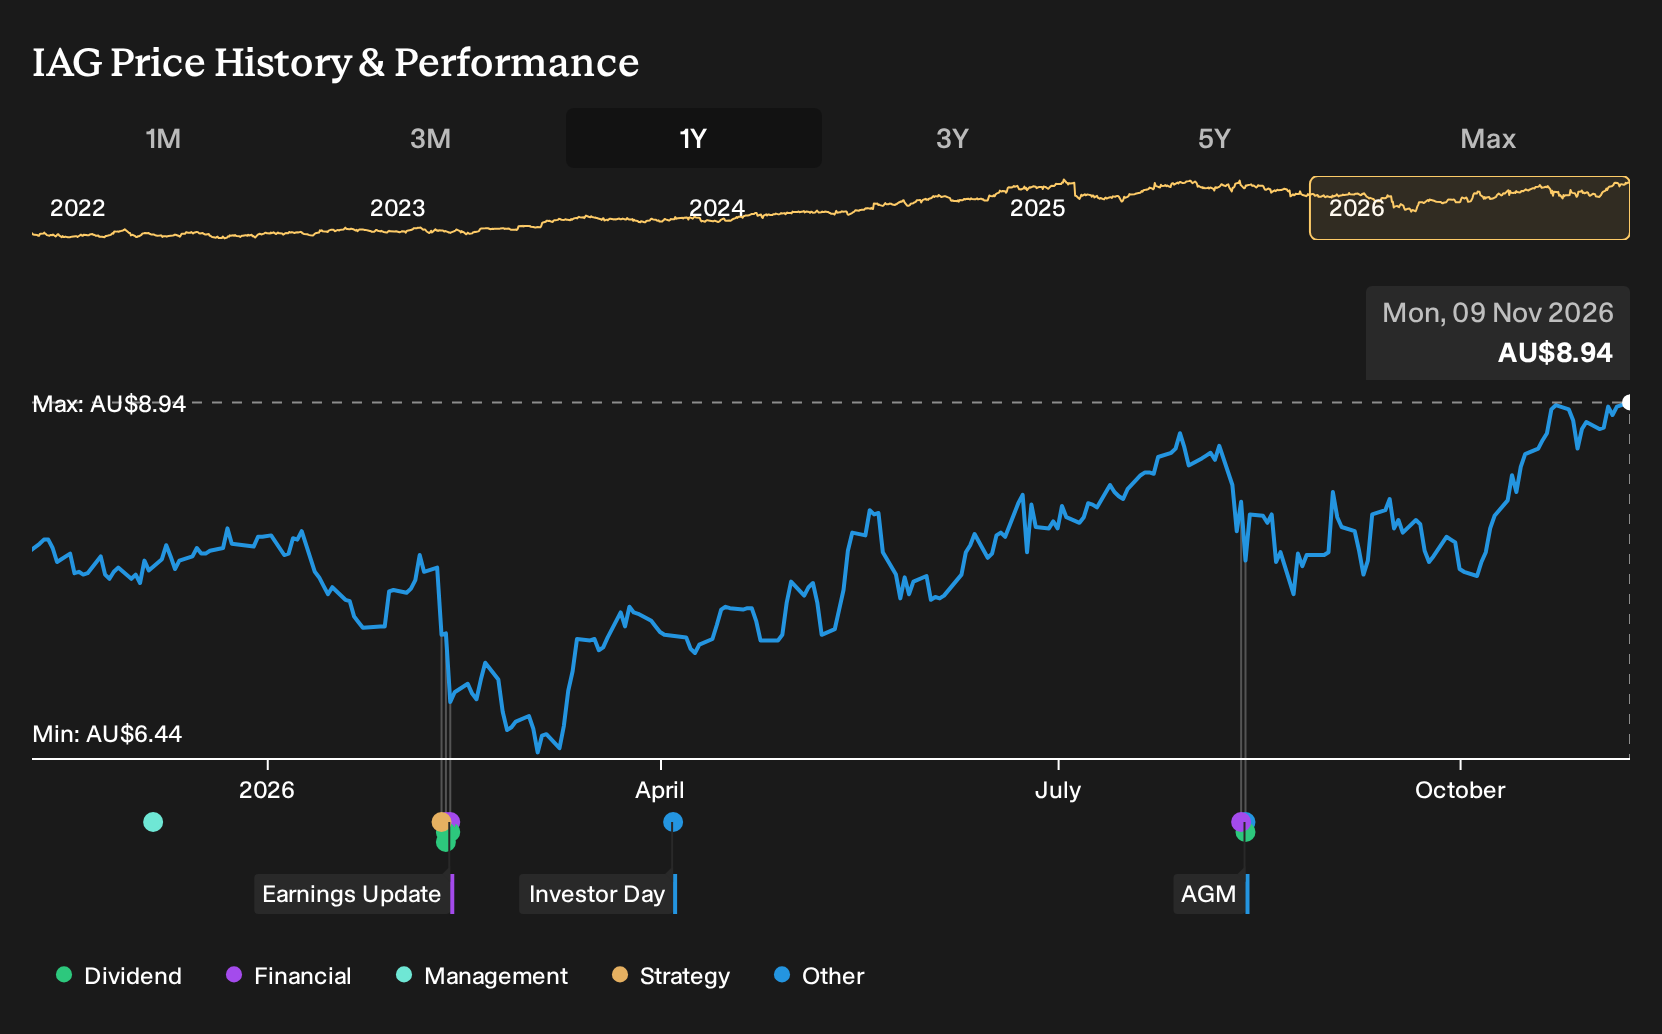
Uncover why Insurance Australia Group's fair value indicates a 7% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
The Simply Wall St Community offers only two fair value views for Insurance Australia Group, with estimates between A$8.30 and about A$10.66, so you are seeing a tight yet varied band rather than a single anchor. When this is set against ADAS usage uncertainty and contested RAC Insurance approvals, it becomes clear you should compare several viewpoints before deciding your stance.
Explore another Insurance Australia Group fair value estimate, including one that suggests as much as 19% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Insurance Australia Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Insurance Australia Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Insurance Australia Group's overall financial health at a glance.
Looking for more investment ideas beyond Insurance Australia Group?
Once you have formed a view on Insurance Australia Group, it can help to benchmark that thinking against other opportunities that match your risk tolerance and income needs. The Simply Wall St Screener lets you scan the market quickly using focused filters, so you can spend time on decisions rather than trawling through raw data.
- If capital preservation is your priority, start with companies that score well on resilience by reviewing a 6 resilient stocks with low risk scores that aim to keep downside in check.
- For investors who care most about quality at a reasonable price, compare Insurance Australia Group with a 3 high quality undervalued stocks that pair strong fundamentals with more modest expectations.
- If income is central to your plan, line up Insurance Australia Group alongside a 5 dividend fortresses designed for investors who want higher yields backed by sturdier balance sheets.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com