


EN
Paladin Energy (ASX:PDN) Just Gave Investors Something To Think About
Paladin Energy (ASX:PDN) has reported first quarter earnings to 30 September 2026, with sales of US$92.38 million and net income of US$4.29 million, replacing a loss a year earlier.
Despite Paladin Energy swinging to a quarterly profit, the share price has fallen 11.08% over the past month and 28.13% over the past three months, while the 1 year total shareholder return is down 3.99%. This suggests that shorter term momentum has weakened even as the longer term drag has been less severe.
Scan beyond Paladin Energy and compare its latest earnings shift with a hand-picked set of uranium and nuclear-linked infrastructure plays using the 17 nuclear energy infrastructure stocks in one place.
Paladin Energy has turned profitable while the share price has retreated sharply. The gap between sentiment, analyst targets and intrinsic estimates now matters most. Where does fair value sit within that range?
Most Popular Narrative: 19.4% Undervalued
Against the last close of A$7.46, the most followed narrative on Paladin Energy pegs fair value at A$9.25, which points to a sizeable gap between price and perceived worth according to that framework. That view comes from Miner2025, an investor in the Simply Wall St Community who set out a detailed argument around mine performance, Canada optionality and project timing.
Paladin (ASX/TSX: PDN) operates the Langer Heinrich uranium mine in Namibia (75% owned) and is advancing the Patterson Lake South (PLS) project in Saskatchewan. The September 2026 quarter was weak on production and strong on price, and the story keeps tilting toward PLS.
See why 1 investors see Paladin Energy as 19% undervalued.
Result: Fair Value of A$9.25 (UNDERVALUED)
Still, the Paladin Energy thesis leans heavily on production targets weighted to the second half and on a long-dated PLS build-out that could slip or strain funding.
Find out about the key risks to this Paladin Energy narrative.
Another View: Cash Flow Model Flips The Paladin Energy Story
A second lens on Paladin Energy comes from the SWS DCF model, which puts fair value at A$0.68 against the current A$7.46 share price. That points to the stock trading well above this cash flow based estimate. If that framework is closer to reality, how comfortable are you paying this kind of premium?
For anyone who wants to see how that cash flow estimate is built line by line, Look into how the SWS DCF model arrives at its fair value.
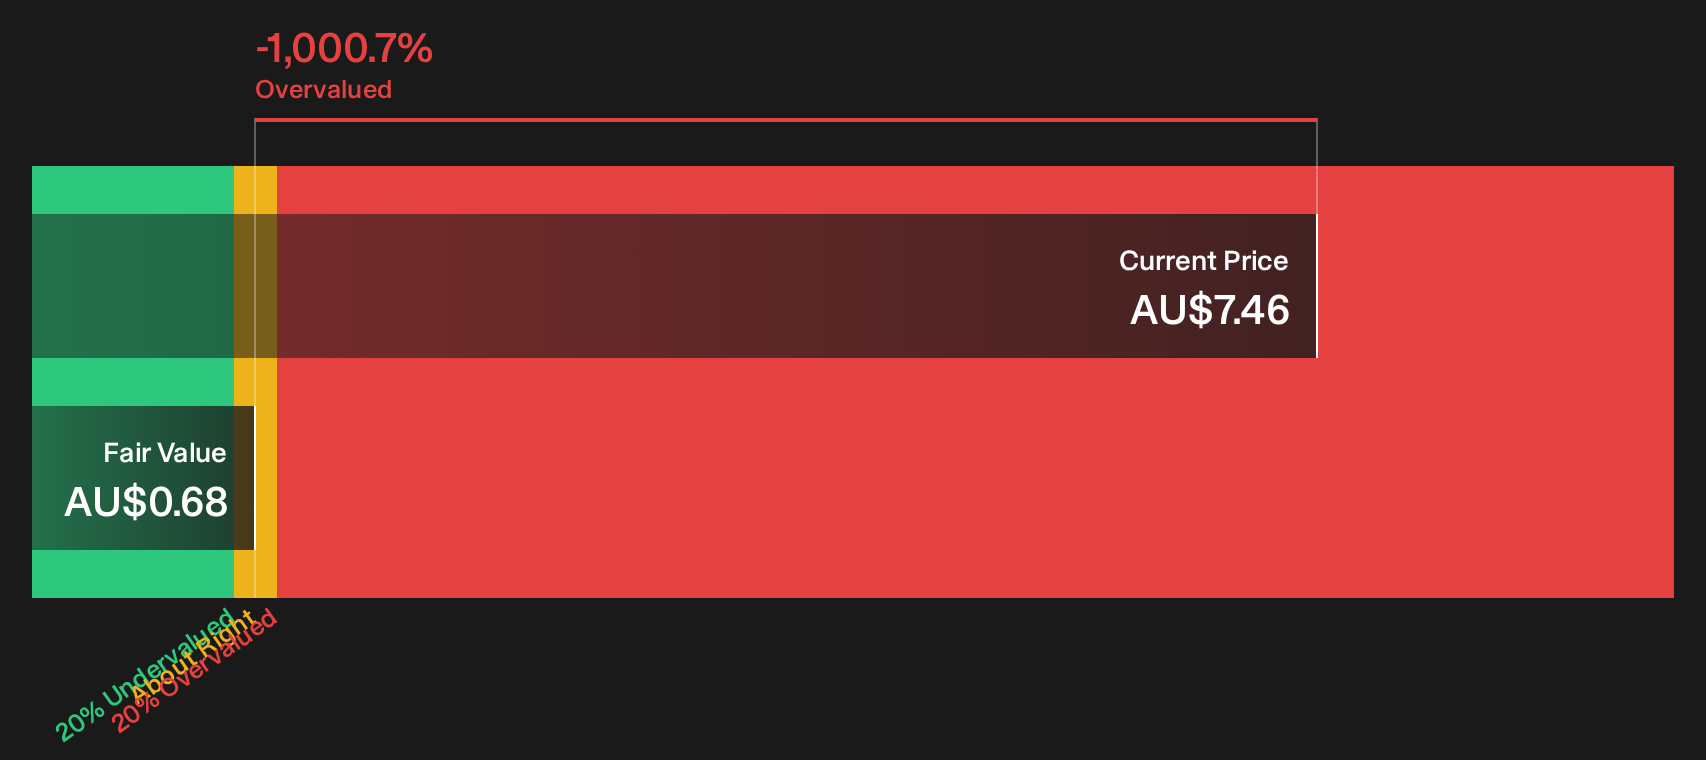
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Paladin Energy for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 3 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Paladin Energy is clearly split, with bulls pointing to upside and bears focused on stretched valuation and execution risks. Act quickly and interrogate the data for yourself by weighing up the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Paladin Energy?
If Paladin Energy has sharpened your focus on risk and reward, you may wish to widen your opportunity set with data driven ideas that highlight different strengths and trade offs.
- Target quality at a discount by scanning companies flagged as potential bargains through the 3 high quality undervalued stocks.
- Prioritise resilience by searching for businesses with stronger finances using the list of solid balance sheet and fundamentals (12 results).
- Hunt for overlooked opportunities before the crowd catches on with the 14 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com