


EN
ICON (ICLR) Stock Could Be Undervalued On Cash Flow Views
ICON plc has climbed over the past year while continuing to lean heavily on its ability to turn contracts into cash. The question now is whether the current share price reflects the cash flows the business is expected to generate.
- ICON has returned 29.8% over the past 12 months, which puts real pressure on the cash flow outlook to justify that kind of share price gain.
- Recent results highlighted strong free cash flow and an expanded share repurchase plan, which can support the view that ICON's future cash generation is central to how investors are valuing the stock today.
- What if you looked at ICON through its earnings instead? See why ICON's 35.4x P/E tells a different valuation story.
The stock's next move may depend on whether ICON's current price is in line with the cash flows implied by its intrinsic value estimate under the Discounted Cash Flow (DCF) approach.
If you are weighing ICON against other opportunities that trade on their cash generation, it can help to line it up next to 40 high quality undervalued stocks.
Is ICON a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) approach here focuses squarely on ICON's ability to keep turning contracted work into cash. Latest twelve month free cash flow sits at about $972.4 million, and the 2 Stage Free Cash Flow to Equity model assumes that this stream continues to grow from hundreds of millions into well over $1b a year over the coming decade.
Those projections, when discounted back using the DCF model, put ICON's estimated intrinsic value meaningfully above the current share price of $204.74. Because management has recently delivered strong Q3 2026 results and expanded the share buyback authorization, the market is already rewarding the stock. However, the implied value from forecast cash generation still runs ahead of where the shares trade today. Find out what ICON could be worth using our Discounted Cash Flow (DCF) estimate.
The ICON Narrative: What Would Justify Today's Price?
Narratives for ICON pick up directly from that valuation question and spell out which paths for revenue, margins and earnings would need to play out for the shares to look meaningfully under or over priced relative to today. Each one treats ICON's implied worth as a hypothesis about how the business could develop over time, so you can see how that idea holds up as new information arrives on Simply Wall St's Community page.
Bulls and bears looking at ICON reach very different conclusions about how much the current contracts and margin profile are worth.
Bull case: 9% undervalued
According to the analyst consensus Narrative on Simply Wall St, ICON’s upside hinges on how it turns bookings and AI tools into better earnings quality.
"The main factor that has to go right is that ICON converts strong net book-to-bill momentum and new AI and lab investments into healthier direct fee growth and a gradual rebuild of adjusted EBITDA margins…"
Discover why this Narrative puts ICON at 9% undervalued.
Bear case: 22% overvalued
The bearish analyst Narrative on Simply Wall St argues that ICON already prices in a lot, while margin reset and control issues still hang over the story.
"ICON’s own disclosure of improper revenue adjustments, errors in cost to complete estimates, material weaknesses in internal controls, and the roughly US$3.9b backlog adjustment create ongoing execution and governance risk that future reported revenue and earnings could again deviate from expectations…"
Explore why this Narrative puts ICON at 22% overvalued.
One more angle on ICON that could matter
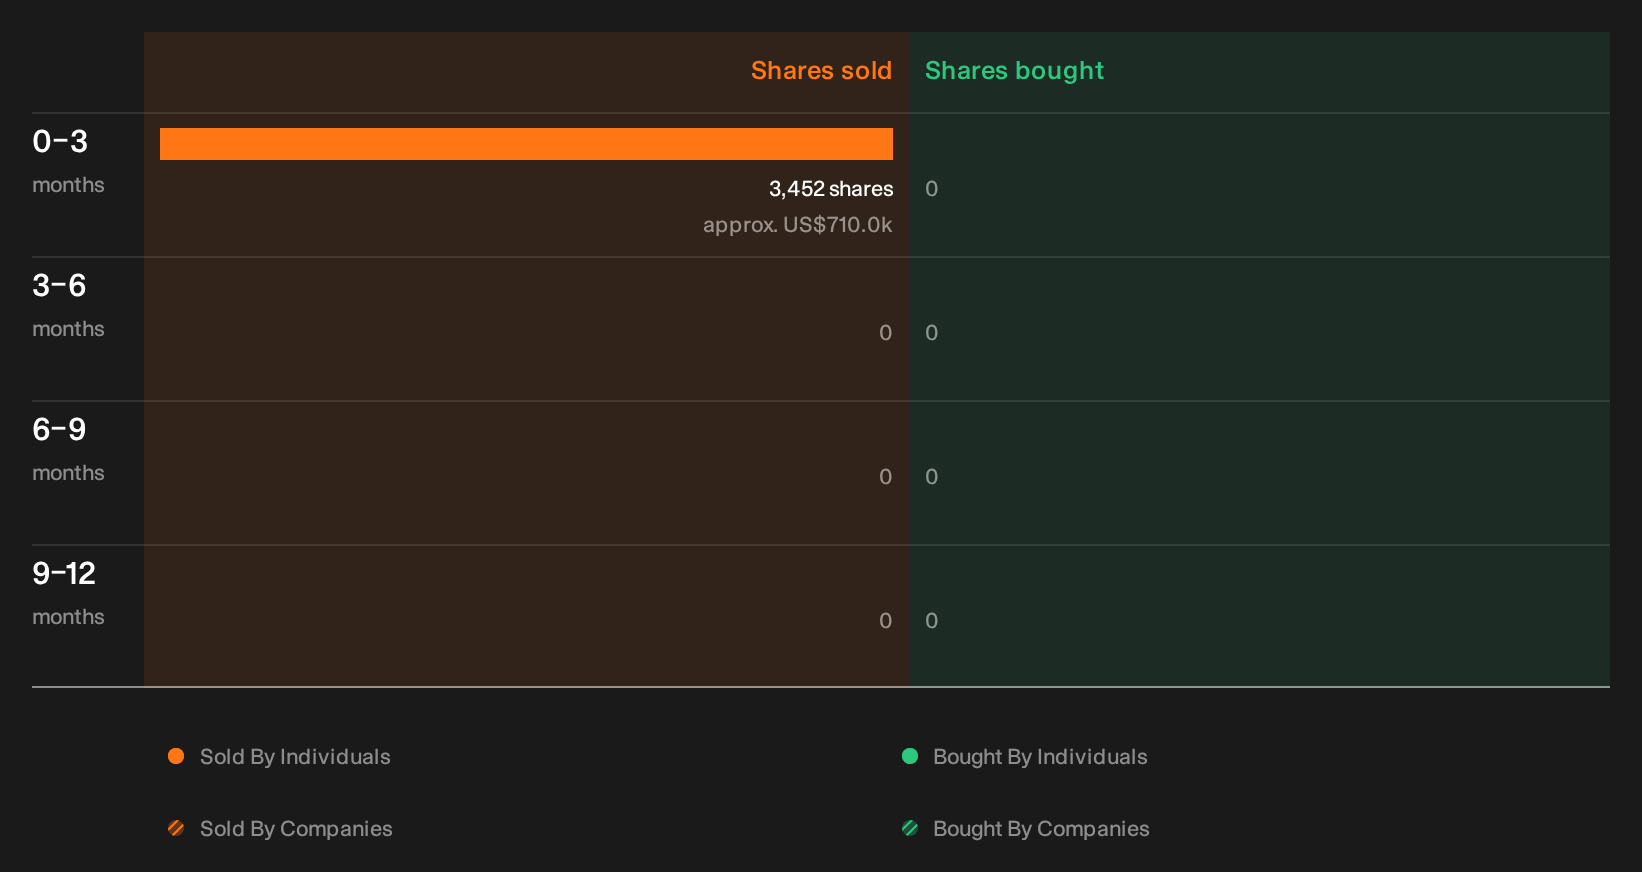
There is one other thread worth pulling on with ICON, since recent checks picked up insider share sales and the identities, sizes and possible signals are still for you to weigh. See the recent insider selling flagged for ICON.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com