


EN
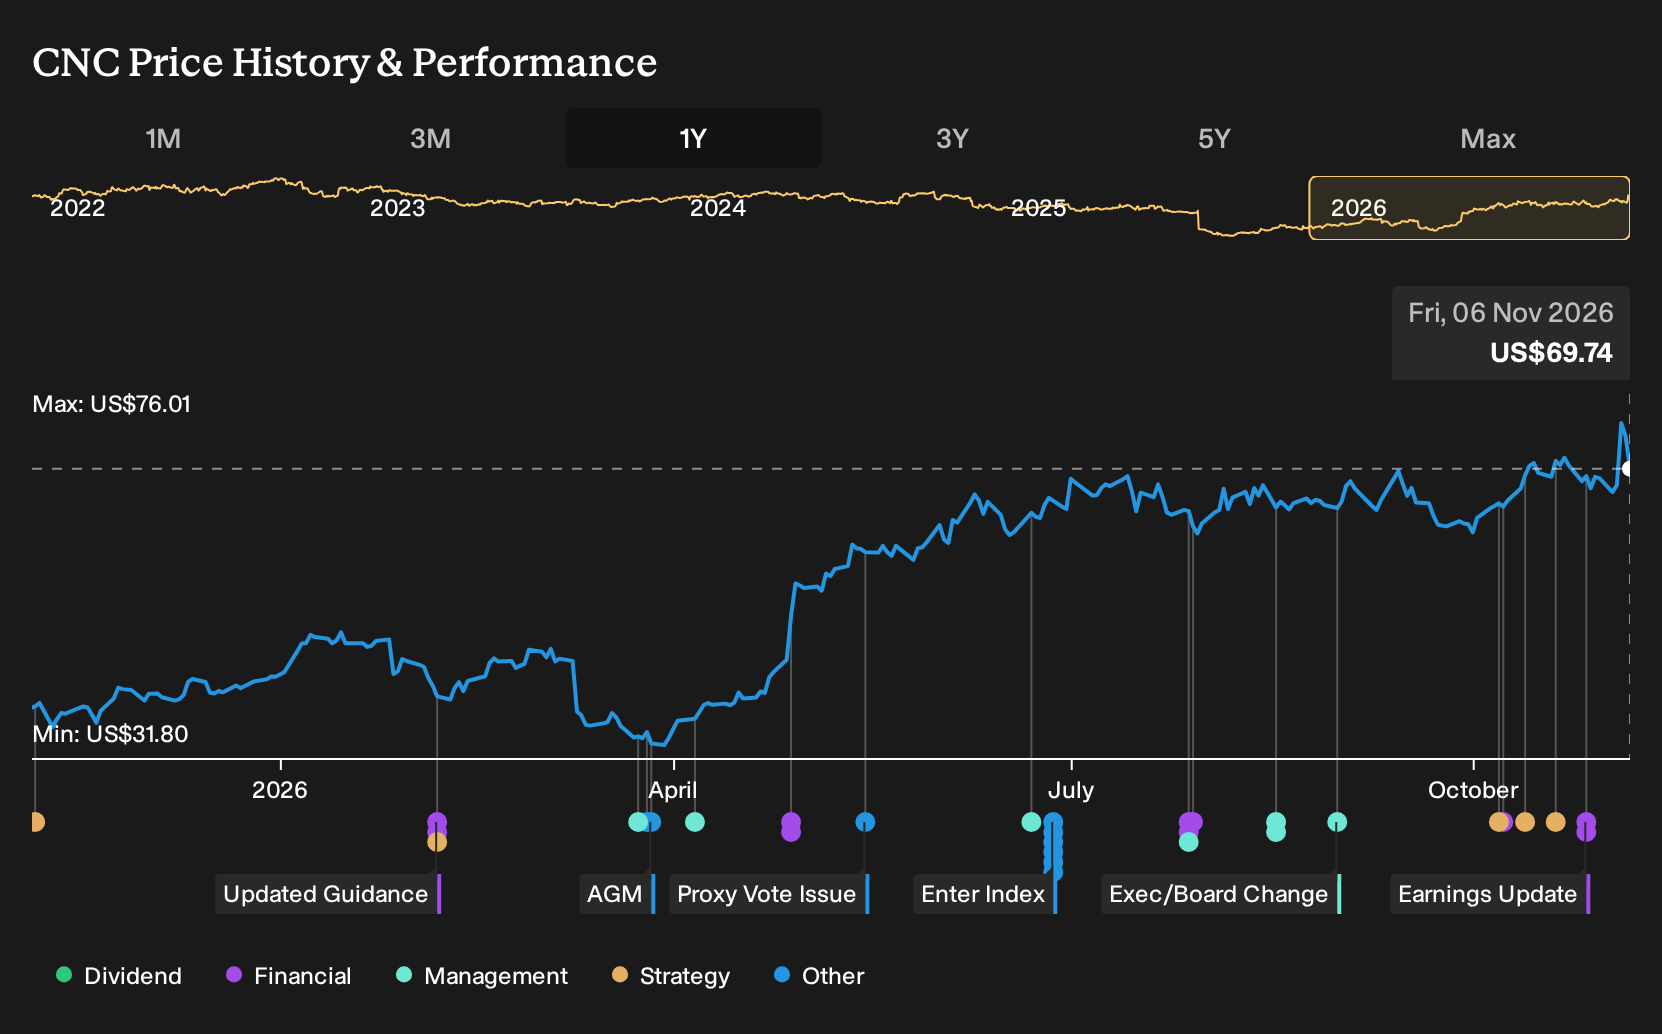
Did Raised Guidance Just Shift Centene (CNC) Investment Narrative?
- Centene reported third quarter 2026 revenue of US$50.647b and a net loss of US$71m, with nine month revenue of US$154.17b and net income of US$2.561b, alongside basic EPS from continuing operations of US$5.19 for the period.
- The swing from a nine month loss of US$5.573b a year earlier to profit, paired with higher full year revenue and GAAP EPS guidance, reflects management's focus on restoring profitability across Centene's government focused health plans.
- We will now look at how Centene's stronger year to date profitability and higher 2026 guidance may influence the investment narrative.
Scan how Centene's profitability reset compares with peers by reviewing a hand picked 31 resilient stocks with low risk scores built around resilient balance sheets and more consistent earnings profiles.
Centene Investment Narrative Recap
To be comfortable owning Centene, you need to believe the reset in profitability can stick across Medicaid, Marketplace, and Medicare while policy and funding terms remain workable. The analyst consensus Narrative on Simply Wall St frames the core catalyst as margin restoration. The latest quarter shows that, even with a third quarter loss, the nine month profit and positive EPS indicate that this reset is at least feeding through the income statement.
The biggest near term swing factor is still Medicaid margins and membership trends, with policy changes and eligibility redeterminations creating real uncertainty. A slower than hoped margin recovery or weaker Marketplace support would affect that thesis. The fresh results and updated guidance do not fully remove these risks, but they do narrow the range of near term operating outcomes.
The most relevant announcement tied to this earnings release is Centene lifting its 2026 revenue guidance range to US$196.5b to US$200.5b and setting a GAAP diluted EPS floor above US$3.46. This connects directly to the margin expansion story across Medicaid, the recovering Marketplace book, and Medicare profitability efforts that analysts have focused on.
For you as a shareholder, that guidance provides a concrete yardstick to track execution against the catalysts set out in the analyst consensus Narrative on Simply Wall St, including the targeted Medicaid medical cost ratio, Marketplace pretax margin goals, and SG&A savings. Misses against those markers, especially if driven by policy changes or weaker rate yields, would quickly become the key risk to monitor.
Centene's narrative projects US$206.2b revenue and US$3.3b earnings by 2029. This implies forecast revenue growth of 4.6% per year and an earnings increase of about US$1.8b from earnings of roughly US$1.5b today.
Uncover why Centene's fair value indicates a 5% potential upside to its current price before sentiment closes that discount.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Centene’s balance sheet shift as the key catalyst, not just Medicaid margins. Before this earnings release, the bullish camp was assuming revenue could reach about US$226.1b and earnings about US$3.6b by 2029. You can compare that more upbeat path with consensus views and decide which narrative might now adjust after the latest results.
Explore 4 other Centene fair value estimates, including one that suggests as much as 201% upside from the current price!
Decide For Yourself
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Centene research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Centene. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Centene's overall financial health at a glance.
Looking For More Ideas Beyond Centene?
Once you have a view on Centene, it can help to cross check that thesis against other opportunities using the Simply Wall St Screener. That way you can see how different business models, balance sheet profiles, and cash flow stories stack up against the risks and rewards you are weighing here.
- If capital preservation sits high on your list, start with sturdier balance sheets and more predictable earnings by checking a list of solid balance sheet and fundamentals (25 results), which is geared toward financial resilience and fundamentals.
- If you are hunting for mispriced quality, compare Centene with a 19 high quality undiscovered gems that focuses on strong fundamentals where the market might not be paying full attention yet.
- If steadier income matters most, scan for payout focused opportunities using a 7 dividend fortresses that highlights companies combining higher yields with more robust financial profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com