


EN
KLA (KLAC) Could Be 38% Undervalued As Strong Results And Guidance Land
KLA (KLAC) has drawn fresh attention after reporting first quarter revenue of US$4.14b and net income of US$1.55b, and then pairing those results with detailed guidance for the December quarter.
KLA's latest numbers and guidance arrive just as the share price has been under pressure, with a 30 day share price return down 29.19% and a 90 day share price return down 30.92%, even though the 1 year total shareholder return is 14.32% and the 3 year total shareholder return is very large at about 2.7x. Recent headlines around fresh guidance, a new shelf registration tied to an ESOP related offering, and an affirmed quarterly dividend have come against that backdrop, so the sharp 6.69% 1 day share price gain to US$138.49 appears more like a bounce within a fading short term trend than the start of clear positive momentum.
Scan how KLA's recent swing compares with other chipmakers showing strong fundamentals and compressed valuations in our hand-picked 40 high quality undervalued stocks.
KLA looks like a powerhouse on the income statement, while the share price has just shed roughly a third in three months. So are you looking at a quality business finally on sale, or still fully priced?
Most Popular Narrative: 38.5% Undervalued
KLA last closed at US$138.49, while the analyst consensus Narrative on Simply Wall St points to a fair value of about US$225.08 using an 11.34% discount rate. This frames the recent share pullback against much higher earnings and cash flow expectations.
KLA’s ability to keep gross margin guidance around 62% for 2026 despite higher memory and tariff costs, together with free cash flow of about US$4b over the 12 months ending March 2026 and US$3.3b of capital returned over the year to June 2026, points to a profitable, cash generative model that can support future earnings and per share growth.
See why 124 investors see KLA as 38% undervalued.
Result: Fair Value of $225.08 (UNDERVALUED)
Still, the KLA narrative relies heavily on converting a US$12.5b backlog on schedule and on China demand not softening further under export or tariff pressure.
Find out about the key risks to this KLA narrative.
Another View: KLA On Earnings Multiples
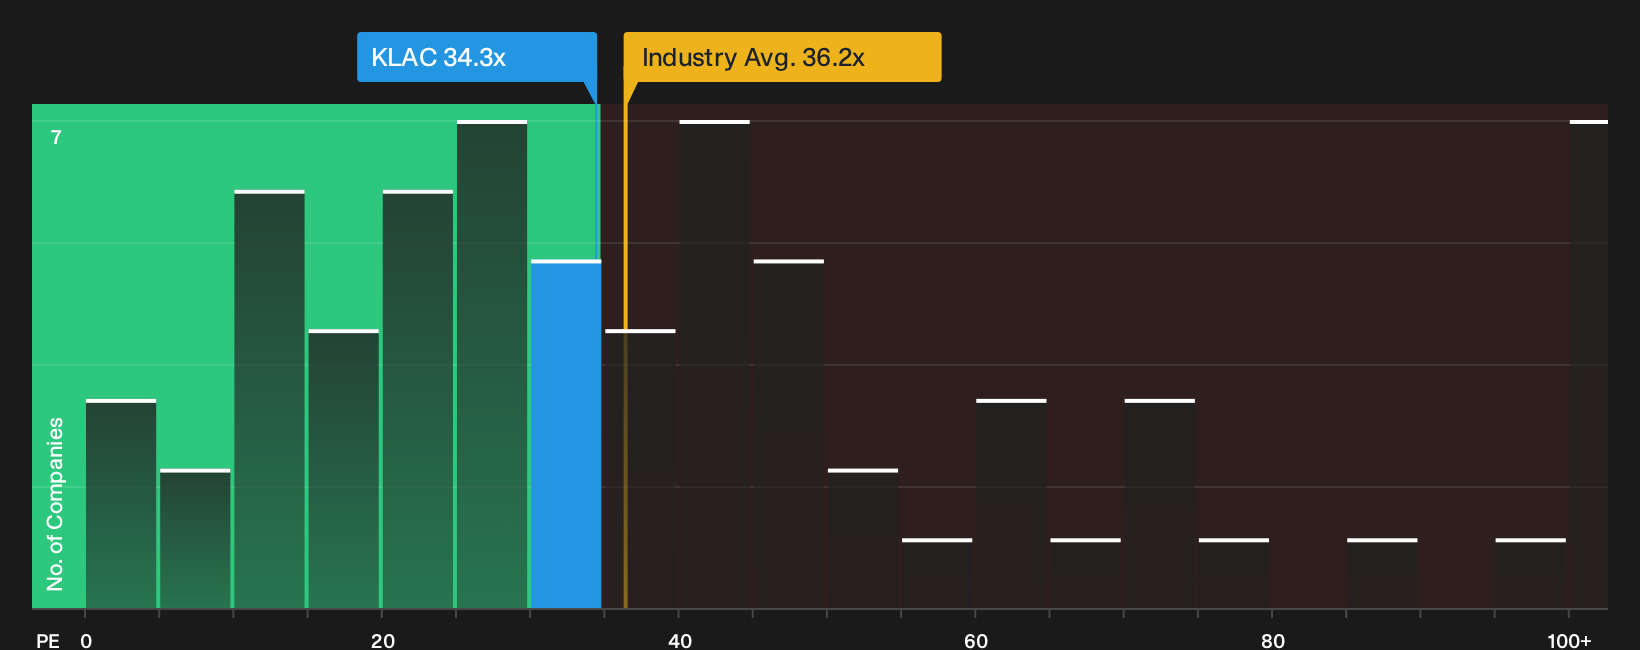
The story looks different if you stop at the P/E line. KLA trades on a P/E of 34.3x, just under the US Semiconductor industry at 36.2x. It is also above a peer average of 31.7x and only slightly above a fair ratio of 34.1x, which points to limited valuation cushion if sentiment weakens.
In practical terms, that means the stock screens cheaper than the broader sector but richer than its immediate peer group, with only a small gap to the fair ratio that the market could move toward. The question for you is whether that thin margin feels like room for upside or a sign that expectations are already quite full.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
After all this mixed sentiment around KLA, the real edge is seeing the numbers for yourself and reaching a view before the crowd reacts. To pressure test whether the market optimism lines up with your own thesis, start with the 4 key rewards.
Looking for more investment ideas beyond KLA?
Do not stop your research at a single ticker. Broaden your watchlist now so you are not chasing opportunities after they have already moved.
- Target long term value hunters by scanning our 40 high quality undervalued stocks and compare how other high quality businesses stack up on price versus fundamentals.
- Strengthen your downside protection by sorting companies with durable finances in the list of solid balance sheet and fundamentals (25 results) so potential weak links do not creep into your portfolio.
- Spot lesser known opportunities early by reviewing the 19 high quality undiscovered gems before attention and capital crowd into the same few tickers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com