


EN
SEGRO (LSE:SGRO) Stock Could Be Overvalued Even After A 34% Gain
SEGRO has delivered a strong 34.0% total return over the past three years, which puts fresh focus on whether the current share price is adequately supported by its earnings power. With the stock closing at £9.13, the key issue for you is how much of that move reflects enduring profit potential rather than just sentiment around logistics real estate.
- A 34.0% gain over three years raises the question of whether SEGRO's earnings justify the re-rating investors have already seen.
- The Vanguard Group's disclosure of a 5.67% stake in SEGRO in early November 2026 can signal confidence in the company's ability to keep generating and growing profits from its industrial property portfolio.
- The analysts covering SEGRO have run their own numbers. See what analysts think SEGRO's shares could be worth.
The stock's next move may depend on whether SEGRO's current earnings profile is strong enough to support the price you see on screen today.
If you are weighing whether SEGRO's 34.0% three year return is fully backed by its earnings, it can help to compare that question across 14 high quality undervalued stocks.
Is SEGRO Getting Expensive on Earnings?
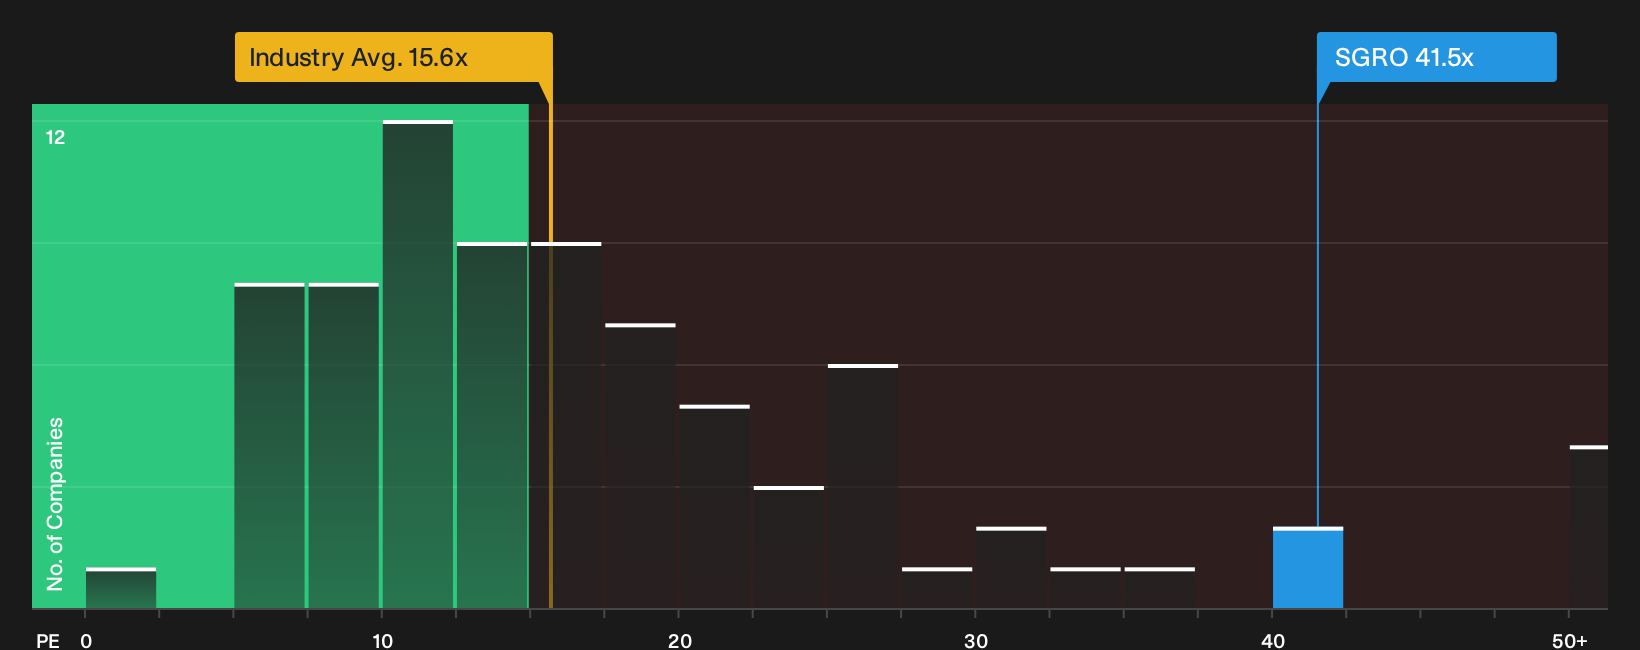
The P/E ratio suits SEGRO because investors often look to earnings-based multiples first when judging real estate investment trusts. At a current P/E of 41.5x, SEGRO trades at a much richer level than the industrial REITs group, where the average sits at about 15.6x, and it also carries a clear premium to the peer average of roughly 14.2x. That kind of gap indicates that the market is willing to pay a high price for each pound of reported earnings.
The fair P/E that fits SEGRO's profile is lower than where the shares change hands, so on this framework the stock screens as overvalued. Because The Vanguard Group has disclosed a 5.67% holding in early November 2026, some of this valuation stretch may reflect confidence from large institutions as well as SEGRO's current earnings power. For anyone considering the shares today, the key question is whether the quality and durability of those profits fully justify paying a P/E that far above sector and peer levels. Explore the numbers behind SEGRO's P/E valuation.
The SEGRO Narrative: What Would Justify Today's Price?
Simply Wall St Narratives take SEGRO's rich P/E debate and turn it into clear future paths, spelling out which combinations of growth, margins and earnings would need to hold for the shares to be worth meaningfully more or less than today. Instead of leaving you with a single output from a ratio or model, they set out the future that number depends on so you can follow whether SEGRO's actual progress keeps matching that picture over time on the Community page.
One of the top community narratives on SEGRO: roughly fairly valued
According to Composite_Research, an investor in the Simply Wall St Community, SEGRO’s shift toward data centers and power capacity is reshaping how its real estate is viewed.
"In the 'Fully Fitted' model, SEGRO also installs and leases the mechanical and electrical infrastructure within the building, which translates to materially higher cash flow generation…"
Discover why this Narrative puts SEGRO at roughly fairly valued.
SEGRO's valuation still leaves one crucial angle unexplored
Numbers only tell part of the story, because the people setting SEGRO's priorities and the way they are rewarded can strongly influence how those figures evolve over time. See who runs SEGRO and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com