


EN
Should Lower Oil Prices Require Action From DHT Holdings (DHT) Investors?
- DHT Holdings plans to report its Q3 2026 results after the market closes on November 9, with investors watching crude tanker fundamentals, charter mix and dividend capacity closely.
- Recent easing of conflict risks around Iran and softer crude prices highlight how macro oil flows and freight demand can quickly reshape DHT Holdings’ earnings sensitivity.
- We will now look at how easing geopolitical risk and softer oil prices could reshape DHT Holdings’ existing investment narrative.
Scan how investors are repricing crude tanker risk around DHT Holdings by comparing it with our curated set of 31 resilient stocks with low risk scores.
DHT Holdings Investment Narrative Recap
DHT Holdings appeals to shareholders who buy into a crude tanker cycle that can still support healthy time charter rates and meaningful dividends, even as earnings volatility remains high. The analyst consensus Narrative on Simply Wall St leans on tight VLCC supply, long route disruptions and a young fleet to underpin that story. Recent easing of conflict risk and softer crude prices mainly hit sentiment rather than the operational setup, so the near term focus stays on freight rate resilience into Q3 and Q4.
The most immediate catalyst is the Q3 2026 report on November 9, where investors are likely to watch TCE levels, time charter coverage and dividend declarations closely. The key risk is that a softer rate environment, combined with already large payouts versus free cash flow, exposes the 100% of ordinary net income dividend policy. Any signs that earnings or cash conversion are under pressure could force investors to rethink how sustainable the current payout really is.
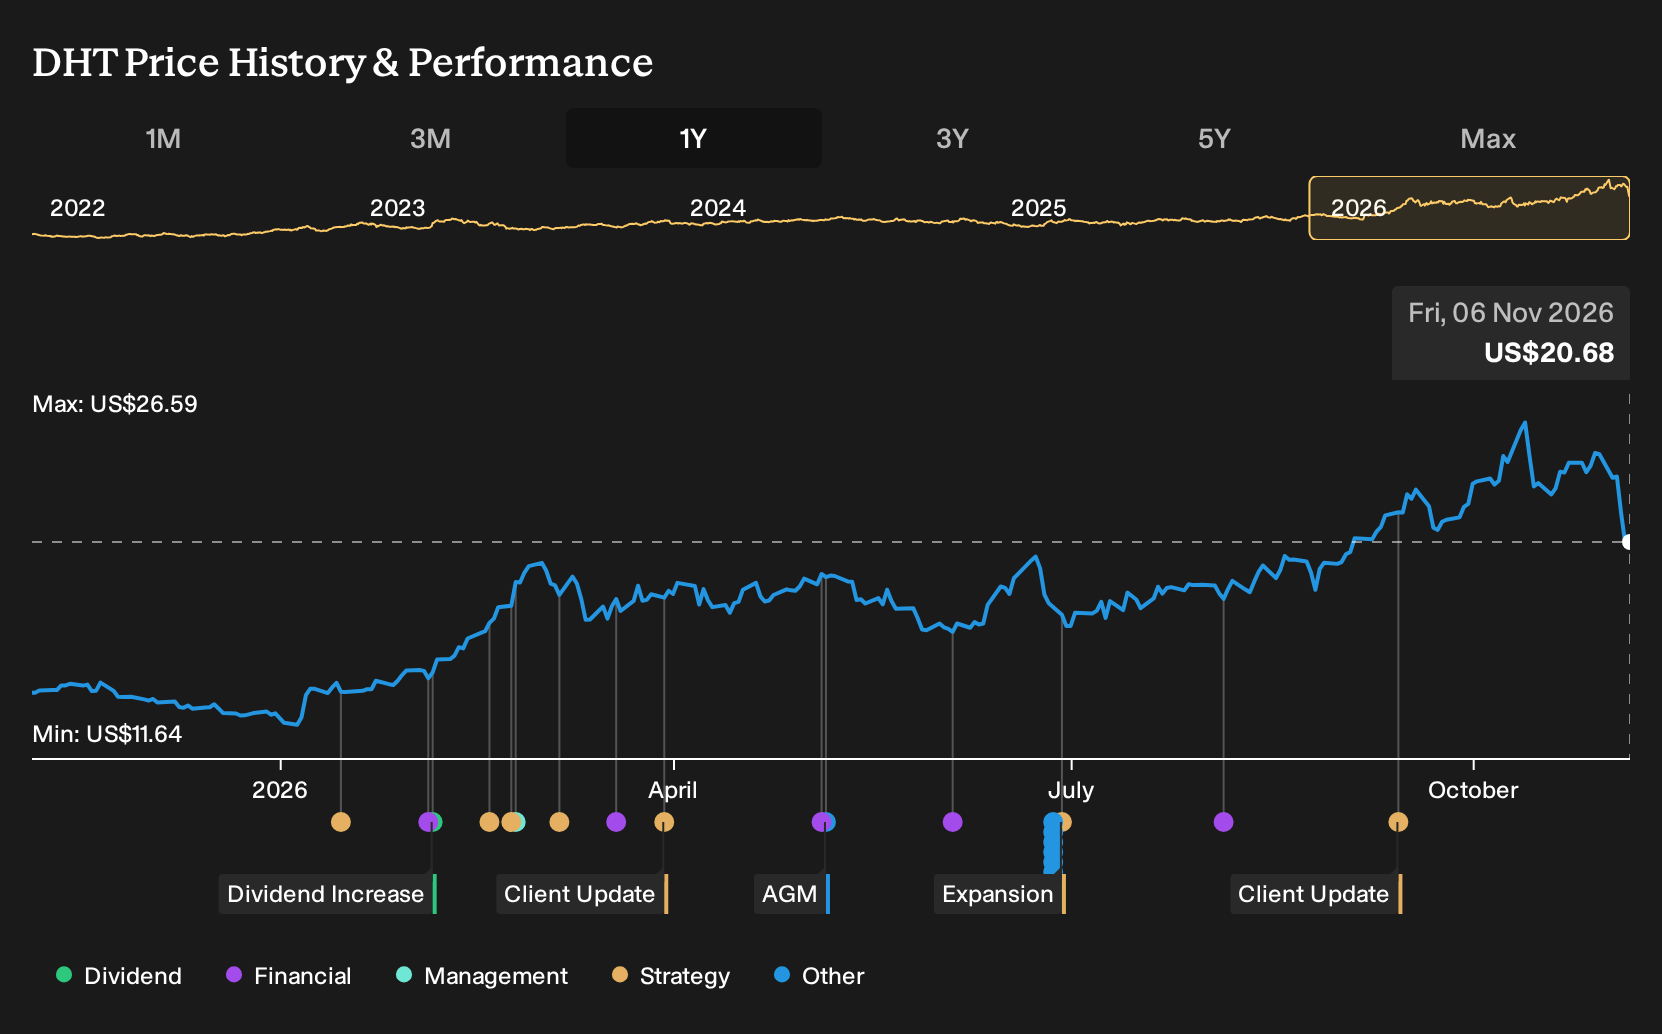
The upcoming Q3 2026 earnings release is the announcement that ties everything together. DHT Holdings has seen its share price decline 5.6% recently as the market reacted to easing war fears around Iran, lower crude prices and reduced expectations of further strikes after the U.S. midterms. That move came after a strong multi year share price surge, so expectations have already been reset somewhat ahead of numbers.
This print now intersects with the catalysts and risks flagged in the analyst consensus Narrative on Simply Wall St. Tanker fundamentals, cash generation and any commentary on the dividend will be read against forecasts for revenue and earnings to decline over the next three years and concerns about high non cash earnings. For readers, the practical question is how Q3 data points influence views on dividend sustainability, balance sheet flexibility and the path of earnings volatility from here.
DHT Holdings' current analyst narrative points to revenues of US$477.6 million and earnings of US$282.2 million by 2029, built on a forecast yearly revenue decline of 15.7% and an earnings drop of about US$191.5 million from the US$473.7 million reported today.
Uncover why DHT Holdings' fair value indicates a 32% potential upside to its current price, which could close faster than many investors expect.
Exploring Other Perspectives
One alternate view on DHT Holdings focuses on how far earnings could compress if spot exposure backfires. The most cautious analysts were pencilling in revenue of about US$352.6 million and earnings of US$161.4 million by 2029, far below consensus. Those projections were set before this Q3 results date was announced, so your own interpretation may differ once fresh data arrives.
Explore 6 other DHT Holdings fair value estimates, including one that suggests as much as 36% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DHT Holdings research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for DHT Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DHT Holdings' overall financial health at a glance.
Looking for more investment ideas beyond DHT Holdings?
Once you have a view on DHT Holdings, it can help to cross check that thesis against other stocks that fit different profiles using the Simply Wall St Screener.
- For investors who care most about balance sheet strength and durable fundamentals, start with a list of solid balance sheet and fundamentals (25 results) that can help you filter for resilience.
- If value opportunities are your priority, consider a 40 high quality undervalued stocks that highlights businesses combining quality metrics with more modest valuations.
- Income focused readers can target yield potential by scanning a 7 dividend fortresses that concentrates on higher paying stocks with recurring distributions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com