


EN
Does Raised Sales Outlook Change The Bull Case For Zebra Stock (ZBRA)?
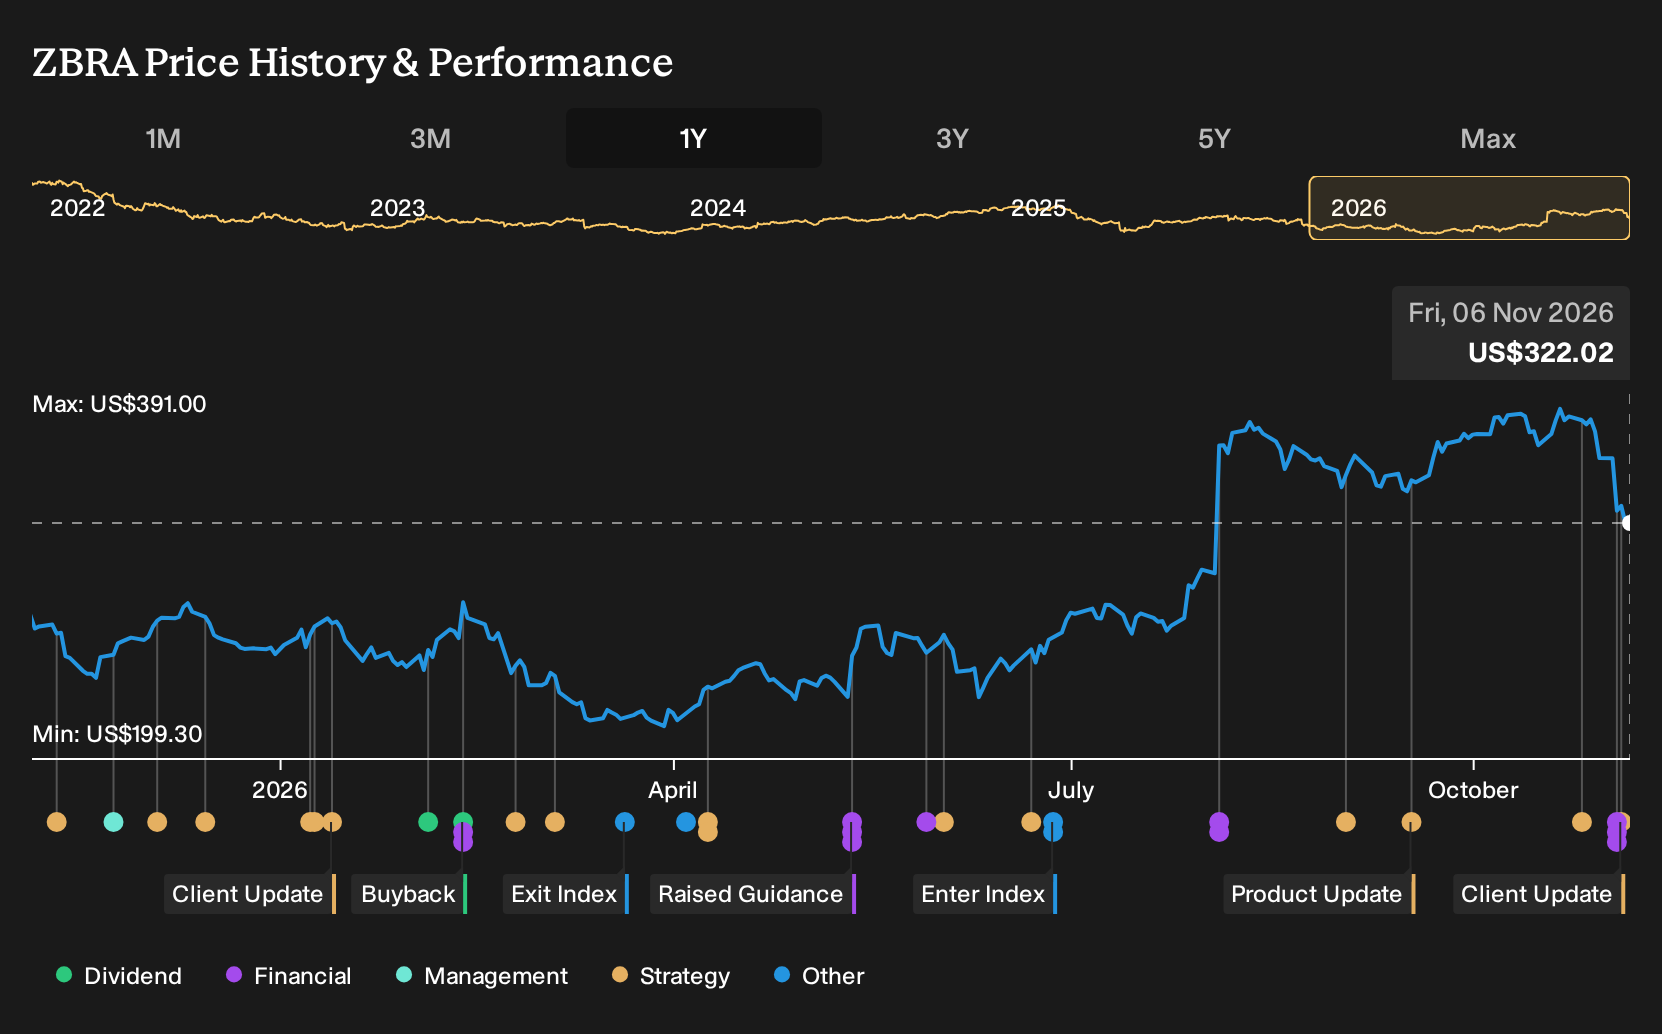
- Zebra Technologies reported third quarter 2026 revenue of US$1,614 million and net income of US$164 million, along with raised full year sales growth guidance.
- The combination of higher earnings, confirmed fourth quarter guidance supported by backlog and FX, and ongoing share repurchases underscores management’s focus on growth, capital discipline and operational execution.
- The focus now shifts to how this upgraded 2026 sales outlook might reshape Zebra Technologies broader investment narrative and risk balance.
Zebra Technologies Investment Narrative Recap
To own Zebra Technologies, you need to be comfortable with a story built around warehouse automation, AI enabled devices and software that helps large customers run frontline operations with fewer errors and less manual work. The analyst consensus Narrative on Simply Wall St leans on that backdrop plus guidance for stronger 2026 sales. Recent Q3 results and the higher full year sales outlook keep that operational thesis intact, while leaving tariff exposure, debt levels and memory cost management as key watchpoints.
In the near term, the most important swing factor is whether customers keep prioritising higher end Zebra Technologies solutions, including machine vision, RFID and AI capable mobile computers, which support mix and margin. The largest risk is that pressure in more price sensitive segments, such as point of sale and consumer facing hardware, limits pricing or shifts product mix, especially if trade policy or component costs move against the business and squeeze profitability.
The announcement of bespoke Zebra Technologies solutions at JD Sports looks most relevant here. JD rolled out TC2 Series handhelds, RFD40 RFID sleds and related software across 414 outlets in roughly three months, reporting better on shelf availability, faster replenishment and improved order fulfilment. That is a concrete example of the automation and digitisation trend that underpins the current earnings guidance.
For catalysts, wins like JD and ORAFOL tie directly into the themes analysts focus on, including automation, AI enabled workflows and software attach. They also show how Zebra Technologies combined hardware, software and services can embed deeply in customer operations, which can support recurring work and refresh cycles. The flip side is execution risk. Large, rapid deployments raise the bar on support quality and product reliability, since any misstep could slow follow on deals or temper demand from similar clients.
Zebra Technologies' current narrative centers on analysts expecting revenue to reach US$7.2b and earnings to reach US$1.0b by 2029. That path assumes 7.0% yearly revenue growth and an earnings increase of about US$461.0m from US$539.0m today.
Uncover why Zebra Technologies' fair value indicates a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Some of the most optimistic analysts frame the JD Sports rollout as proof that Zebra Technologies could lean harder into large scale deployments. Before this update, the bullish camp was already pencilling in revenue of about US$7.5b and earnings near US$1.1b by 2029. That is a very different story from the more cautious forecasts. Treat this as one lens and compare it with other views before deciding what feels realistic for you.
Explore 4 other Zebra Technologies fair value estimates, including one that suggests there could be as much as 68% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Zebra Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Zebra Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Zebra Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Zebra Technologies?
If the Zebra Technologies story has you thinking about where else automation, cash generation or balance sheet resilience could matter, it can help to widen the lens and scan a broader set of opportunities using the Simply Wall St Screener.
- For income focused investors who value consistency, review companies that appear as 7 dividend fortresses and see which payouts align with your comfort level.
- If capital preservation and steadier business profiles appeal to you, filter for 31 resilient stocks with low risk scores that may better match a more cautious approach.
- When you want to hunt for potential future leaders before they attract wider attention, sort through 19 high quality undiscovered gems and see which stories resonate with your own research process.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com