


EN
Top 3 Australian Undervalued Stocks To Watch In November 2026
Precious metals have drawn fresh interest after concerns about how the United States manages its economy and fiscal position, which has pushed many investors toward hard cash flows instead of headline stories. That focus on money in the door makes undervalued Australian cash generators especially interesting, where prices sit below estimates of fair value based on discounted cash flow work. This article walks through three such stocks from our cash flow value screen.
The three Australian precious metal producers highlighted below are only a sample from this cash flow value approach, with the full screen surfacing 3 more businesses with equally interesting stories that are not covered here. To size up the whole opportunity set and identify which ideas best fit your portfolio, go straight to the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper producer whose Havieron project in Western Australia anchors its role in this cash-flow-focused screen, with the integrated Telfer-Havieron hub generating A$2.26b from that segment and the business carrying a market value of about A$6.94b.
That cash engine is what matters for value hunters. According to redrum9128, an investor in the Simply Wall St Community, the investment case now hinges on how a maturing producer converts that asset into durable cash generation rather than just headline resource potential.
"The primary driver of Greatland’s future is the gold price. As a single asset developer moving toward production, it offers significant operational leverage to gold."
What happens if a single pressure point on future profitability shifts in either direction will do a lot of the work for investors here.
The weight investors put on that single driver is exactly what the full narrative for Greatland Resources unpacks, showing where operational leverage could accelerate or stall the story.
Ansell (ASX:ANN)
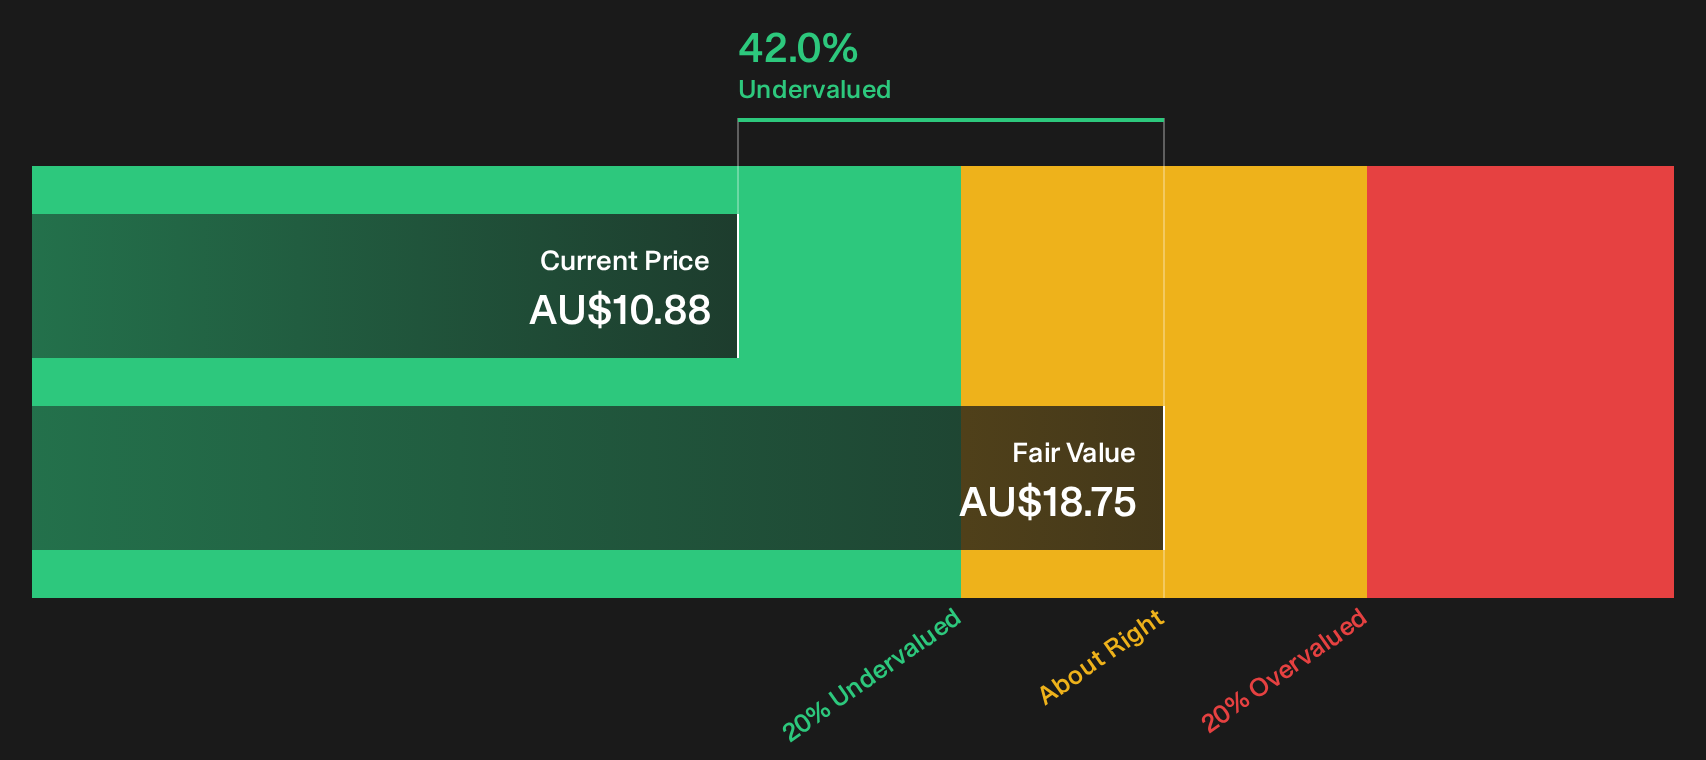
Ansell is a global personal protection specialist. Its Healthcare arm, built around high margin disposable surgical and examination gloves and related consumables, anchors its role in this cash flow screen. The segment generates about US$1.19b of sales alongside US$947 million from Industrial, with the group valued near A$6.34b.
Where Greatland turns on a single resource asset, Ansell offers a different type of cash engine through its Healthcare consumables. Reyyyyy, an investor in the Simply Wall St Community, argues that this recurring glove demand is what really ties the business to a discounted cash flow themed screen.
"Ansell is positioned to capture the structural tailwinds in global PPE demand through both organic and inorganic expansion."
What happens if one unseen pressure on glove margins and capital returns shifts will likely matter far more than headline revenue forecasts.
If that unseen pressure on margins is what you care about, the full narrative for Ansell explains how recurring glove demand could either accelerate Ansell’s cash story or cause it to stall.
Origin Energy (ASX:ORG)
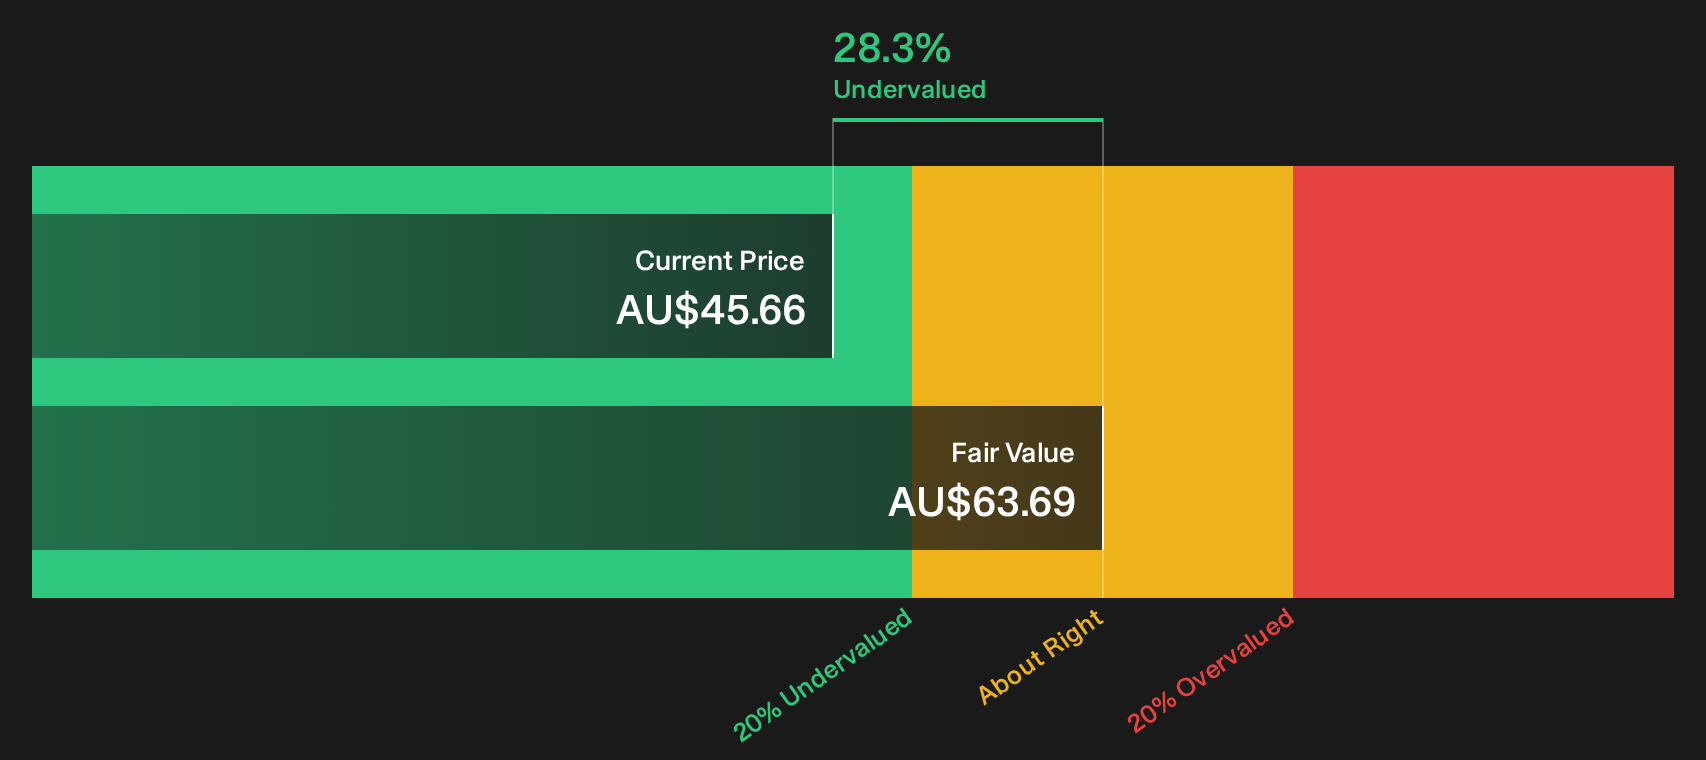
Origin Energy is a long-established integrated power and gas group where cash-generating wholesale and retail energy activities, plus upstream gas production, anchor its role in this cash-flow-focused screen. Most income comes from the A$15.26b Energy Markets segment, with Integrated Gas contributing A$307 million and the business valued near A$20.82b.
For Origin Energy, the analyst consensus Narrative on Simply Wall St highlights how its everyday energy markets cash flows feed into the cash-based value case. It also flags some important moving parts investors need to watch before deciding how comfortable they feel with that story.
"Continued growth in rooftop solar, home batteries and the 1.6 GW virtual power plant, supported by rising adoption of customer electrification products, can shift more consumption behind the meter and reduce grid supplied volumes."
What happens if a single assumption about how those behind the meter trends affect long term earnings power proves too optimistic or too cautious will matter a lot.
If that long term earnings power is the real question for you, the full narrative for Origin Energy explains how behind the meter trends could either accelerate or quietly cap Origin Energy’s cash engine.

Curious To Explore The Alternatives?
Fresh ideas keep emerging while attention focuses on yesterday’s moves. Some of the sharpest picks remain under the radar for now. Do not get caught falling behind; aim to act early.
- Target dependable income streams by scanning a curated pool of yield-focused opportunities through the 5 dividend fortresses before dividend momentum shifts.
- Spot early movers in transformative computing by reviewing the handpicked universe inside the 25 quantum computing stocks while the theme is still relatively under the radar.
- Track AI suppliers supporting real world infrastructure demand by checking the focused group highlighted in the 53 AI infrastructure stocks as market interest evolves.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com