


EN
Glaukos (GKOS) Jumped, What Is Behind The Fresh Attention?
Glaukos earnings and index shift catch investor attention
Glaukos (GKOS) is back on investor watchlists after third quarter 2026 results showed a move into profitability, paired with raised sales guidance and a shift from the S&P 600 to the S&P 400.
The fresh guidance and index reclassification create two parallel storylines for the stock. One is about the scale of the underlying ophthalmic business. The other is about how a different group of institutions might approach the shares after the index move.
Glaukos has ridden a strong wave of buying interest, with a 30 day share price return of 35.44% and a year to date share price gain of 102.68%, while total shareholder return over five years has reached 357.98%. This points to momentum that recent guidance upgrades and the move into the S&P 400 have helped keep in focus.
Scan for other healthcare names showing similar earnings momentum and index shifts using the hand picked 35 healthcare AI stocks that keeps you focused on potential Glaukos style catalysts.
Glaukos now appears to be a much larger and more streamlined ophthalmic platform, yet the stock has already surged into the S&P 400 spotlight. Is this a strong business priced accordingly, or something beyond that?
Most Popular Narrative: 27% Overvalued
Glaukos closed at $224.41, while the bearish analyst Narrative on Simply Wall St places fair value near $176.97. The story hinges on whether current optimism outpaces the assumptions behind that lower figure and the 7.54% discount rate.
Although the company emphasizes high gross margins from iDose TR and Epioxa, the forecast increase in 2026 operating expenses to about US$600 million as it “adds fuel” to commercial investments creates a risk that incremental sales from interventional glaucoma and keratoconus therapies do not fully offset spending. This could limit operating leverage and cash flow improvement even if top line trends look healthy.
See why 2 investors see Glaukos as 27% overvalued.
Result: Fair Value of $176.97 (OVERVALUED)
Still, if iDose TR adoption accelerates or if Epioxa and the retinal pipeline scale faster than forecast, Glaukos could outgrow the cautious 2029 earnings assumptions.
Find out about the key risks to this Glaukos narrative.
Another View on Glaukos valuation
Glaukos looks expensive if you only focus on the headline P/S of 19.2x versus 2.8x for the US Medical Equipment group and 3.8x across peers. The fair ratio estimate of 10.9x points to a big gap that could matter if sentiment on high growth healthcare cools.
To see what the underlying numbers imply beyond this simple sales multiple, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
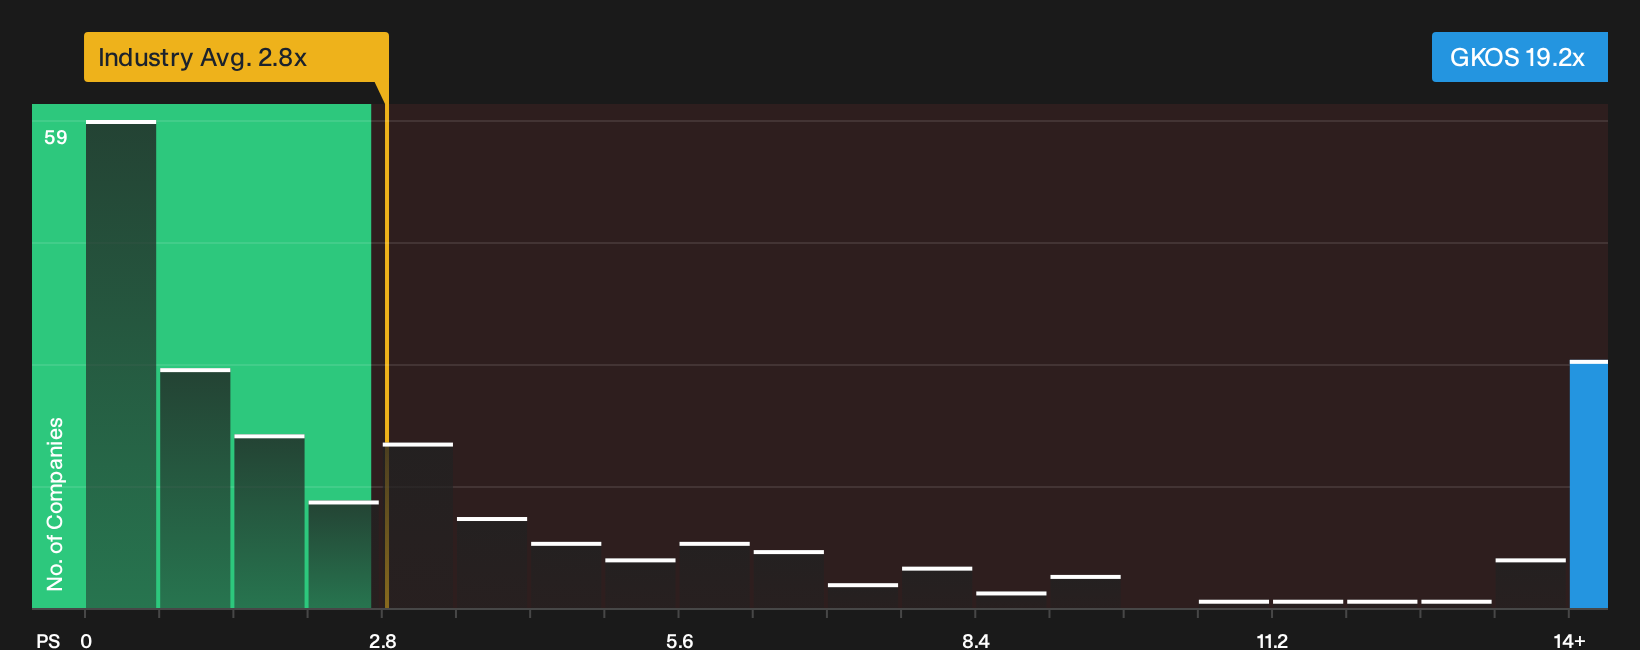
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Glaukos for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 40 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed views on Glaukos after all this. Move quickly from headline reactions to hard numbers by weighing both sides through the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Glaukos?
Glaukos may be front of mind today, but your next strong idea could be sitting just outside your current watchlist if you know where to search.
- Target sturdier portfolios by focusing on resilience first, then use the 31 resilient stocks with low risk scores to see which companies clear that quality bar.
- Hunt for value where fundamentals still matter, filtering the market with the 40 high quality undervalued stocks before sentiment moves on to the next story.
- Spot lesser known opportunities early by scanning the 19 high quality undiscovered gems that pair solid financials with lower crowd attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com