


EN
Coupang Shares Slid Even Though Sales Rose
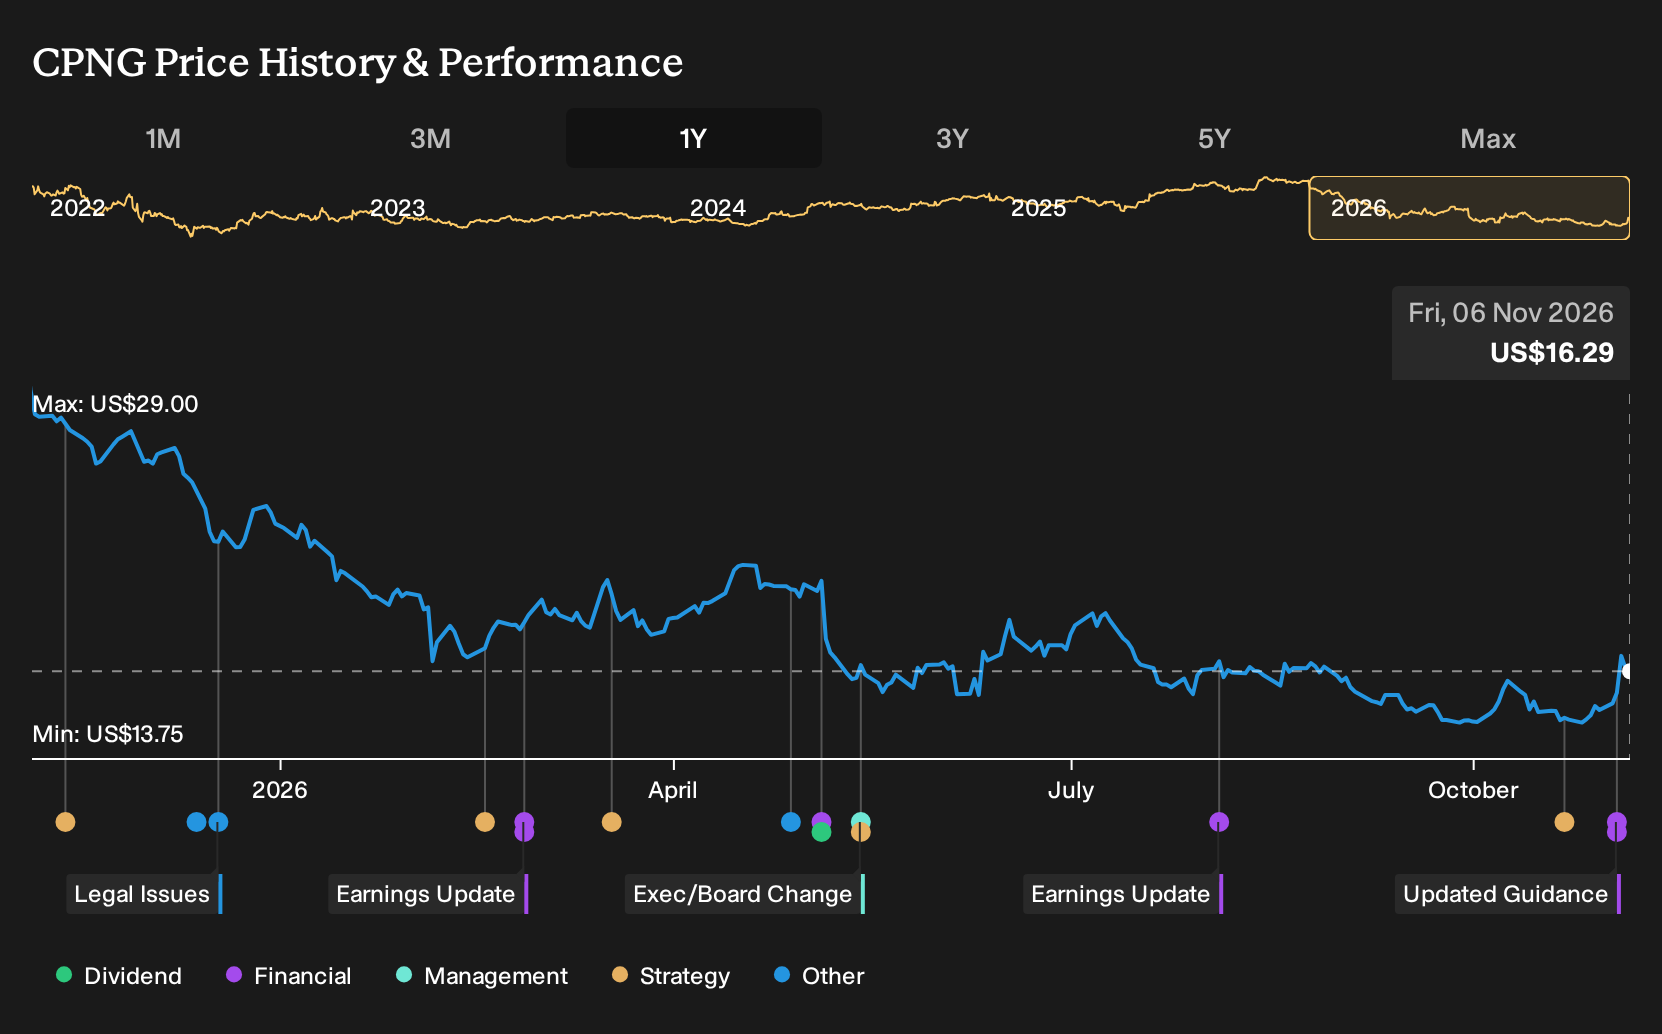
If Coupang looked like a clear beneficiary of AI driven logistics and international expansion, the outcome for holders was far more painful. For Coupang shareholders, the loss over the past year was 43.7%, including dividends. Analysts had laid out detailed forecasts on margins and earnings, and management later reported revenue growth alongside sizeable losses and regulatory fines. The key question is which signals, if any, hinted this gap between business progress and shareholder outcome was on the cards.
This theme extends beyond Coupang. See which of 53 AI infrastructure stocks may still merit a closer look.
The Two Stories Investors Had To Choose Between On Coupang
The shares cost US$29 at the start of the period, and Coupang sat between two very different but plausible stories.
The bullish view saw a fair value of US$34.52, a notional target price based on assumptions that AI driven logistics, 14.0% revenue growth and a 4.2% profit margin could support a future P/E of 41.7x within three years.
The cautious narrative pointed to fair value of US$27.25, implying slower 12.0% revenue growth, a 3.6% margin and concern that intense competition and international expansion risked keeping profitability under pressure.
What The Results Changed For The Coupang Thesis
The most telling data point is that Coupang’s net margin moved from 1.0% in Q3 2025 to a 5.0% loss in Q3 2026, even as revenue reached US$10.0b. That shift challenged the bullish case that assumed a 4.2% profit margin, while the persistent operating losses and large data breach fines also leaned toward the cautious view.
The practical takeaway is clear. When a story leans on margin expansion, you need to track net margin and absolute profit in each filing and test whether new projects, fines or one off incidents are pulling those numbers away from the original script.
What Coupang's Lower Price Asks You To Believe Today
Coupang trades at US$16.29 today, with this analyst consensus Narrative on Simply Wall St suggesting a Fair Value that sits above that quote based on its own assumptions. The argument leans on technology, automation and capital allocation to eventually turn current operating strain into stronger earnings power.
The fall only looks like a potential opportunity if you think WOW membership, Taiwan, Eats and Rocket Now can offset fines, fires and higher expenses by translating strong customer spending into durable margin improvement.
"Key Takeaways: Analysts expect Coupang to keep using technology, automation, and capital allocation to improve operating leverage and support long term earnings power, even as current margins are affected by fines, capacity underutilisation, and higher marketing spend. The main thing that has to go right is that Coupang converts its strong cohort spending patterns, WOW membership recovery, and international expansion in areas like Taiwan, Eats, and Rocket Now into sustainable margin improvement while managing ongoing regulatory and operational risks in Korea."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
One Step Beyond Coupang
Coupang puts AI into delivery, but the digital journey does not end there. Your order still needs selling space and computing muscle.
Another heavyweight supplies the online shelves, streaming screens and rented servers many businesses lean on. Its tools help retailers run shops, place ads and rent AI ready infrastructure.
Where Coupang obsesses over the doorstep, this other platform focuses on the storefront and the data center. The same shopper can touch both without noticing.
If demand for smarter logistics endures, attention may drift toward whoever shapes those broader digital aisles and AI foundations next.
The case is on the record, with the assumptions it rests on. → See the Narrative that values this company 74% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com