


EN
Leonardo DRS (DRS) Wins Laser Program Work, Is It Still 35% Undervalued?
Leonardo DRS (DRS) just picked up fresh visibility with AeroVironment selecting the defense contractor to provide rugged integration work for the U.S. Army’s Enduring High Energy Laser production program, alongside recently reported third quarter results.
For investors tracking the bigger picture, Leonardo DRS now trades at US$34.04 after a 1-day share price return of 3.15%, yet the stock is still down over the past week and quarter, with a 7-day share price return of 9.66% and a 90-day share price return of 24.44% as some of this year’s earlier enthusiasm has cooled. Those near term moves contrast with a 3-year total shareholder return of 74.68%. The recent contract win, raised 2026 revenue outlook and fresh dividend declaration are landing against a backdrop where long term holders have already seen sizeable gains while shorter term momentum has been fading.
Scan defense and mission-critical tech opportunities that are moving on similar catalysts to Leonardo DRS with our curated list of 31 resilient stocks with low risk scores.
For Leonardo DRS, the backdrop of softer recent returns against stronger multi year gains raises a simple tension. Are traders just cooling on the story, or has the business moved further than the valuation has caught up?
Most Popular Narrative: 35% Undervalued
On the analyst consensus Narrative on Simply Wall St, Leonardo DRS screens as undervalued, with a fair value of $52.50 against the last close at $34.04. That gap rests on assumptions about defense budgets, contract conversion and margin resilience that investors need to weigh carefully.
Anticipated increases in U.S. and allied defense budgets with substantial front-loaded funding and new NATO commitments are still expected to support persistent demand for advanced defense technologies. This could help Leonardo DRS sustain multiyear revenue growth and support backlog and earnings. The company's alignment with national priorities in naval modernization, next-generation air and missile defense and counter UAS capabilities now has further support from new awards such as MK 41 VLS electronics and propulsion systems for at least six South Korean KDDX destroyers. These awards can extend revenue visibility and support net margins as these contracts move into execution.
See why 19 investors see Leonardo DRS as 35% undervalued.
Result: Fair Value of $52.50 (UNDERVALUED)
Still, if newer areas like counter UAS and space sensing fail to scale, or sector sentiment weakens again, the Leonardo DRS undervaluation story could easily stall.
Find out about the key risks to this Leonardo DRS narrative.
Another Take on Leonardo DRS Valuation
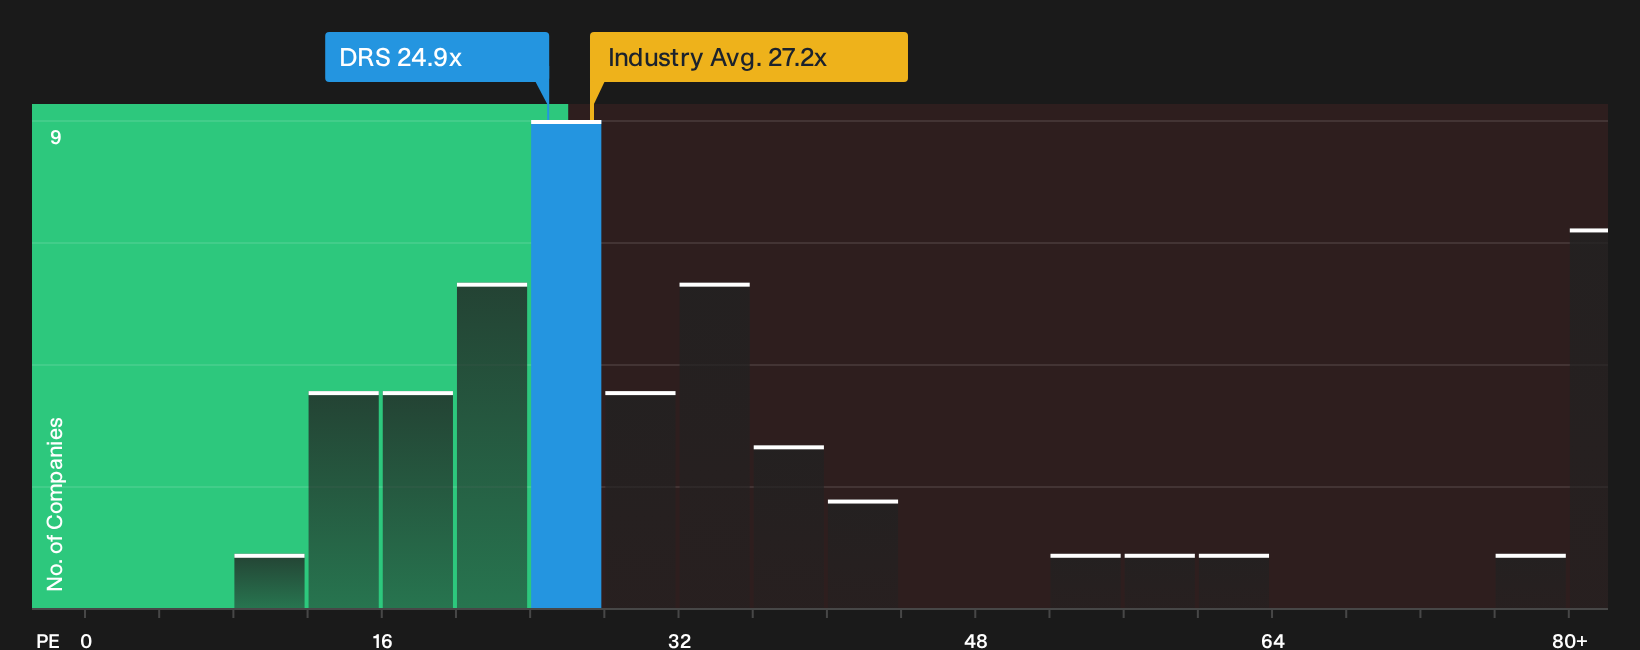
Analysts on Simply Wall St frame Leonardo DRS as materially undervalued on a fair value of $52.50, yet the current P/E of 24.9x sits above its own fair ratio of 22.2x and only slightly below the US Aerospace & Defense average of 27.2x. That mix of apparent upside with a richer than fair multiple leaves a simple question for investors: is this a mispricing, or is the market already baking in plenty of optimism?
For a closer look at how that P/E gap, peer comparison and fair ratio stack up in practice, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Leaning bullish after reading this, or feeling cautious about how much optimism is already in the Leonardo DRS story? Put the numbers in context for yourself by reviewing its 4 key rewards.
Looking for more investment ideas beyond Leonardo DRS?
If Leonardo DRS has your attention, now is the moment to widen your watchlist with a few targeted screeners that surface fresh opportunities you might otherwise miss.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (25 results) that pair financial strength with room for potential upside.
- Spot potential value opportunities early through the 40 high quality undervalued stocks, where stocks trade below their assessed worth based on current fundamentals.
- Build a watchlist of reliable income ideas using the 7 dividend fortresses focused on companies offering yields from 5% and higher.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com