


EN
How Verdi Hotels Deal Will Impact Accor (ENXTPA:AC) Stock
- Accor has agreed to add Corinthia's Verdi Hotels to its Handwritten Collection, expanding its managed portfolio and fee-based hotel network.
- The Verdi Hotels deal reflects Accor's efforts to grow higher quality management and franchise fees, which shapes expectations for its long term cash flow profile.
- This article examines how Accor's investment narrative is influenced by the Verdi Hotels partnership and its fee focused expansion.
Compare Accor's fee driven story with other potential value ideas by scanning our curated list of 222 high quality undervalued stocks that may not fully reflect their long term cash flow potential.
Accor Investment Narrative Recap
To own Accor, you need to be comfortable with a fee driven model that relies on converting its hotel pipeline, loyalty program and brand mix into steadier cash generation. The analyst consensus narrative on Simply Wall St leans on that idea, tied to expectations for both revenue and earnings advances over the next few years.
Right now, the near term swing factor is whether management and franchise EBITDA momentum can catch up with its 2023 to 2027 plan. The biggest risk remains pressure in the Middle East and China, where weaker RevPAR and ibis closures could blunt the benefit of new signings, so the Verdi Hotels news does not remove that concern.
The Verdi Hotels agreement fits into the same story as the binding sale of Accor's Essendi stake of up to €975m. Both push the group further toward an asset light structure with a larger managed and franchised base and less owned or leased exposure in the portfolio.
For catalysts, that matters because a lighter balance sheet and higher fee weighting can support more stable recurring income if execution holds. The risk is that weaker regions or slower EBITDA growth versus the internal plan keep offsetting these moves, which would leave the DCF implied undervaluation argument less compelling in practice.
Accor's narrative projects €6.9b revenue and €723.2m earnings by 2029. This assumes 6.6% yearly revenue growth and an earnings increase of about €493m from €230.0m today.
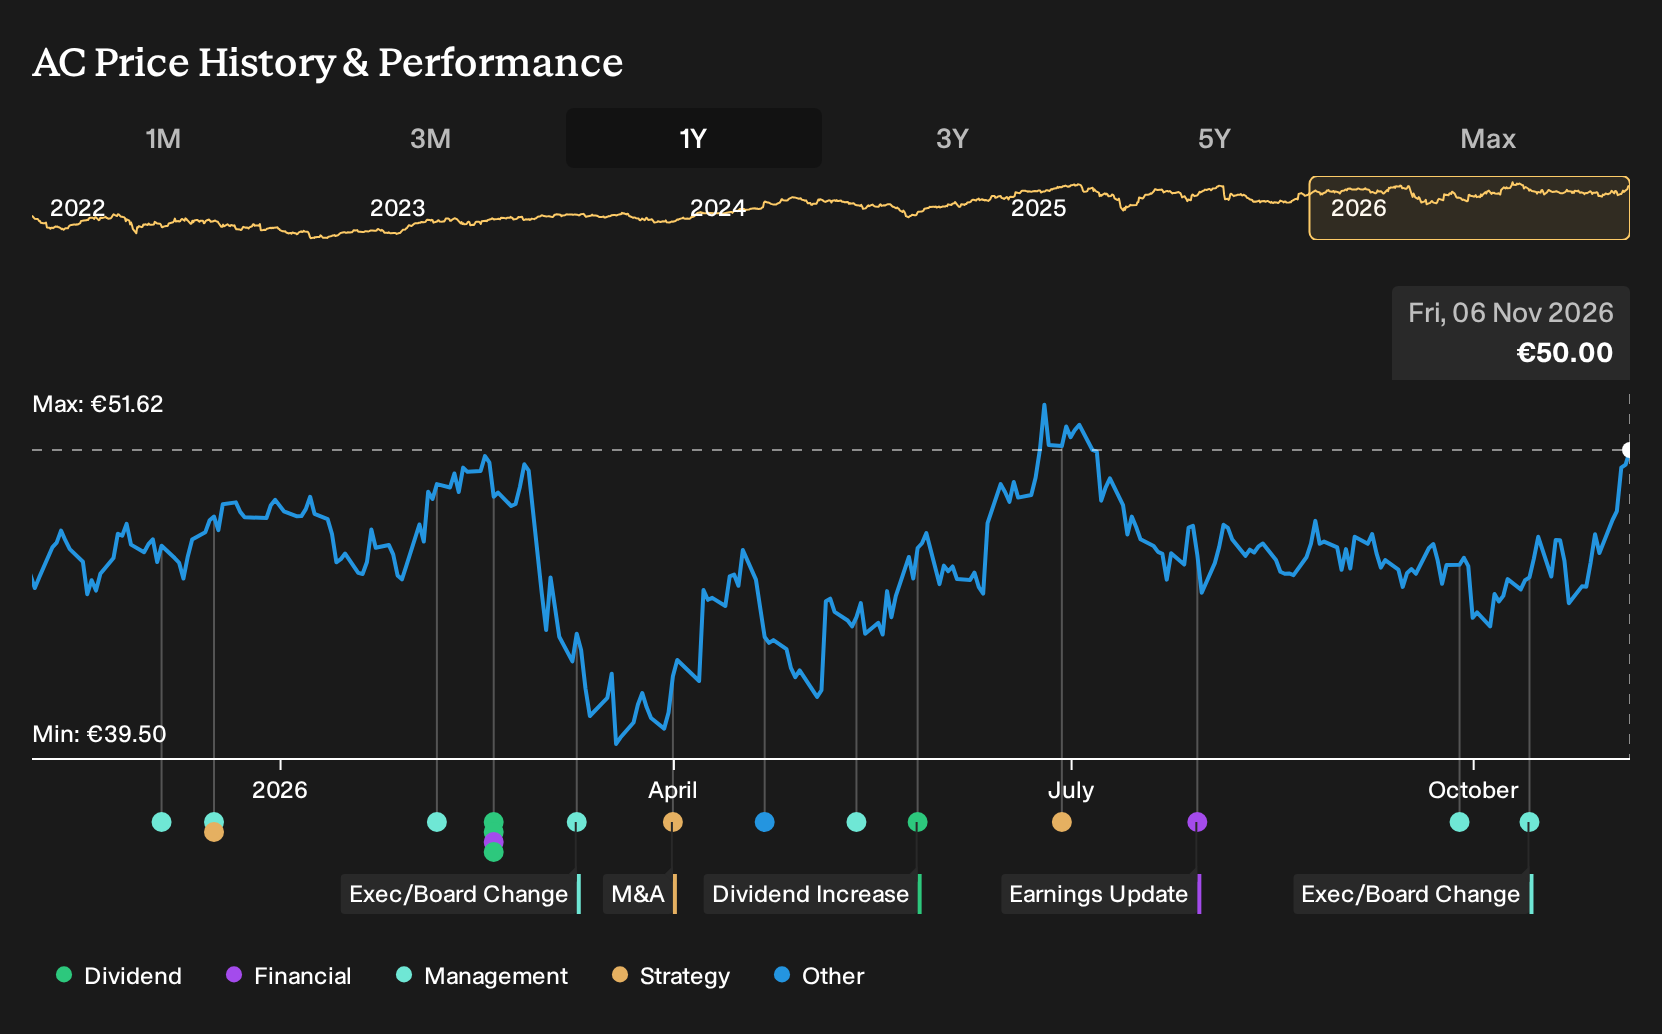
Uncover how Accor's fair value indicates an 11% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternate view on Accor zooms in on the risk that faster net unit growth disappoints. The most cautious analysts were only pencilling in about 5.2% annual revenue growth and roughly €704.8m in earnings by 2029. That is a far more restrained story than consensus, and the Verdi Hotels news could eventually nudge those assumptions in either direction.
Explore 2 other Accor fair value estimates, including one that suggests it could be worth just €55.39.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Accor research is our analysis highlighting 2 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Accor. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Accor's overall financial health at a glance.
Looking For More Investment Ideas Beyond Accor?
If the Accor story has sharpened your sense of what you want in a business, the next step is to line it up against other opportunities that match your style, risk tolerance and return goals using the Simply Wall St Screener.
- For investors hunting for quality at a discount, scan a curated pool of candidates through 222 high quality undervalued stocks that may trade below what their fundamentals suggest.
- If capital preservation and balance sheet strength sit high on your checklist, filter for resilient businesses using the list of solid balance sheet and fundamentals (193 results).
- Income focused investors who want cash paid today rather than only potential capital gains can zero in on yield heavy opportunities via the 226 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com