


EN
How Investors May Respond To Infineon Technologies (XTRA:IFX) AI Power Deals
- SOLUM, Vertiv and Enphase announced new agreements and product plans with Infineon Technologies that extend its silicon, silicon carbide and 900 V GaN power semiconductors deeper into AI data centers, grid tied systems and commercial power products.
- The trio of deals ties Infineon Technologies directly into customers' next generation AI power architectures, from 800 VDC data center backbones to solid state transformer platforms. This highlights how embedded its components are in future infrastructure design decisions.
- We will look at how Infineon Technologies' AI focused power alliances with Vertiv shape the existing investment narrative around capacity ramps.
Infineon Technologies Investment Narrative Recap
To own Infineon Technologies, you need to believe the build out of AI data center power, grid infrastructure and automotive electronics can increasingly fill its large new fabs and backend capacity. The analyst consensus Narrative on Simply Wall St leans on multi year AI power demand and capacity reservations to support revenue visibility. The recent SOLUM, Vertiv and Enphase updates point to tighter integration with key customers, but do not fundamentally change that story.
In the near term, the key swing factor remains how quickly AI and power infrastructure orders translate into higher utilization at projects like the €5b Smart Power Fab in Dresden and the new Bangkok backend hub. The biggest risk is that geopolitical friction, renewed customer destocking or ongoing weakness in high voltage drivetrains slows volumes, leaving fixed costs elevated and margins pressured while GaN restrictions in mainland China continue to cap part of the power portfolio.
The Vertiv three year agreement looks most relevant here because it directly connects Infineon Technologies to 800 VDC data center systems and broader critical power infrastructure. Vertiv is locking in silicon and silicon carbide supply and aligning product roadmaps with Infineon, which ties into the AI power capacity reservations highlighted in the analyst consensus Narrative on Simply Wall St. That relationship can help support visibility for data center related output from Dresden and other sites.
For you as an investor, this deal frames a clear execution test. Infineon now has to convert preferred supplier status on insulated gate bipolar transistors, silicon and silicon carbide devices into consistent high loadings across its expanded manufacturing base while keeping quality and delivery on track as Vertiv scales. Any production bottlenecks, delays in Vertiv deployments or broader weakening in data center and industrial spending could blunt what many see as a key factor for earnings progression over the next few years.
Infineon Technologies' current analyst narrative points to revenues of €25.3b and earnings of €5.3b by 2029, built on 17.5% yearly revenue growth and an increase in earnings of about €4.1b from €1.2b today.
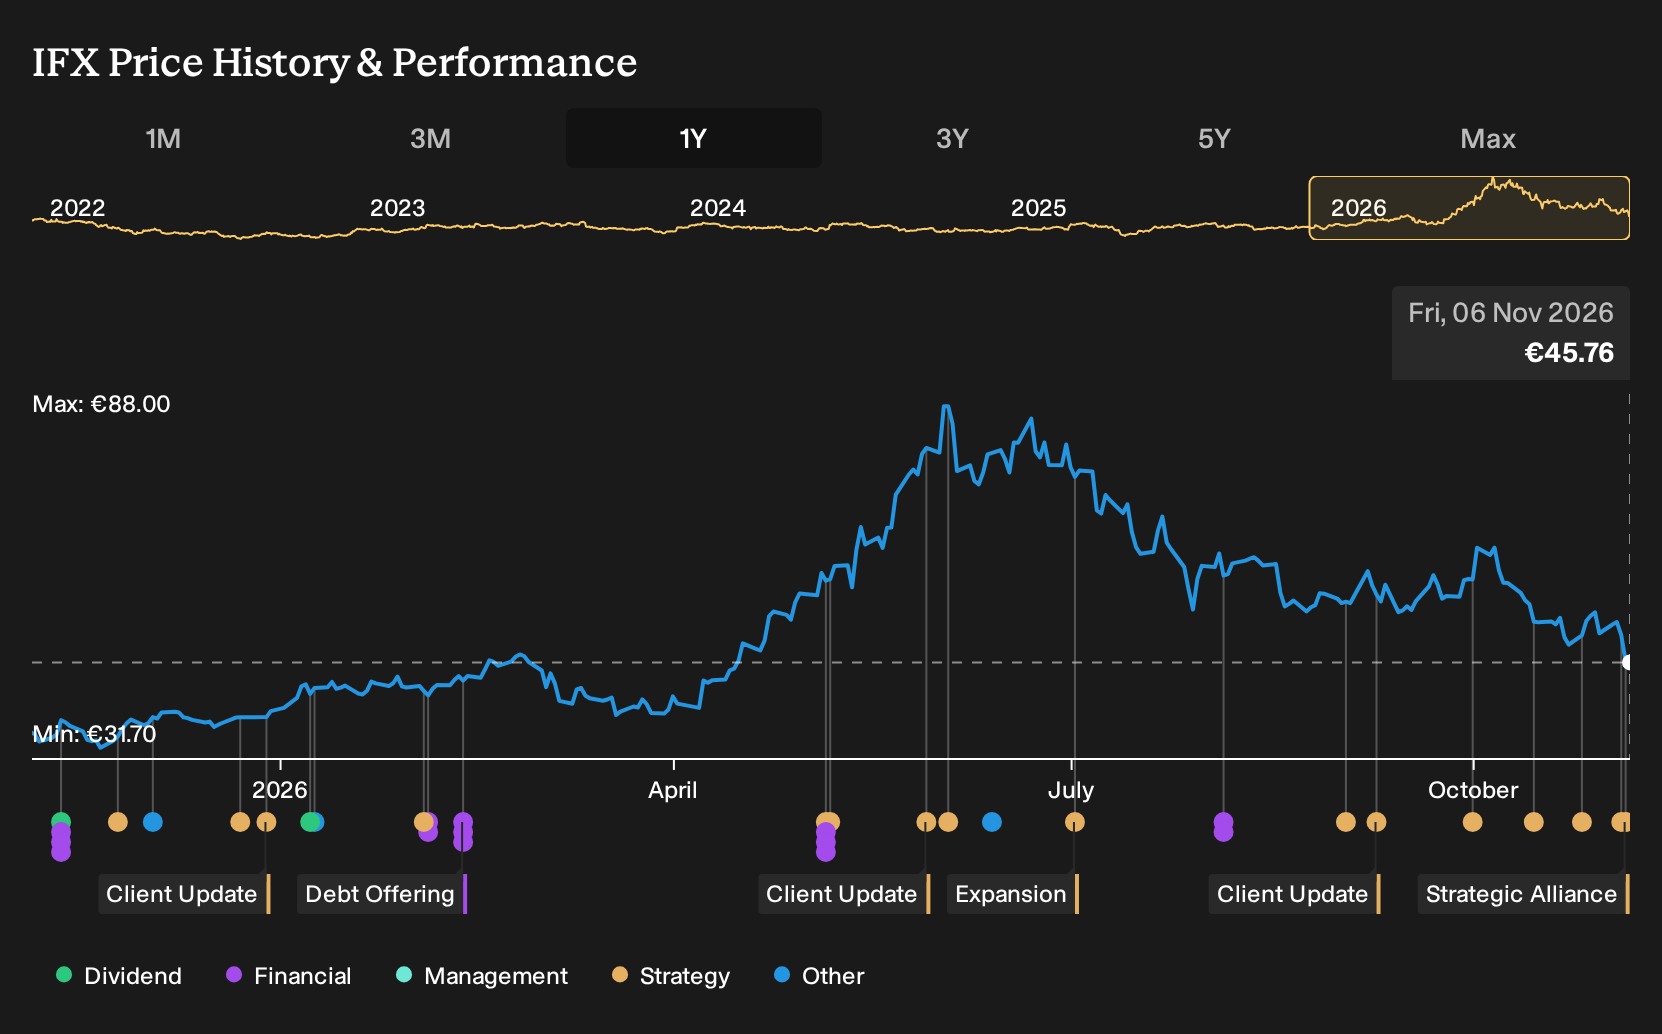
Uncover why Infineon Technologies' fair value indicates a 90% potential upside to its current price, a gap that could narrow quickly.
Exploring Other Perspectives
One alternate view on Infineon Technologies puts the AI concentration risk front and center. The most cautious analysts were pencilling in about €25.1b of revenue and €4.7b of earnings by 2029 before this Vertiv and SOLUM news, along with a much lower P/E of 19.5x. This reflects a far more restrained confidence in long term AI power demand. You can treat these contrasting expectations as a prompt to stress test your own thesis and explore how fresh collaboration headlines might shift both narratives from here.
Explore 3 other Infineon Technologies fair value estimates, including one that suggests it could be worth just €50.32.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Infineon Technologies research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Infineon Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Infineon Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Infineon Technologies?
If you want to balance your view on Infineon Technologies with fresh opportunities, broaden your watchlist using targeted stock lists built from the Simply Wall St Screener. These can help you pressure test your portfolio and spot different types of risk and return profiles.
- For investors who want potential upside with tight cost control and stronger finances, scan a curated 572 high quality undiscovered gems that might not yet be widely followed.
- If capital preservation and steadier profiles matter more to you than punchy gains, focus on companies screened as 207 resilient stocks with low risk scores to see which businesses currently flag fewer fundamental concerns.
- Income focused readers can centre their search on dependable cash distributions by reviewing a hand picked list of 226 dividend fortresses that pair high yields with more durable payout histories.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com