


EN
Elon Musk Predicts ‘Guppy-Level Death’ for Neoclouds. Here’s Why I’d Buy Nebius Over CoreWeave Before Q3 Earnings.
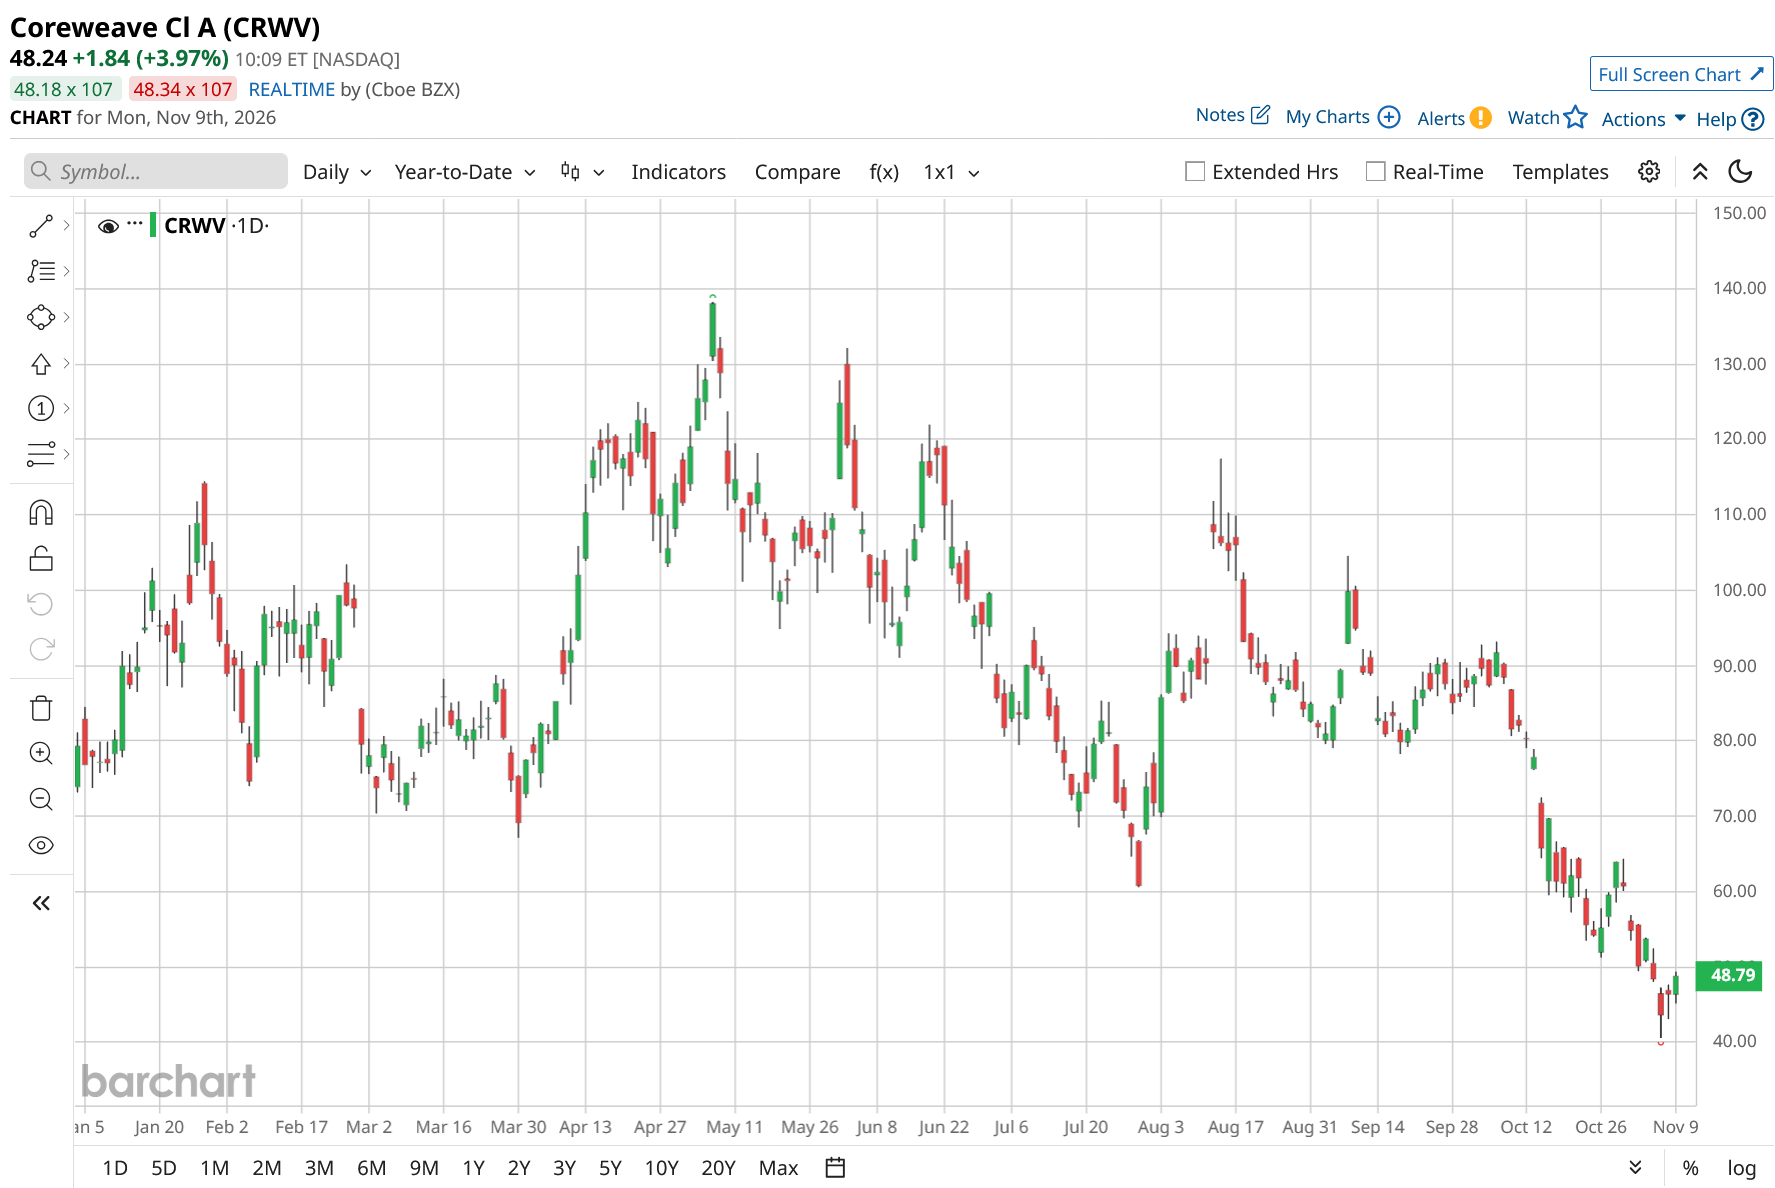
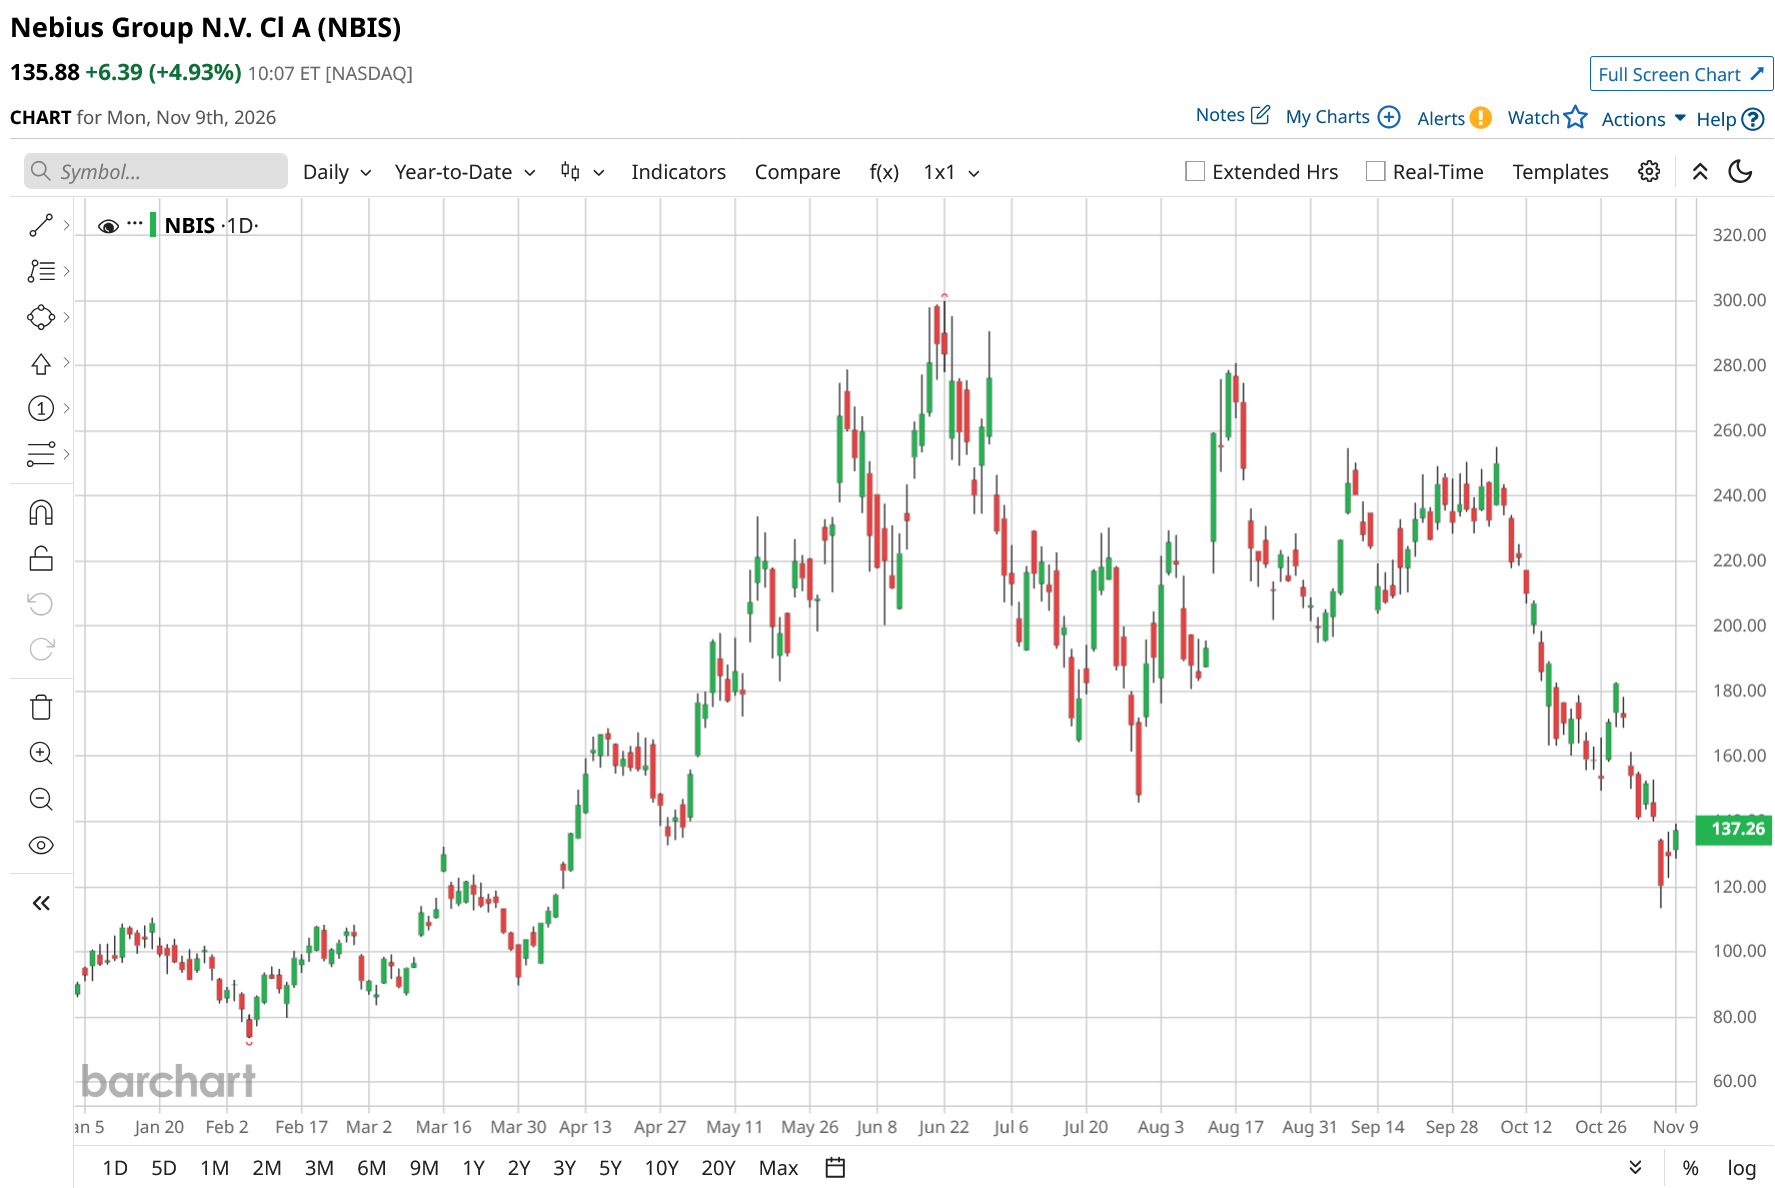
Neocloud stocks have had one of the worst runs in the past month. Investors' concerns about how these companies pay for their data centers grew further, since most of the money is borrowed, and borrowing has become more expensive. Musk's warning and the new Congress potentially slowing data center construction also added to the worries. During this period, CoreWeave (CRWV) crashed 43% and Nebius (NBIS) about 41%.
Musk's warning was basically a prediction he made in late October, where he said that there would be a “guppy-level death and consolidation” for the 200-plus neoclouds, meaning that most of them won't survive, according to him. Jensen Huang, on the other hand, said neocloud demand is “off the charts.” His company, Nvidia (NVDA), backs both CoreWeave and Nebius. CoreWeave reports on Nov. 10 and Nebius on Nov. 12. When I covered these two companies after the last earnings, I picked Nebius as the better stock. That’s how I still see it. But let's take a closer look at both again as their respective earnings Q3 reports approach.
About CoreWeave and Nebius Stock
CoreWeave and Nebius are both neoclouds, companies that rent out Nvidia-powered computing to businesses building and running AI models. CoreWeave is the bigger of the two by revenue, with Microsoft (MSFT) as its largest customer. Yet Nebius has grown quickly on deals with tech giants like Meta (META) and Microsoft. CoreWeave was founded in 2017 and is headquartered in Livingston, New Jersey. It's led by co-founder and CEO Michael Intrator. Nebius, on the other hand, took its current form in 2024 after separating from Yandex's Russian business. Based in Amsterdam, the company is led by founder and CEO Arkady Volozh.
The past month has been brutal for both stocks, far worse than for tech overall. CRWV stock has dropped 42% in the last month and is down 34% this year, leaving it close to its 52-week low of $43.10. In the last month, NBIS stock has fallen almost as hard, crashing 38%. But its strong run earlier in the year means it's still up 64% in 2026. At around $135, though, it sits well below its 52-week high of $299.86. For comparison, the Invesco QQQ Trust (QQQ) is down 10% over the past month, so the neocloud selloff has been roughly three times worse than the wider tech pullback.
Same Selloff, Very Different Balance Sheets
CoreWeave has kept borrowing heavily to buy Nvidia chips and build data centers, and it has now dug itself into a hole that doesn't look easy to get out of. It carries roughly $51.6 billion in total debt, including lease obligations, against $5.5 billion in cash. That's about twice the company's entire market value. CoreWeave's bonds pay a fixed interest rate of 9.625%. But investors have sold them off so heavily that anyone buying them now earns more than 16% a year. Lenders only demand that kind of return when they worry about getting their money back. CoreWeave expects to pay $860 million to $940 million in interest in the quarter it reports this week, roughly four times its expected adjusted operating income. That's why every rate increase hurts CoreWeave more than most. As I explained when the Fed raised rates, its whole model runs on borrowing, so each hike makes its next data center pricier to build.
Nebius carries about $10.2 billion in debt against $8 billion in cash, so the net debt is small for a company worth about $35.5 billion. The way Nebius funds growth is the main difference in my opinion. Much of its buildout is covered by customer prepayments, so it borrows less. It expects over $9 billion in prepayments this year. Management now aims for a $7 billion to $9 billion annual revenue run rate by year-end, up from $3 billion in June. So if Musk's shakeout happens, I think Nebius looks like the safer neocloud to own.
One thing to keep in mind is that CoreWeave, because of all its risks, is much cheaper to own right now. It currently trades at a forward sales of about 2x against Nebius' 10.6x. So if CoreWeave's report eases the debt fears a bit, its stock has the potential to bounce harder. But I think its interest costs will keep it deep in the red, and debt concerns will remain the main focus of the call.
What Do Analysts Expect for CRWV and NBIS Stocks?
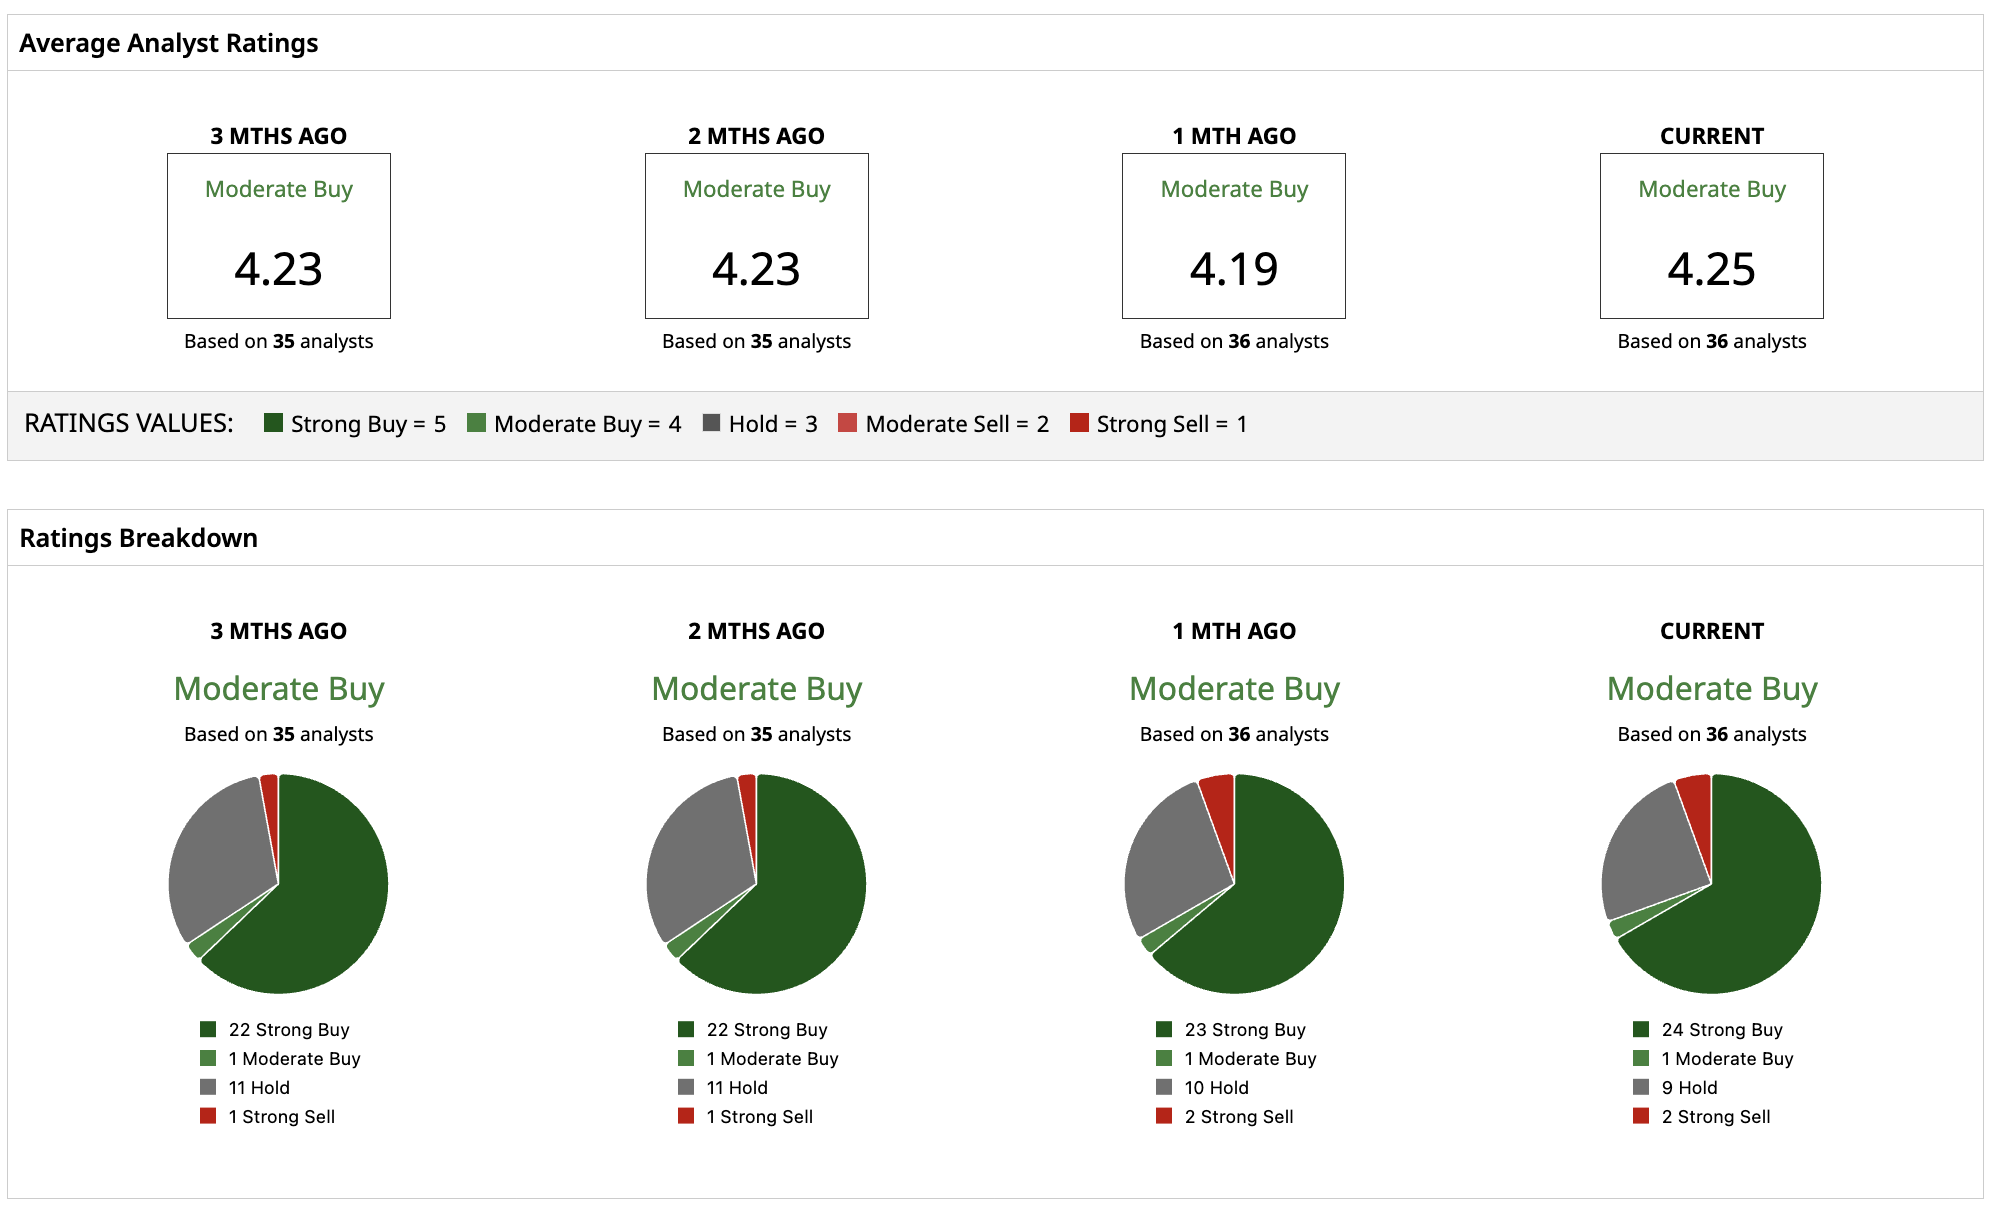
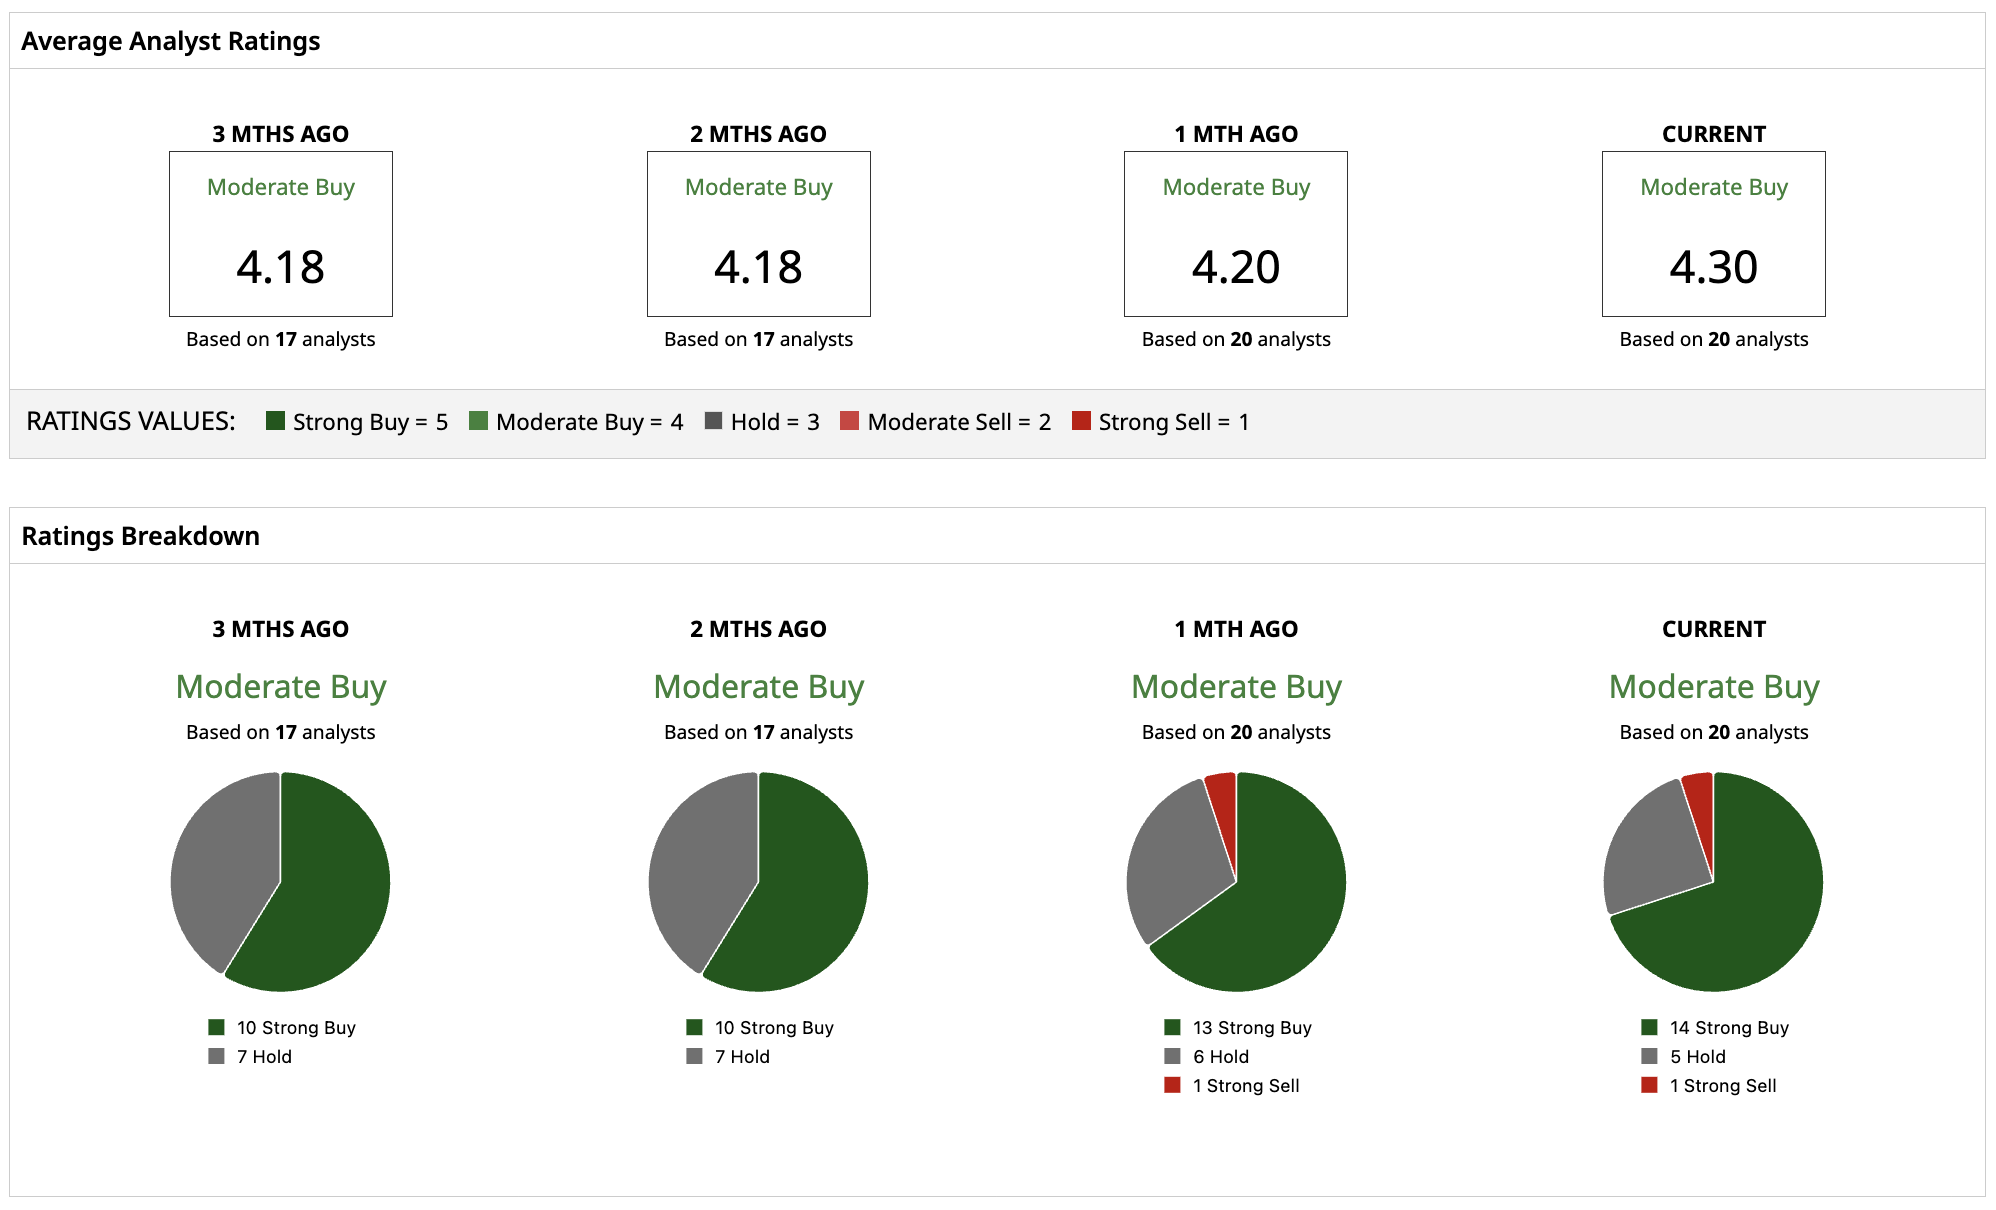
Based on 36 Wall Street analysts, CRWV holds a “Moderate Buy” rating. The stock has dropped so far that its mean price target of $126.40 now indicates a massive 162% upside. Its highest price target is $250, while the lowest price target of $39 isn’t too far below the current share price. The estimates for NBIS stock look quite encouraging too. Based on 20 analysts, it also holds a “Moderate Buy” rating. Its mean price target of $285.19 indicates a 110% upside. This shows that analysts believe both stocks have plenty of room to run.
On the date of publication, Jabran Kundi did not directly have a position in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.