


EN
Ligand Pharmaceuticals (LGND) Could Be 11% Below Fair Value Following Earnings Shock
Earnings Shock Puts Ligand Pharmaceuticals Under The Microscope
Ligand Pharmaceuticals (LGND) posted a third quarter revenue decline to US$78.75 million and reported a US$28.49 million net loss, while management reaffirmed full year sales guidance.
The latest results land after a powerful run in Ligand Pharmaceuticals’ shares, with a year-to-date share price return of 61.1% and a 1-year total shareholder return of 46.3%. The 3-year total shareholder return is roughly 4.5x, and recent single-day and 30-day share price gains suggest momentum has cooled but not reversed.
Balance that earnings shock at Ligand Pharmaceuticals by evaluating it alongside hand picked biopharma peers using the 19 high quality undiscovered gems filter.
The earnings setback at Ligand Pharmaceuticals clashes with a multi year share price surge, creating a clear tension. Is the recent move still tethered to business fundamentals, or is it drifting on changing sentiment as valuation comes into focus?
Most Popular Narrative: 11% Undervalued
The analyst consensus Narrative on Simply Wall St places Ligand Pharmaceuticals’ fair value at $344.25, compared with a last close of $306.20. This frames the current earnings setback against a longer term royalty growth story built on detailed forecasts and a 7.24% discount rate.
Expansion of Ligand Pharmaceuticals’ high margin royalty portfolio through the completed XOMA Royalty acquisition, which adds more than 120 assets including additional commercial products and late stage programs, is expected to widen the base of recurring royalty revenue and support higher earnings power as the assets mature.
See why 5 investors see Ligand Pharmaceuticals as 11% undervalued.
Result: Fair Value of $344.25 (UNDERVALUED)
Still, Ligand Pharmaceuticals depends heavily on a handful of royalty drivers. As a result, any pricing pushback or regulatory delay on a key partnered drug could quickly weaken that narrative.
Find out about the key risks to this Ligand Pharmaceuticals narrative.
Another View: What Multiples Say About Ligand Pharmaceuticals
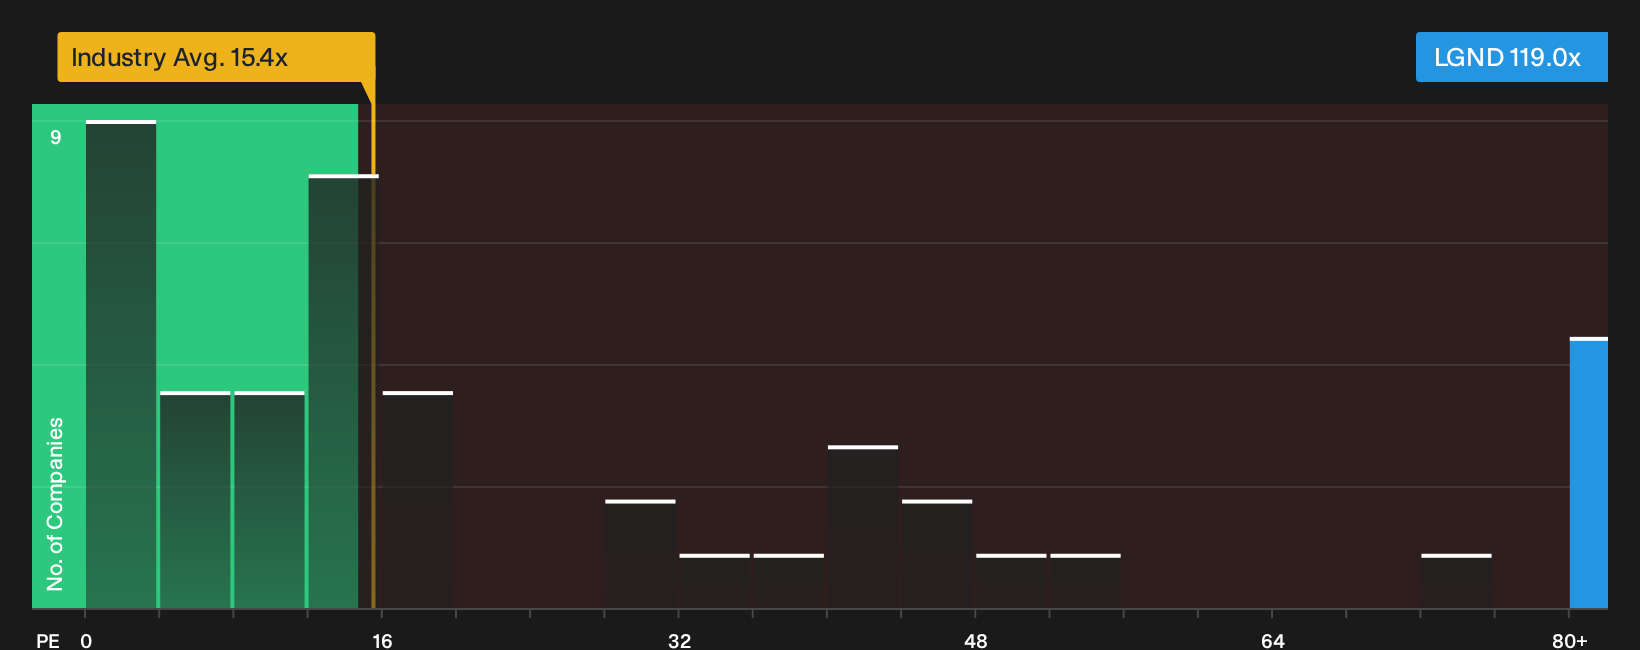
The first narrative leans on analyst fair value and future royalty growth. A different lens, the current P/E, paints a sharper picture. Ligand Pharmaceuticals trades at 119x earnings, while the US Pharmaceuticals industry sits at 15.4x and peers average 29.9x, with a fair ratio of 33.1x.
That gap implies investors are paying a heavy premium relative to both sector and fair ratio, which raises a practical question. If sentiment cools or forecasts are revised, does the price compress toward that 33.1x area or do earnings catch up sufficiently to justify the current multiple?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment around Ligand Pharmaceuticals feels conflicted after this report, consider reviewing the underlying metrics yourself. The best way to balance the concerns and potential upside that other investors are focused on is to weigh the 3 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Ligand Pharmaceuticals?
Do not let your research stall at Ligand Pharmaceuticals. Broaden your watchlist with a few targeted idea lists that other investors are already using.
- Target resilient balance sheets and steady fundamentals by scanning companies in the list of solid balance sheet and fundamentals (25 results).
- Hunt for quality businesses trading below their estimated worth with the 40 high quality undervalued stocks.
- Aim for stability with potential downside protection by reviewing companies flagged in the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com