


EN
Murphy Oil (MUR) Raised Guidance And Added Offshore Deals, Is 14% Undervalued?
Why Murphy Oil Is Back in Focus After Earnings and Offshore Deals
Murphy Oil (MUR) just reported a busy third quarter, combining higher reported earnings with raised 2026 production guidance and new offshore contracts in Mauritania that expand its international exploration footprint.
Murphy Oil’s share price has slipped recently, with a 7 day share price return of down 10.46% and a 30 day move of down 7.03%, even though the year to date share price return is up 10.68% and the 1 year total shareholder return sits at 30.05%. This suggests that longer term momentum has held up better than the latest pullback that followed the earnings beat, higher 2026 production guidance and the new offshore positions in Mauritania.
Scan how Murphy Oil compares with other producers reacting to the same earnings and offshore themes by checking our hand picked 40 high quality undervalued stocks in the sector.
The pullback in Murphy Oil after stronger earnings and fresh offshore commitments forces a simple choice. Are investors reassessing the business itself, or just resetting sentiment around what they are willing to pay?
Most Popular Narrative: 14% Undervalued
Murphy Oil last closed at $35.96, while the analyst consensus Narrative on Simply Wall St points to a fair value of $41.93 based on a 7.24% discount rate and long run earnings and revenue forecasts that already factor in its offshore and onshore plans.
Ongoing exploration and appraisal activity across Murphy Oil’s key offshore areas, including the Bubale discovery in Côte d'Ivoire and continued work in Vietnam and the Gulf of America, is intended to convert current spending into additional booked reserves and higher future production. This in turn would support revenue growth and potential earnings expansion.
See why 15 investors see Murphy Oil as 14% undervalued.
Result: Fair Value of $41.93 (UNDERVALUED)
Still, the higher 2026 capex plan and rising Bubale appraisal costs leave Murphy Oil exposed if those wells disappoint or if free cash flow comes in softer than hoped.
Find out about the key risks to this Murphy Oil narrative.
Another View: Murphy Oil On Earnings Multiples
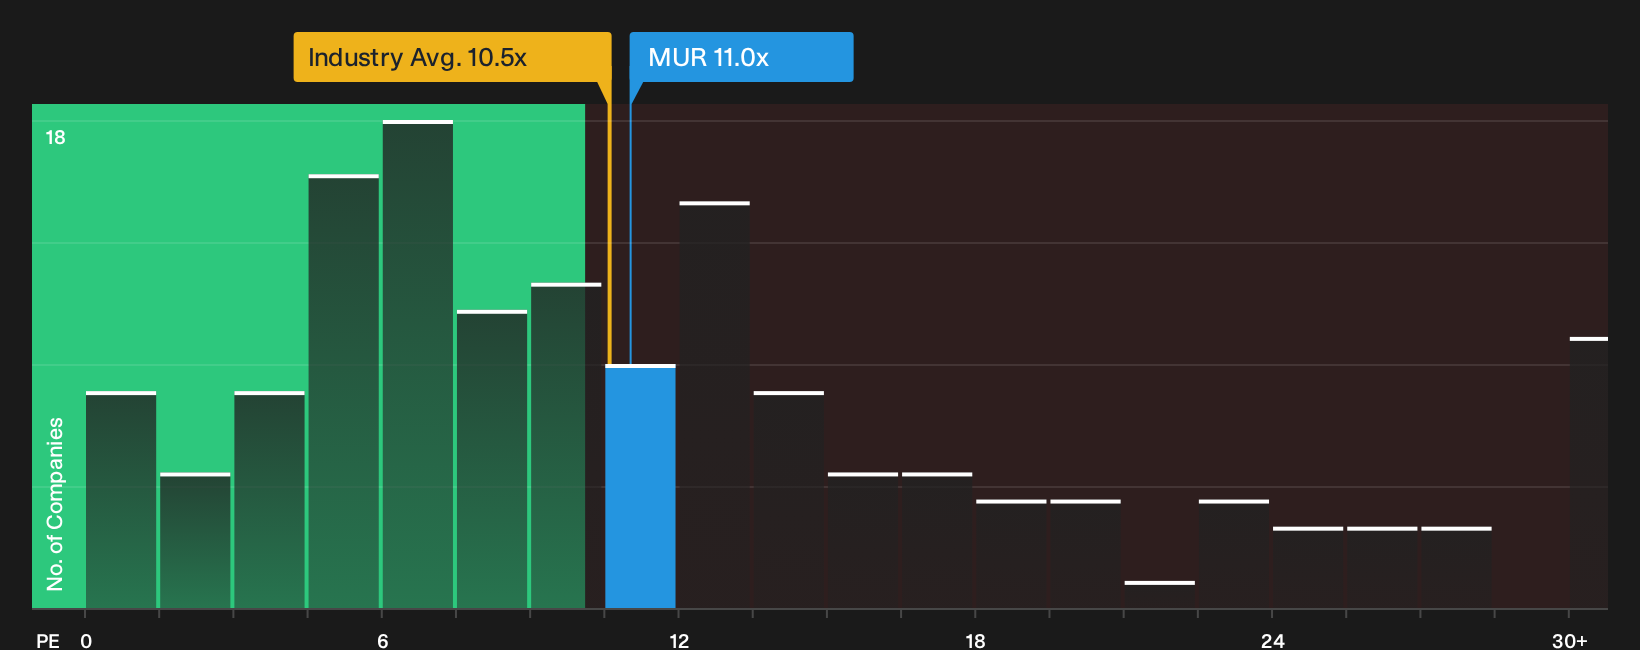
Murphy Oil screens differently when priced off earnings. The stock trades on an 11x P/E, which is slightly higher than both the US Oil and Gas sector at 10.5x and its peer group at 10.9x, even though the estimated fair ratio sits higher at 13.7x. That mix of mild premium today and room to move toward the fair ratio raises a simple question for investors: Is this a reasonable entry point, or does it leave less margin for error if the offshore spend does not fully pay off?
For readers weighing that earnings based view against the analyst narrative and fair value, it helps to see how the raw numbers stack up in a simple valuation breakdown. This includes how the current P/E compares to the fair ratio and sector levels, before deciding which story feels more convincing in light of Murphy Oil’s offshore and onshore plans. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Murphy Oil so far. If you want to move quickly and build your own take on the risk and reward balance, start with the 3 key rewards and 2 important warning signs.
Looking for more Murphy Oil style investment ideas?
Do not stop with Murphy Oil. Broaden your watchlist with fresh ideas sourced from data driven screeners that surface stocks you might otherwise never consider.
- Target potential bargains that combine quality with a discount by running the 40 high quality undervalued stocks and comparing them to Murphy Oil’s current setup.
- Prioritize balance sheet strength and financial resilience by filtering through the list of solid balance sheet and fundamentals (25 results) to spot companies that may better handle tough cycles.
- Hunt for lesser known opportunities with strong fundamentals by scanning the 19 high quality undiscovered gems before other investors start paying attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com