


EN
How Investors May Respond To IDEXX Laboratories (IDXX) Raised Full Year Guidance
- IDEXX Laboratories reported third quarter 2026 revenue of US$1,214.24 million and net income of US$317.15 million, with higher basic and diluted EPS from continuing operations compared with the prior year period.
- Management also raised full year 2026 guidance for revenue and reported EPS, while slightly trimming the operating margin outlook, highlighting both demand strength and ongoing investment needs.
- We will look at how IDEXX Laboratories' raised full year EPS guidance intersects with the existing recurring diagnostics driven investment narrative.
Scan for other recurring revenue stories like IDEXX Laboratories by running the same playbook on our curated list of 40 high quality undervalued stocks.
IDEXX Laboratories Investment Narrative Recap
IDEXX Laboratories appeals to shareholders who buy into a recurring diagnostics story, where more tests per visit and a growing instrument base support earnings over time. The raised 2026 revenue and EPS guidance aligns with that thesis. The slight trim to operating margin expectations keeps attention on cost discipline as spending ramps in sales and R&D.
The near term catalyst remains execution in companion animal diagnostics, particularly consumables pull through on platforms like inVue Dx and Catalyst, as described in the analyst consensus Narrative on Simply Wall St. The main risk stays the same. Softer U.S. wellness visits and higher operating expenses could limit near term earnings leverage despite stronger guidance.
The most relevant update is the revised full year 2026 outlook. Management now guides revenue to US$4,741 million to US$4,767 million, with reported EPS of US$14.96 to US$15.16. Reported revenue growth guidance moves to a range of 10.1% to 10.8%, while the operating margin range nudges to 32.1% to 32.3% from a slightly higher prior band.
For you as an investor, this sets a clearer bar for near term execution in IDEXX Laboratories. Stronger top line and EPS targets lean into the recurring diagnostics and software catalyst. The marginally lower margin outlook highlights the risk that heavier investment in international expansion and AI or IT projects may take time to translate into higher recurring revenue density per clinic.
IDEXX Laboratories' narrative projects US$6.0b revenue and US$1.6b earnings by 2029. This implies 9.0% yearly revenue growth and an earnings increase of about US$400m from US$1.2b today.
Uncover why IDEXX Laboratories' fair value indicates a 6% potential upside to its current price that could narrow quickly.
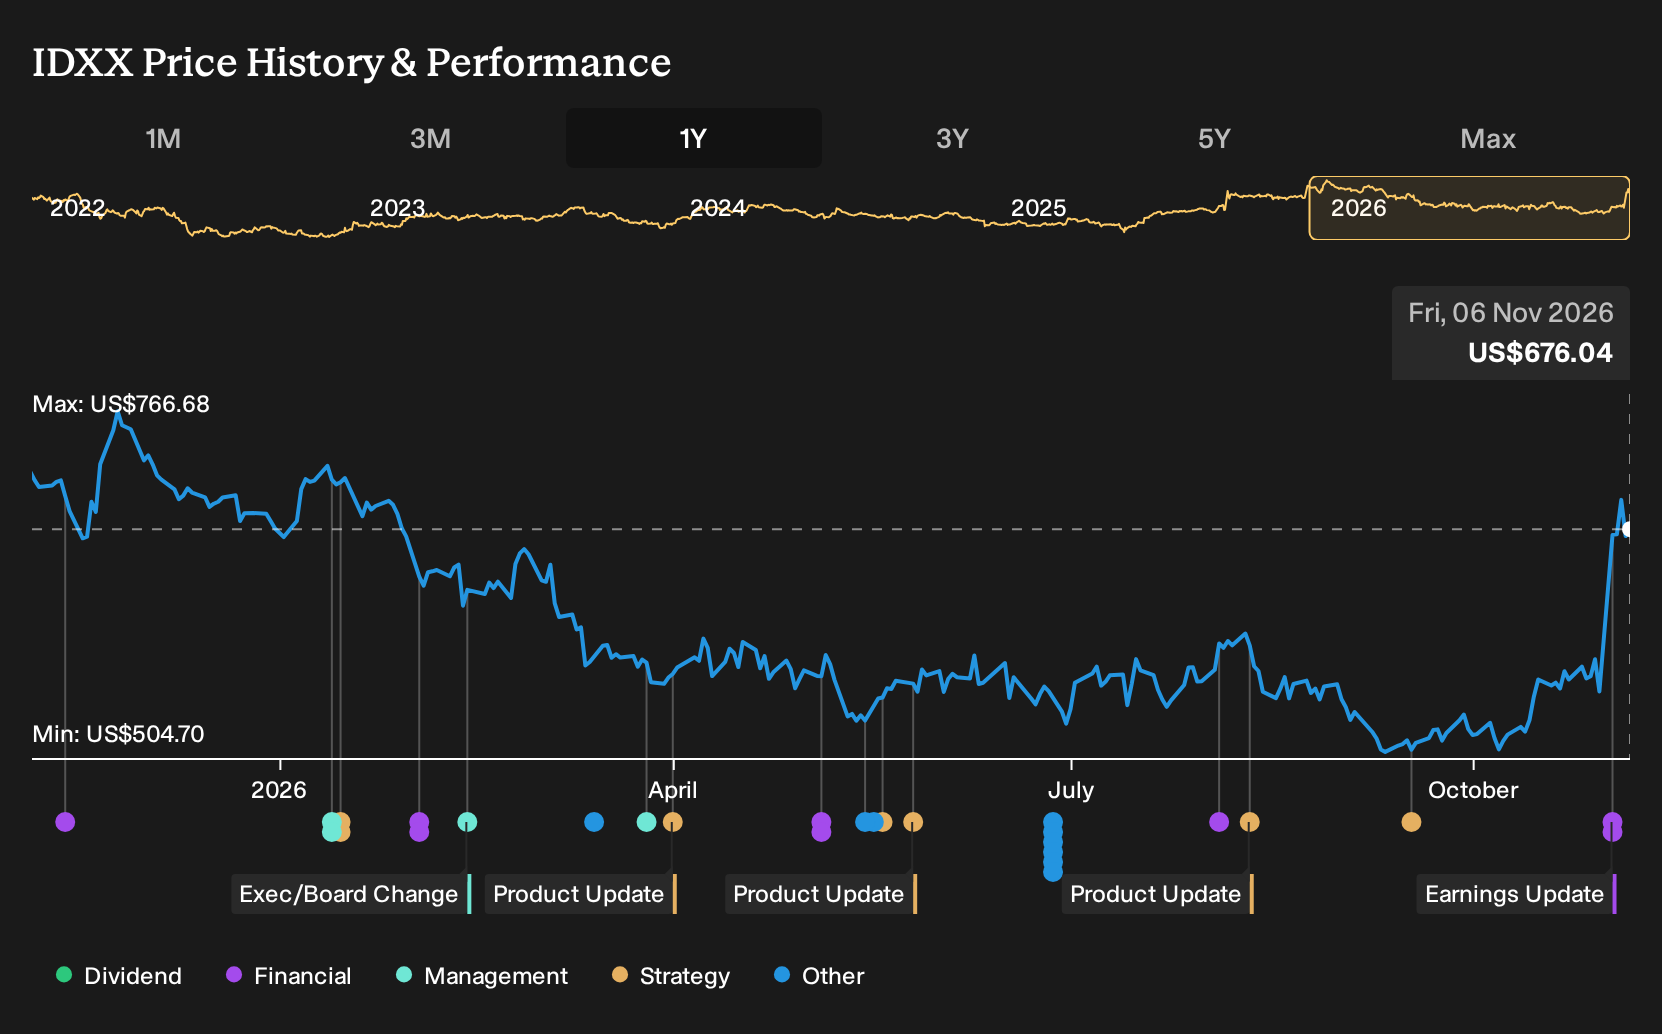
Exploring Other Perspectives
One alternate view on IDEXX Laboratories focuses on weaker pricing power in newer diagnostics. The most bearish analysts were working off revenue of about US$5.9b and earnings near US$1.5b by 2029, which is below the consensus path. Those forecasts came before this guidance lift, so opinions may shift as fresh data lands.
Explore 6 other IDEXX Laboratories fair value estimates, including one that suggests as much as 50% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your IDEXX Laboratories research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for IDEXX Laboratories. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate IDEXX Laboratories' overall financial health at a glance.
Looking For More Investment Ideas Beyond IDEXX Laboratories?
If the IDEXX Laboratories story has sharpened your thinking about recurring revenue and quality fundamentals, you can use that same lens across a wider watchlist. The Simply Wall St Screener lets you apply consistent rules so you compare like for like rather than chasing headlines.
- If you prefer companies that combine quality with attractive pricing and want a starting pool of candidates that already clear some fundamental bars, scan through 40 high quality undervalued stocks that may fit that brief.
- If capital preservation and steadier risk profiles sit higher on your list, focus your search on 31 resilient stocks with low risk scores that could help anchor a more defensive portfolio.
- For readers who care most about balance sheet strength and want fewer surprises from leverage or weak liquidity, sort through the list of solid balance sheet and fundamentals (25 results) to see which businesses make the cut.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com