


EN
Estée Lauder Companies (EL) Raises 2027 Guidance Following Recovery Plan Progress, With Fair Value In Focus
Estée Lauder Companies (EL) has put a clearer marker down for investors, raising fiscal 2027 sales and earnings guidance while reaffirming its dividend and detailing new product and AI-focused technology initiatives.
Recent moves in Estée Lauder Companies’ share price suggest momentum is picking up, with a 1 month share price return of 12.25% and a 90 day gain of 25.38% at a latest share price of US$110.06, supported by stronger quarterly earnings, raised fiscal 2027 guidance and new AI and skincare platforms.
Scan how Estée Lauder Companies compares with other beauty and consumer stocks that are showing fresh momentum and fundamentals support by using our curated list of 40 high quality undervalued stocks.
Bulls point to Estée Lauder Companies’ earnings reset, higher guidance and AI push. Bears focus on past share price damage and execution risk. Do the recent numbers and valuation now lean more toward recovery or caution?
Most Popular Narrative: 3% Undervalued
On the analyst consensus Narrative on Simply Wall St, Estée Lauder Companies carries a fair value estimate of $113.98 versus a last close of $110.06. This frames the current rally as modestly below that narrative fair value while keeping attention firmly on execution risk and earnings quality.
The current valuation implies that the share price does not fully reflect the view that Estée Lauder Companies may be undervalued and in the early stages of a margin and cash flow recovery.
The main thing that has to go right is that the Profit Recovery and Growth Plan and related restructuring continue to translate cost reductions and AI-enabled execution into durable margin expansion without damaging brand equity.
See why 105 investors see Estée Lauder Companies as 3% undervalued.
Result: Fair Value of $113.98 (UNDERVALUED)
Still, Estée Lauder Companies faces execution risk from its multi year restructuring and workforce reductions, along with a governance overhang from the ongoing external investigation.
Find out about the key risks to this Estée Lauder Companies narrative.
Another View: Estée Lauder Companies Looks Expensive On Earnings
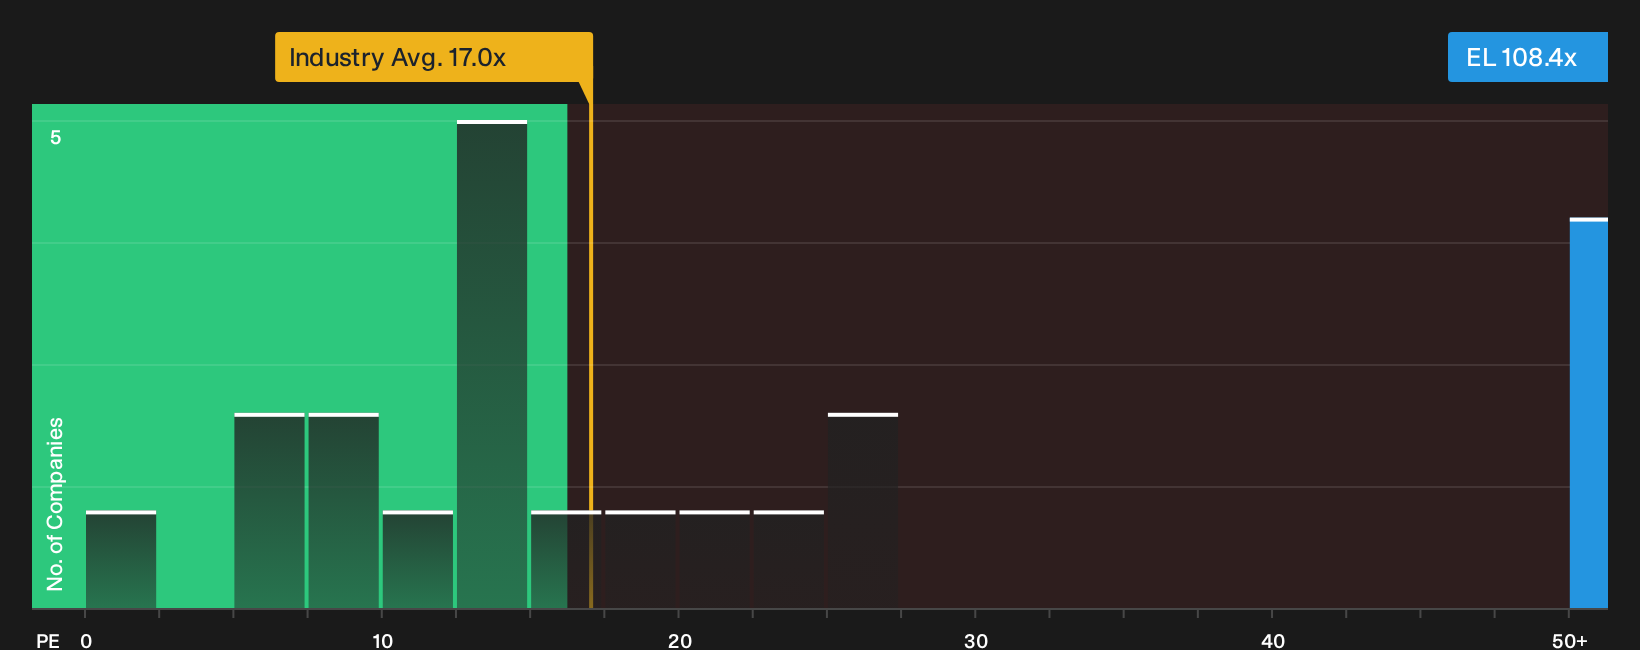
On a simple earnings yardstick, Estée Lauder Companies looks stretched. The stock trades on a P/E of 108.4x compared with 17x for the global personal products group and a fair ratio of 32.8x. That gap points to valuation risk rather than a clear bargain if sentiment cools.
Investors weighing that premium against the recovery story may want to see what the numbers imply in more detail, especially if earnings expectations ever reset closer to peers. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages so far on Estée Lauder Companies, which is exactly why you should move quickly and weigh the evidence yourself. Balance the potential upside and the open questions by reviewing the 2 key rewards and 2 important warning signs.
Looking for more Estée Lauder Companies sized opportunities?
If you are serious about building a stronger portfolio, do not stop with Estée Lauder Companies. Put fresh ideas on your radar using the Simply Wall St Screener before others move first.
- Spot potential turnarounds early by checking companies that look overlooked on quality and valuation using the 19 high quality undiscovered gems.
- Strengthen your income stream by hunting for reliable cash payouts through the 7 dividend fortresses.
- Dial down portfolio risk by focusing on businesses with healthier finances through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com