


EN
Does Mixed Earnings Growth Change The Bull Case For Fraport Stock (XTRA:FRA)?
- Fraport reported third quarter 2026 sales of €1,396.9 million and revenue of €1,443.9 million, with net income of €221.5 million and basic earnings per share of €2.39, while nine-month 2026 net income reached €272.8 million on revenue of €3,572.5 million.
- The figures show top line growth alongside lower net income and earnings per share compared with the prior year, which points to pressure from costs, financing or non operating items that could matter for how Fraport balances expansion projects with profitability.
- We will now look at how Fraport's mixed revenue growth and weaker earnings shape the investment narrative that investors have been using.
Fraport Investment Narrative Recap
To own Fraport, you need to be comfortable with a story where heavy airport investments and interest costs sit in front of the earnings profile you care about. The latest quarter fits that picture. Revenue moved up, yet net income and earnings per share were lower than a year ago, which keeps the focus on cost discipline and capital intensity rather than pure traffic growth.
The analyst consensus Narrative on Simply Wall St still leans on earnings forecast growth of 16.55% a year and eventual margin improvement. The recent results, with nine month profit at €272.8 million versus higher levels last year, nudge the near term risk skew toward pressures from depreciation, financing costs and any further cost inflation rather than new upside catalysts.
The most relevant update is the third quarter and nine month 2026 earnings announcement itself. Fraport posted third quarter revenue of €1,443.9 million and net income of €221.5 million, with basic earnings per share of €2.39. For the first nine months, revenue reached €3,572.5 million and net income came in at €272.8 million, with earnings per share of €2.95.
Those figures matter because the existing catalysts in that analyst consensus Narrative on Simply Wall St, such as forecast profit growth and expectations of better margins over time, now sit against a year on year drop in earnings despite higher sales. For you as a shareholder, the operational question is whether Fraport can translate upcoming capacity projects into better net income without letting interest, depreciation and staff expenses dominate the income statement.
Fraport's current earnings of €388.2 million are set against consensus forecasts of €485.1 million by 2029. This implies revenue of €5.1 billion by that same year, built on assumed annual revenue growth of 4.2% and an earnings increase of about €96.9 million from today.
Discover how Fraport's fair value indicates a 7% potential upside to its current price that may not last much longer.
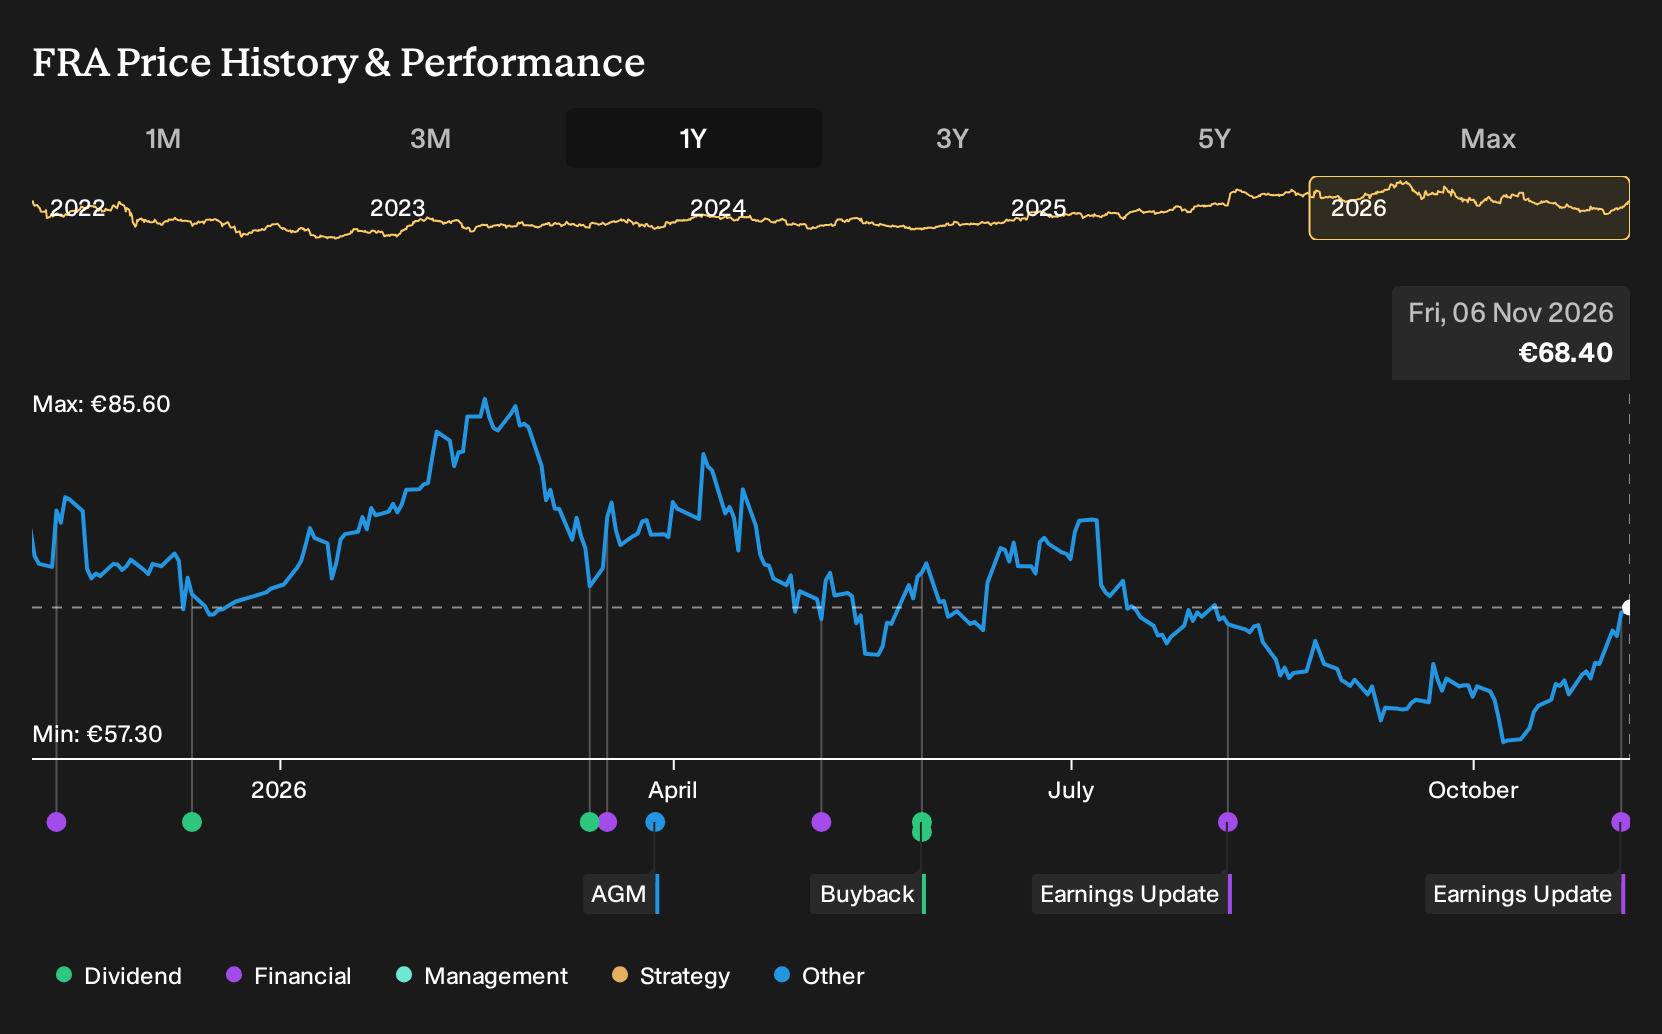
Exploring Other Perspectives
One upbeat angle in the alternate Fraport story is the expected ramp in earnings toward about €514.6 million by 2029 on roughly 6.0% annual revenue growth, even though this latest quarterly report showed profit pressure. The most optimistic analysts were already baking in richer P/E multiples, so this new earnings hit may prompt sharp narrative rewrites.
Explore another Fraport fair value estimate, including one that suggests as much as 94% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Fraport research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fraport. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fraport's overall financial health at a glance.
Looking for more Fraport investment ideas?
If the latest Fraport numbers sharpened your focus on quality, income, or resilience, it can help to widen the lens and compare this stock with others that already fit clear financial profiles. The Simply Wall St Screener lets you filter for traits that actually match how you like to invest, rather than forcing your approach to fit a single company.
- For investors who want strong fundamentals without paying up for hype, scan a 572 high quality undiscovered gems that combine solid balance sheets with earnings support.
- If stability matters most to you, narrow in on companies that score well on risk with a 207 resilient stocks with low risk scores and see which businesses already show more resilient profiles.
- Income focused readers can keep Fraport on the watchlist while also checking a 225 dividend fortresses that pairs higher yields with balance sheets built to support regular payouts.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com