


EN
Quaker Chemical (KWR) Returned To Profit, Is The Rebound Already Priced In?
Quaker Chemical earnings spark fresh interest
Quaker Chemical (KWR) drew investor attention after reporting third quarter 2026 results with higher sales and a sharp swing to profit for the nine month period compared with last year.
The update also arrived alongside confirmation that the company completed a previously announced share repurchase plan, adding a capital return angle to the latest earnings story.
Quaker Chemical shares now trade at $150.02, with the stock up 7.96% on a year to date share price basis but showing a 3 year total shareholder return that is down 5.72% and a 5 year total shareholder return that is down 41.48%. This points to improving short term momentum off a weaker long term record.
Scan how Quaker Chemical compares with other quality industrials reporting earnings turnarounds by reviewing our curated list of 40 high quality undervalued stocks.
Quaker Chemical now trades below the average analyst target after a sharp rebound, while its own fair value gauge signals a slight premium. Is the discount a genuine mispricing, or just measured caution on recent progress?
Most Popular Narrative: 22% Undervalued
Quaker Chemical’s analyst consensus Narrative on Simply Wall St puts fair value at $192.57, above the latest $150.02 close. This frames the recent earnings rebound against a longer term view that leans on cost savings and Asia Pacific execution under a 7.8% discount rate.
The main factor that needs to go right is successful execution of the multi year cost and business transformation program that targets at least $20 million to $30 million of structural savings and sustainably higher EBITDA margins.
The current valuation implies the share price already reflects some benefit from above market volume growth and margin progress, while still leaving room for further upside if Quaker Chemical delivers on its cost savings and Asia Pacific growth plans.
See why 8 investors see Quaker Chemical as 22% undervalued.
Result: Fair Value of $192.57 (UNDERVALUED)
Still, the Quaker Chemical story can break if Asia Pacific share gains slow, or if the multi year cost program delivers savings at the low end of expectations.
Find out about the key risks to this Quaker Chemical narrative.
Another View: Quaker Chemical Through The P/E Lens
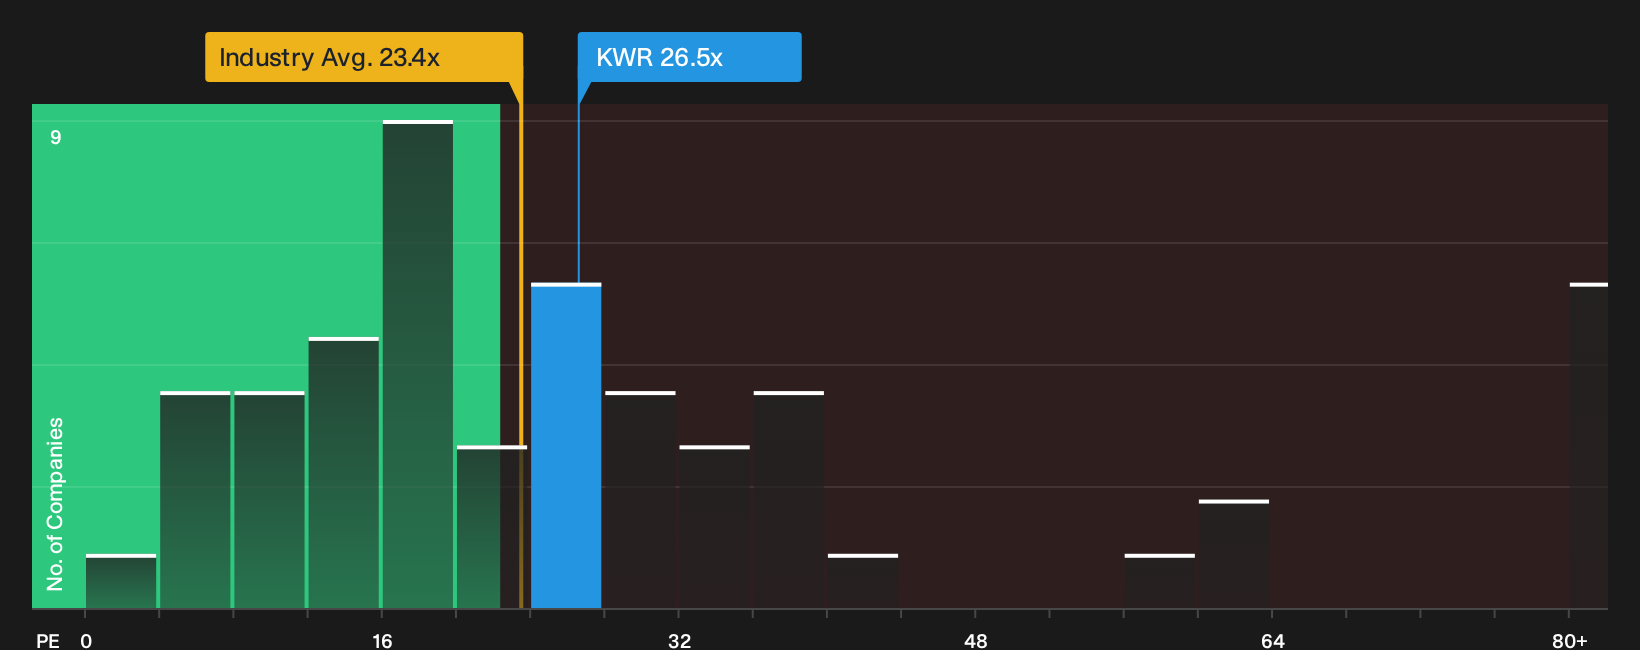
The first fair value narrative paints Quaker Chemical as 22% undervalued, yet the current P/E of 26.5x tells a tougher story. That multiple sits above both the US Chemicals industry at 23.4x and the fair ratio of 22x, which implies less cushion if expectations slip from here.
Put simply, the stock trades richer than the sector and above where the fair ratio suggests the market could settle, so any stumble on earnings or margins might have an outsized effect on the share price. Does that premium reflect confidence in Quaker Chemical’s rebound, or are expectations already running a little hot?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Quaker Chemical so far, right? If you want to move quickly and ground your view in the full picture, weigh up the 3 key rewards and 3 important warning signs.
Looking for more Quaker Chemical investment ideas?
If Quaker Chemical has sharpened your focus, now is the moment to widen your watchlist with other opportunities instead of waiting for the next headline.
- Target resilient income by reviewing companies that feature 7 dividend fortresses for investors who want yield with a focus on durability.
- Hunt for mispriced quality by scanning a curated 19 high quality undiscovered gems that many investors may not be watching yet.
- Dial down portfolio stress by filtering for 31 resilient stocks with low risk scores that prioritize sturdier balance sheets and steadier business profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com