


EN
Bank of America Is Doubling Down on Apple While Tech Sells Off. Here's Its Price Target
Bank of America (NYSE:BAC) analyst Wamsi Mohan is maintaining a buy rating on Apple (NASDAQ:AAPL) at a time when memory costs and a volatile tech market are testing investors’ patience.
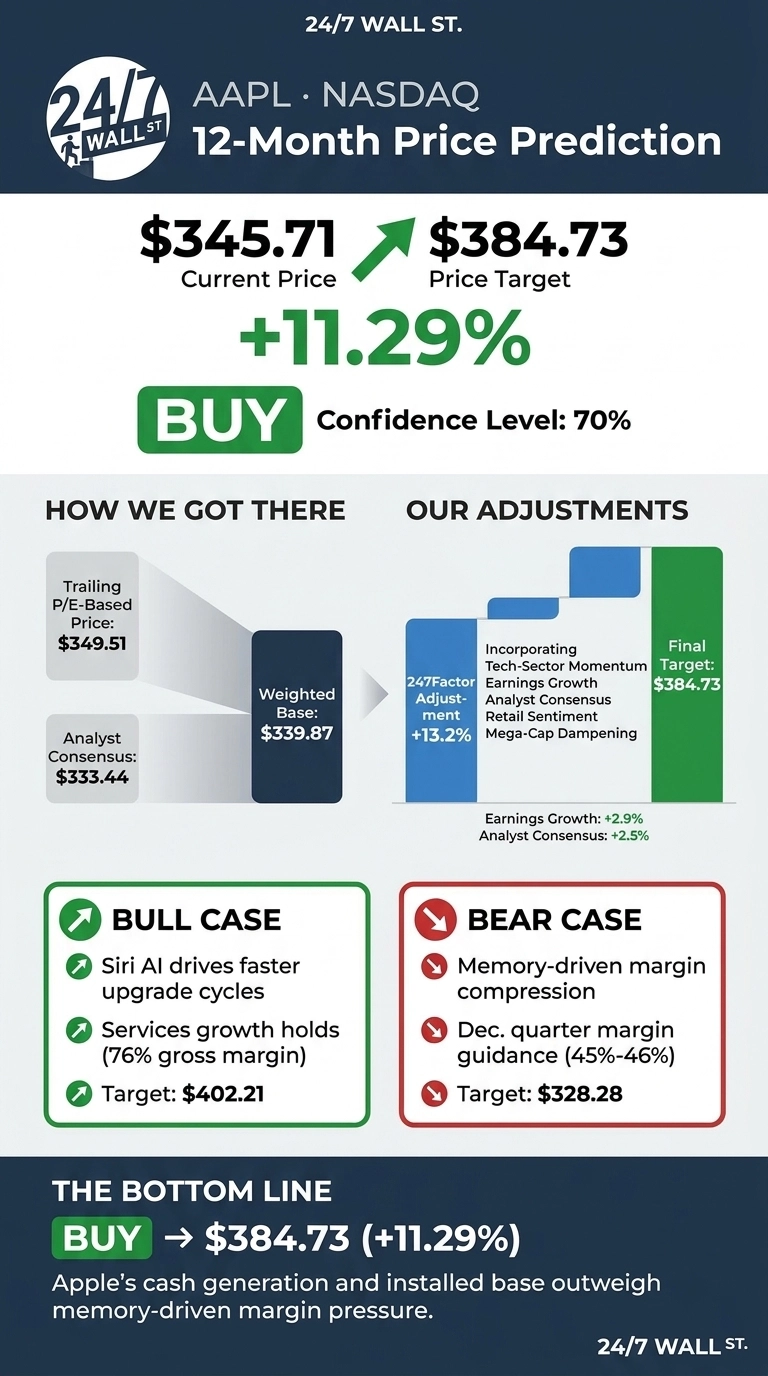
Our model is also bullish. Apple’s 24/7 Wall St. price target is $384.73. That means 11.29% upside from where shares trade at $345.71.
24/7 Wall St. Price Target Summary Metric Value Current Price $345.71 Price Target from 24/7 Wall St. $384.73 Upside 11.29% Recommendation BUY Confidence Level 70%A 70% confidence score means I have moderately high conviction. Apple just finished its best fiscal year ever, and management expects the December quarter to be the best quarter for revenue in the history of the company.
The main pressure on the target comes from memory-driven margin compression. My view is that Apple’s cash generation and the size of its installed base outweigh that drag over the next 12 months.
 24/7 Wall St. A Record Quarter Collided With a Memory Shock
Over the past week Apple fell 1.36%. It is up 3.16% over the past month and 26.95% year to date. Shares sit 2.48% below the 52-week high of $354.50 and 42.41% above the low of $242.76.
Fiscal Q4 revenue came in at $114.48 billion (+11.7% YoY), ahead of the $113.36 billion estimate. EPS of $2.10 beat expectations of $1.98, although that figure includes a $0.05 one-time benefit from tariff refunds. Even so, the stock sank as the global memory crisis hurt profits. It then surged alongside hyperscalers after election results removed uncertainty.
Why Bulls See $402 Within ReachiPhone revenue reached $57.58 billion. The new iPhone Duo is supply constrained, and the chief executive calls it “the most transformational iPhone since the original.” Services brought in $31.57 billion at a 76% gross margin.
Greater China grew 21%. Apple also bought back $24 billion of its own stock in the quarter. Management guided December-quarter revenue growth to between 7% and 10%. If Siri AI drives faster upgrade cycles, our bull case points to $402.21.
Memory Inflation Could Squeeze MarginsGross margin was 47.9% in the September quarter, and Apple guided it down to between 45% and 46% for December. The chief executive described memory pricing as “unprecedented.”
Operating expenses rose 21%, and inventories climbed to $14.54 billion from $5.72 billion. Building inventory protects supply during the holiday quarter, and the jump in R&D to $11.73 billion funds AI features that could drive future upgrades. Still, the consensus analyst target sits below where the stock trades. Our bear case is $328.28.
Apple Trades at a Premium to Microsoft and AlphabetMicrosoft (NASDAQ:MSFT) is the closest mega-cap comparison on quality. Its P/E is 30 and quarterly revenue grew 18.8%. However, Microsoft spent $115.9 billion on capex in fiscal 2026, while Apple spent $9.04 billion.
Alphabet (NASDAQ:GOOGL) competes with Apple on AI assistants and trades at a P/E of 13. Its free cash flow came in at -$9.065 billion last quarter because of heavy AI spending.
Company P/E Net Margin Latest Quarterly Revenue Growth Apple 45 26.9% 11.7% Microsoft 30 40.3% 18.8% Alphabet 13 32.8% 24.65%On earnings multiples alone, the peer group makes our target look aggressive. Apple’s light capex needs and steady buybacks are the reasons I consider the target reasonable anyway.
Apple’s Cash Machine Supports Our Buy RatingThe 24/7 Wall St. price target of $384.73 carries a buy rating with 70% confidence. What tips the balance for me is capital efficiency.
I’d stay positive if iPhone Duo supply catches up with demand and gross margin holds within guidance. I’d be more cautious if memory costs push margins below the guided range.
Apple Price Prediction 2026-2030 Year Price Target from 24/7 Wall St. 2026 $384.73 2027 $388.89 2028 $419.78 2029 $452.72 2030 $480.97Apple would need to keep executing on its current strategy for these estimates to hold. Results could land well above or below them depending on how fast Siri AI is adopted and how long memory costs stay high.