


EN
Missed Allfunds Group's Rally? Here's The Bet Holders Made
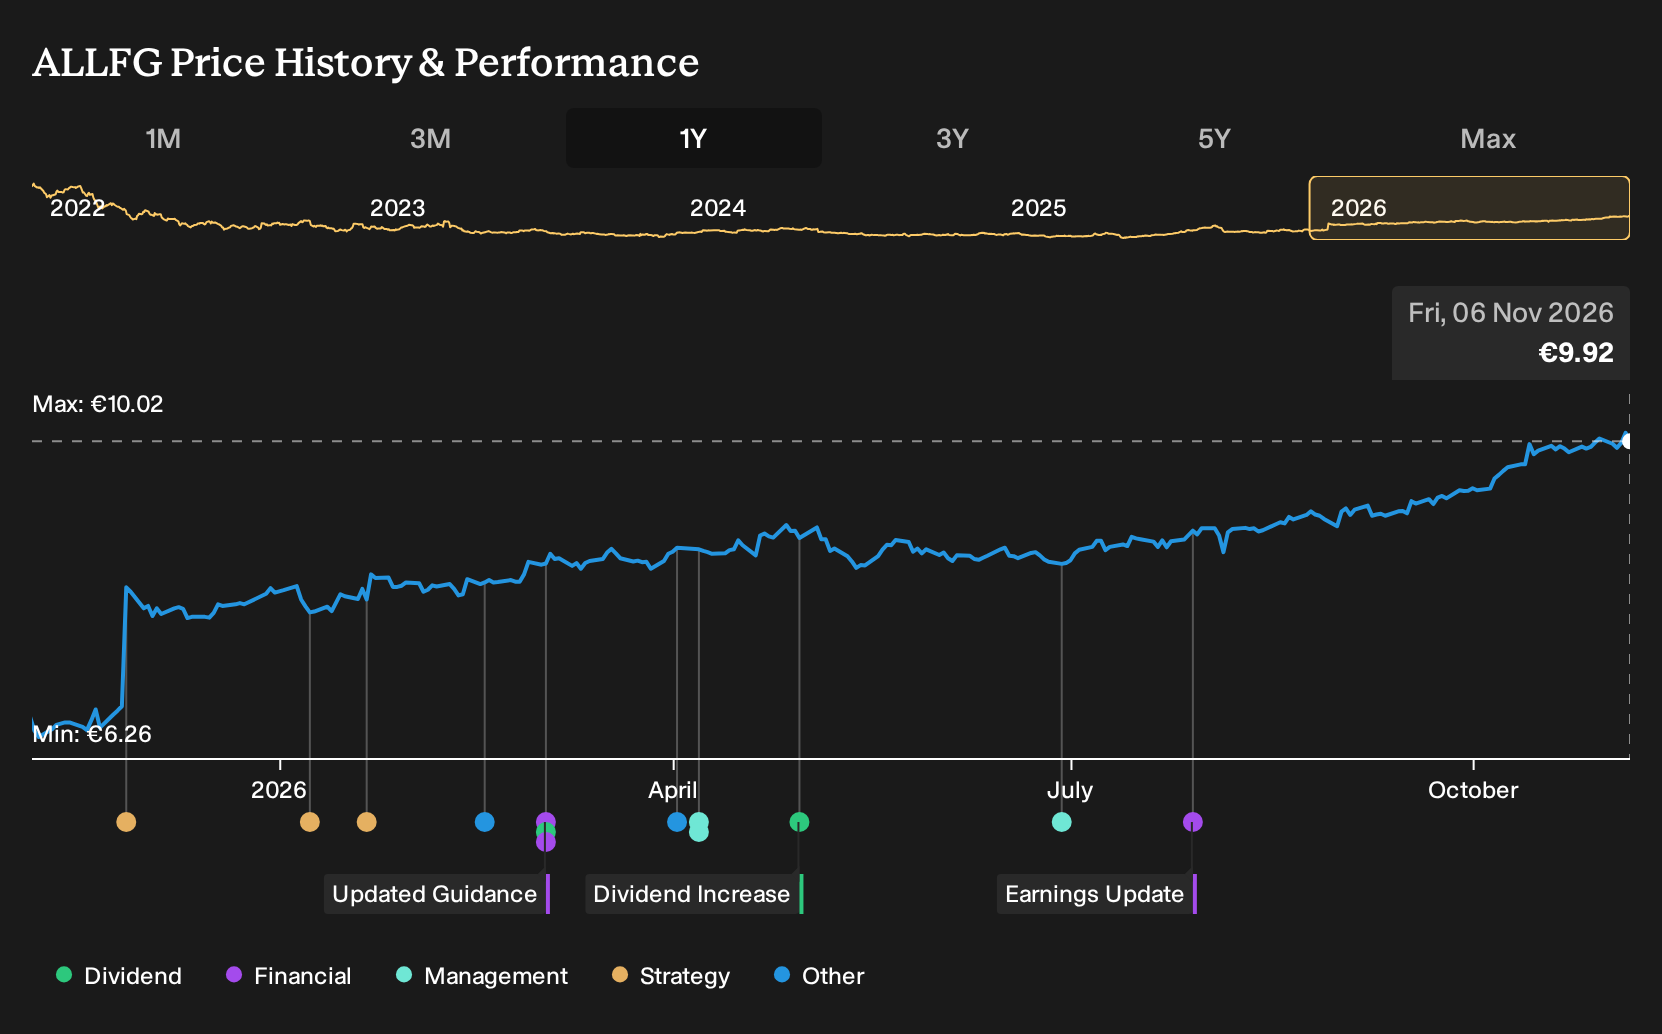
If you had looked at Allfunds Group in late 2025, you would have seen a wealth platform facing fee pressure, rising competition and uncertainty about how much of its bullish or bearish analyst debate would play out. For Allfunds Group shareholders, the return over the past year was 59.7%, including dividends. If you were weighing those conflicting narratives back then, what did the available evidence really say about the balance between margin risk and platform potential?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
The move put Allfunds Group in the middle of this trade. Scan 18 cryptocurrency and blockchain stocks for other companies exposed to it.
What Expectations Were Really In Play For Allfunds Group?
The shares cost €6.33 at the start of the period, and anyone looking at Allfunds Group then had to choose between two very different stories about the same platform.
On the bullish side, one published view in May 2025 put Fair Value at €8.2, which was 29% above the start price. That case leaned on rising adoption of open architecture and outsourcing, plus assumptions of 7.2% annual revenue growth and profit margins moving from a loss position to 26.1% by 2028.
The bearish July 2025 narrative set Fair Value at €5.8, which was 8% below the start price. It focused on fee compression and disintermediation risk, despite still assuming revenue growth of 2.9% a year and margins improving from a loss to 26.4% by 2028.
What The Allfunds Group Results Actually Tested
The clearest new fact was operating performance. Allfunds Group reported total revenue of €352.7m and net income of €81.9m in H1 2026, with net margin at 23.2% versus 13.1% a year earlier. Profitability moving closer to mid 20s margins broadly backed the optimistic case, although the bear view on fee pressure and competition was not disproved.
The key lesson is simple. When a thesis hangs on future margin strength, keep checking reported net margin against the story. For other platform stocks, compare each new half year margin print with what the bullish and cautious cases had assumed.
What Today's Allfunds Group Price Already Builds In
Allfunds Group now trades at €9.91, with this cautious Narrative's Fair Value sitting below that quote. The bearish analyst Narrative on Simply Wall St argues that the key question has shifted from simple fee pressure to whether newer profit pools justify the current valuation.
For that to hold up, a buyer at today's price would need to believe the alternatives and tokenized fund push can offset any squeeze on traditional distribution economics and support the current mix of margins and growth.
"The main thing that has to go right is that Allfunds Group converts its growing alternatives and tokenized fund ecosystem into durable, higher quality revenue that more than offsets fee pressure on its core platform. The current valuation implies the Allfunds Group share price already reflects a long runway of high margin growth and successful execution on private markets, blockchain automation and the portfolio refocus."
One Narrative disagrees with today's price. → See where this Narrative says Allfunds Group should trade
How Could You Get There Earlier?
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 42% below our estimate - focuses on cash recycling technology that automates and streamlines branch transactions.
- Company 2 - 30% below our estimate - uses acquisition-driven funding to scale an automated, higher margin banking loan platform.
- Company 3 - 22% below our estimate - targets secured consumer lending while improving staff productivity and maintaining strong credit standards.
Those are three of them. See every one of the 223 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com