


EN
MercadoLibre (MELI) Stock Looks Above Fair Value Following Its 28% Slide
MercadoLibre has seen its share price come under pressure over the past year, and the slide is prompting a fresh look at whether what you pay today still lines up with what the business is earning. For a company built around e-commerce and fintech in Latin America, that question now sits front and center for anyone thinking about valuation.
- The stock is down 27.8% over the past 12 months, which puts the focus squarely on whether that drop has brought the earnings based valuation in line with what the business is currently producing.
- Recent updates around MercadoLibre’s e-commerce, payments and advertising operations, including the planned advertising tie up with Netflix, can influence expectations for how quickly profits might grow and how reliable those earnings streams may look over time.
- Your read on MercadoLibre is one view; the desks covering it have another. See what analysts think MercadoLibre's shares could be worth.
The issue now is whether MercadoLibre’s current share price around US$1,510 is justified by its earnings when judged against the Fair Ratio benchmark.
If you want to explore the same earnings question you are asking of MercadoLibre across a wider field, scan through 40 high quality undervalued stocks.
Is MercadoLibre Getting Expensive on Earnings?
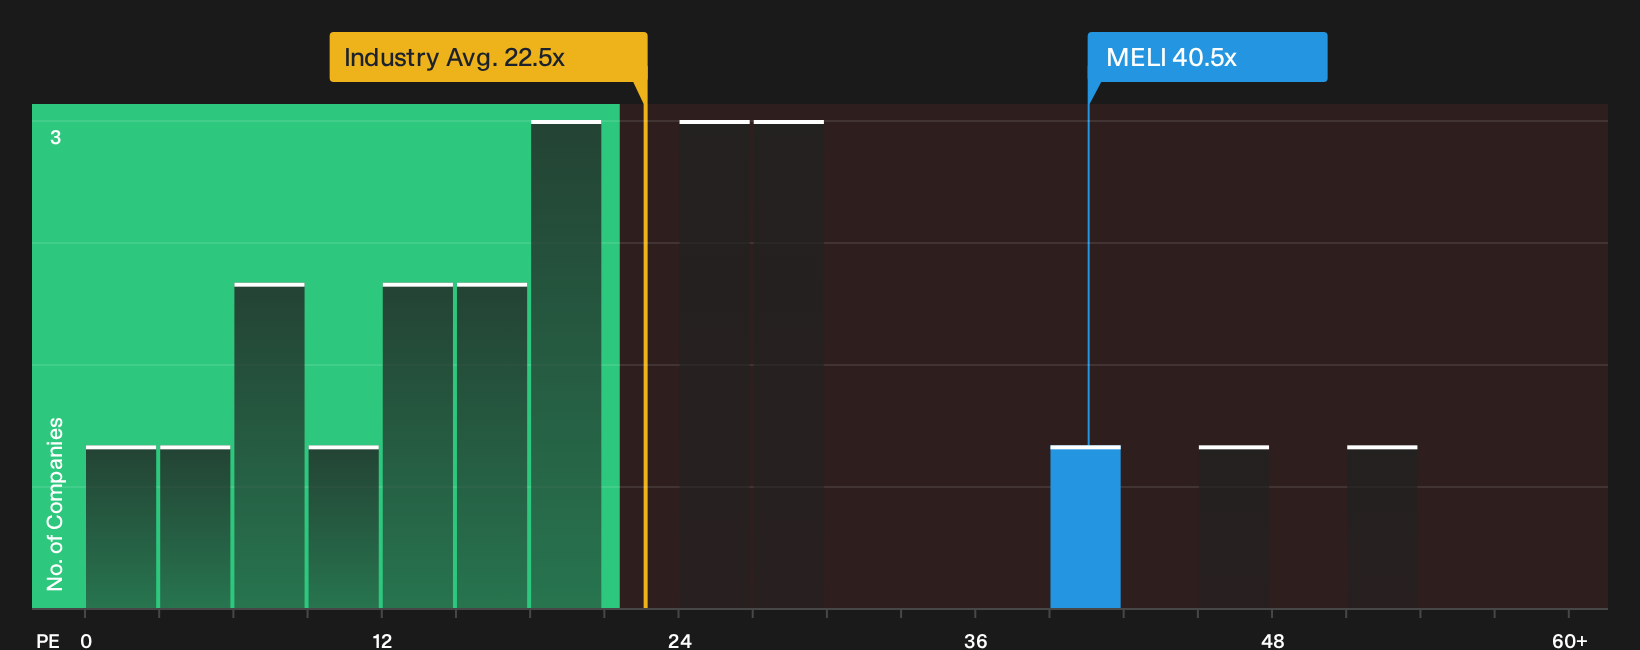
P/E is the cleanest way to frame MercadoLibre right now because earnings are available and investors are weighing what they are willing to pay for each dollar of profit. On this yardstick, the stock trades around 40.5x, which is roughly double the Multiline Retail industry average of about 19.3x and also higher than the peer group at about 20.0x.
The Fair Ratio, which blends the company’s growth profile, margins, size and risk into a tailored benchmark, sits below that level. As a result, the current P/E points to MercadoLibre appearing overvalued on this framework. Despite the recent Q3 2026 report flagging strong revenue and user momentum, the present multiple still prices the business well above both its own earnings-based reference point and sector norms, so buyers are paying a clear premium for that story. Explore the numbers behind MercadoLibre's P/E valuation.
The MercadoLibre Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the MercadoLibre valuation puzzle leaves off and spell out which paths for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or richer than today's quote, using the Community page as home base. Each one treats fair value as a working hypothesis about MercadoLibre's business that you can watch over time rather than a one off snapshot.
One of the top community narratives on MercadoLibre: 37% undervalued
According to John_Eric, a Simply Wall St Community investor who wrote the Narrative, MercadoLibre hinges on how its fintech lending reshapes reported cash generation.
"The disagreement is about a judgment call, is MercadoLibre's credit book a temporary, self-funding investment phase, or a structurally cash-hungry business..."
Discover why this Narrative puts MercadoLibre at 37% undervalued.
The one MercadoLibre question this valuation has not touched
Price tags and profit multiples only tell part of the story, because the people steering MercadoLibre and the way their rewards are structured can heavily shape future choices and risk. See who runs MercadoLibre and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com