


EN
BeOne Medicines (ONC) Priority Review And Earnings Put Valuation Back In Focus
Why BeOne Medicines Stock Is Back in Focus
BeOne Medicines (NasdaqGS:ONC) is back on investors radar after two closely timed catalysts. The FDA granted Priority Review for a key BRUKINSA regimen and the group reported detailed third quarter earnings.
That regulatory and earnings one two punch has arrived alongside a strong run in the shares, with BeOne Medicines posting a 30.85% year to date share price return and a 3 year total shareholder return above 100%. Shorter term gains suggest momentum has recently picked up as investors reassess both growth prospects and risk.
Spot fresh oncology momentum beyond BeOne Medicines by scanning a hand picked set of 35 healthcare AI stocks that sit at the intersection of cancer treatments and advanced AI-driven drug development.After that kind of move, and with BeOne Medicines now trading near analysts’ published targets, the real tension sits in the valuation. Has the bulk of the rerating already happened, or is the market still conservative here?
Most Popular Narrative: 7% Undervalued
The analyst consensus Narrative on Simply Wall St marks BeOne Medicines at a fair value of $437.57, slightly above the last close at $406.96. This frames the recent share price strength against a still modest discount using a 7.38% discount rate.
The main factor that has to go right is that BeOne Medicines converts its broad late stage oncology pipeline and global development platform into successful approvals and sustained uptake, while continuing to manage operating expenses that are growing at mid teens rates.
The current valuation implies the market is not fully crediting BeOne Medicines for its reported GAAP profitability, high 80s gross margins, rising free cash flow and guidance upgrades, which this narrative describes as consistent with an undervalued setup for the share price.
See why 20 investors see BeOne Medicines as 7% undervalued.
Result: Fair Value of $437.57 (UNDERVALUED)
Still, the BeOne Medicines story can break if high mid teens operating expense growth squeezes margins, or if biosimilar pressure on partnered assets bites harder than expected.
Find out about the key risks to this BeOne Medicines narrative.
Another View: What Multiples Say About BeOne Medicines
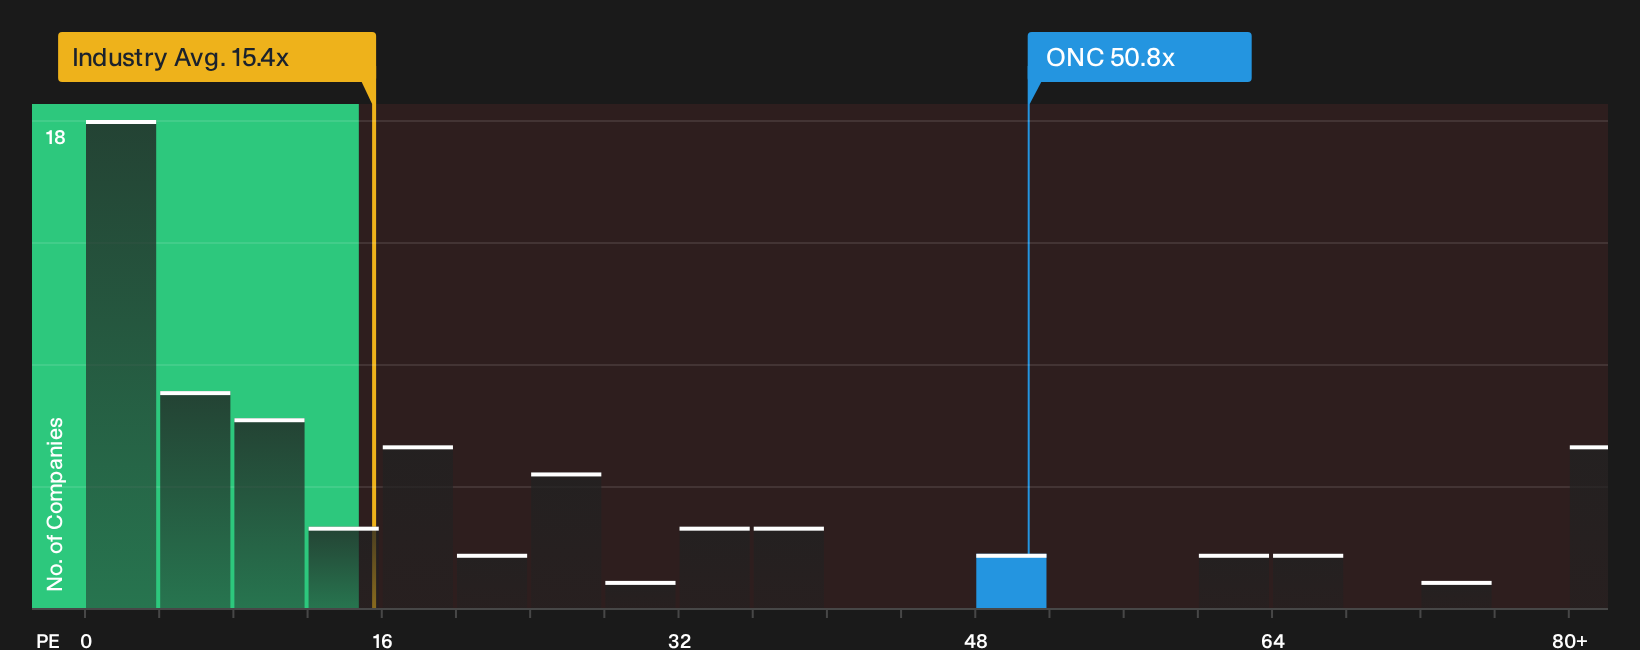
There is a different message hiding in the simple P/E ratio. BeOne Medicines trades on about 50.8x earnings, compared with 48.4x for similar peers and 15.4x for the wider US biotechs group, while the fair ratio for the stock is calculated at 34.8x.
That gap implies investors are already paying a premium for BeOne Medicines on earnings today, even though the fair ratio points to a lower level the market could eventually move toward. The question is whether you lean more on the DCF style cash flow story or on this richer earnings multiple when weighing upside versus valuation risk.
See what the numbers say about this price in our valuation breakdown to pressure test your own view on BeOne Medicines, starting with the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If sentiment in this BeOne Medicines story feels split, that is the point. The real edge comes from working through the numbers yourself and testing every assumption against your own risk tolerance. To pressure test whether the optimism is justified by the underlying data, spend a few minutes with the 3 key rewards
Looking for more BeOne Medicines investment ideas?
Do not stop with a single ticker. Broader research can surface opportunities you would never spot just skimming headlines or following the latest buzz.
- Target higher potential upside by focusing on companies that screen well for quality and value through the 19 high quality undiscovered gems.
- Prioritise sleep at night stability by reviewing the 31 resilient stocks with low risk scores that score well on resilience and downside protection.
- Aim for dependable income streams by scanning the 7 dividend fortresses that pair stronger yields with more robust fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com