


EN
A. O. Smith (AOS) Cuts China From 2026 Guidance, Is The Stock 17% Overvalued?
A. O. Smith event recap
A. O. Smith (AOS) shares are in focus after management updated full year 2026 guidance to exclude the China business and released third quarter results showing slightly lower sales and earnings than a year earlier.
At around US$64.55 a share, A. O. Smith has slipped 3% on the day and edged lower over the past week. However, the 30 day share price return of about 14% shows momentum that contrasts with a weaker year to date share price performance and slightly negative multi year total shareholder returns, as investors weigh the China exit from 2026 guidance against recent earnings softness.
Compare A. O. Smith's shift away from China with other industrial players reshaping their revenue mix by scanning our curated list of list of solid balance sheet and fundamentals (25 results)
For A. O. Smith, a 14% gain over 30 days, set against softer earnings and a planned China exit, raises a simple issue: Is the price now signaling business resilience or just a sentiment swing that the valuation needs to test?
Most Popular Narrative: 17% Overvalued
Against A. O. Smith's last close at $64.55, the leading narrative pegs fair value at $55, which implies the shares screen as richer than that estimate. That framing uses an 8.65% discount rate and pulls together cash generation, market structure, and business mix.
AOS manufactures water heaters and boilers in North America, with a secondary business in China that is in structural decline. The North American franchise is genuinely strong: three players control more than 90% of the market, the product is a non-discretionary emergency replacement in more than 80% of cases, and prices have risen above inflation for twelve consecutive years.
See why 3 investors see A. O. Smith as 17% overvalued.
Result: Fair Value of $55 (OVERVALUED)
Still, the pending China review and the 2029 U.S. heat pump rules could both upset the current A. O. Smith valuation story if outcomes disappoint expectations.
Find out about the key risks to this A. O. Smith narrative.
Another View on A. O. Smith’s Valuation
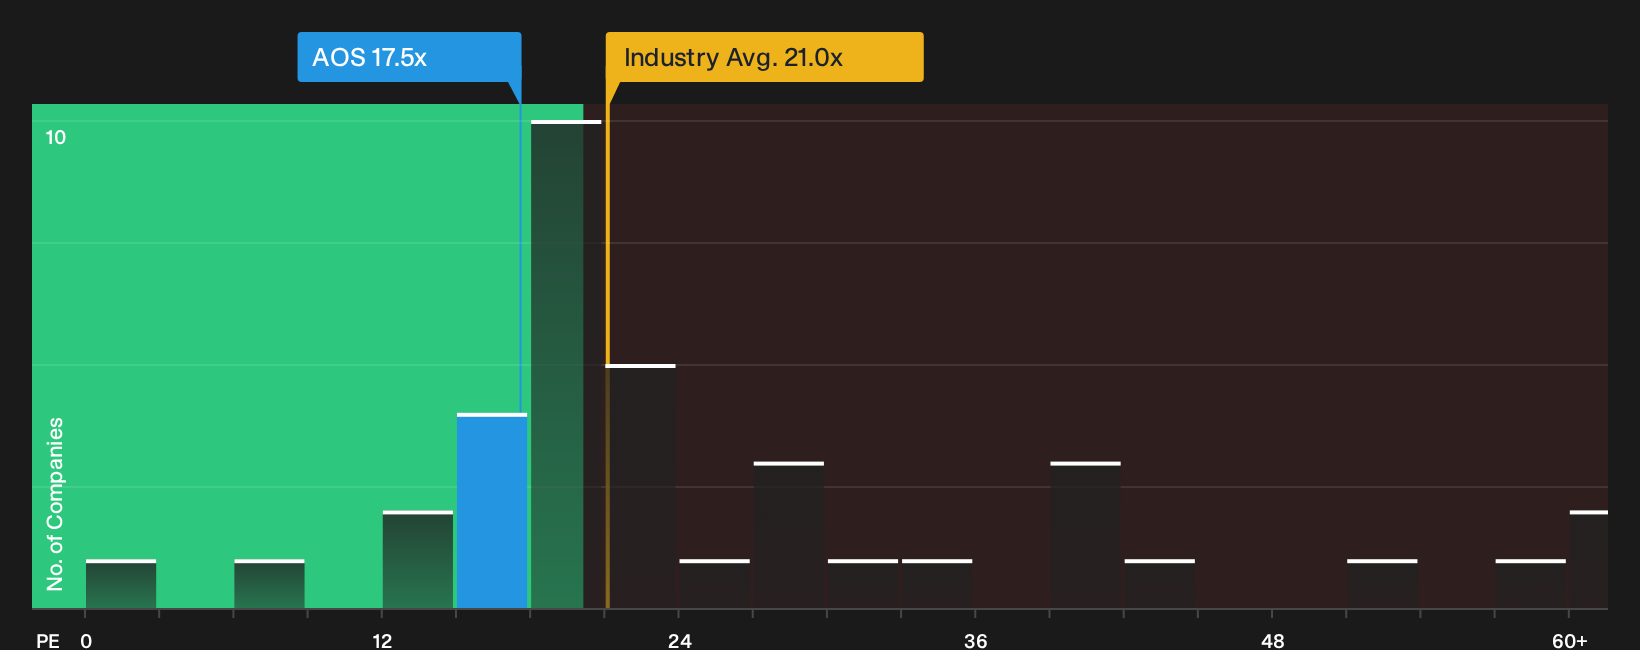
That $55 fair value narrative clashes with how the market is actually pricing A. O. Smith on earnings. At a P/E of 17.5x, the stock trades below the US Building industry at 21x, the peer group at 20.6x, and even the 19.3x fair ratio our model suggests the market could move toward. Is this a cushion against disappointment or a value trap if the China exit and heat pump shift do not play out cleanly?
For investors who rely on comparative pricing more than spreadsheets, the P/E gap and fair ratio context offer a different lens on risk and potential reward in A. O. Smith, which is unpacked in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the mixed sentiment around A. O. Smith has you on the fence, move quickly from headlines to hard facts and check the underlying signals. To see what investors are currently optimistic about, start with 4 key rewards
Looking for more A. O. Smith style investment ideas?
If A. O. Smith has sharpened your focus on quality and valuation, broaden your watchlist with a few targeted stock ideas powered by the Simply Wall St screener.
- Target value opportunities that pair strong fundamentals with supportive pricing by scanning our 40 high quality undervalued stocks.
- Build a portfolio that aims for income strength and resilience with the help of our 7 dividend fortresses.
- Prioritise financial strength and staying power across market cycles by starting with the 31 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com