


EN
Will Fiber Contract Win Change Belden (BDC) Stock Narrative
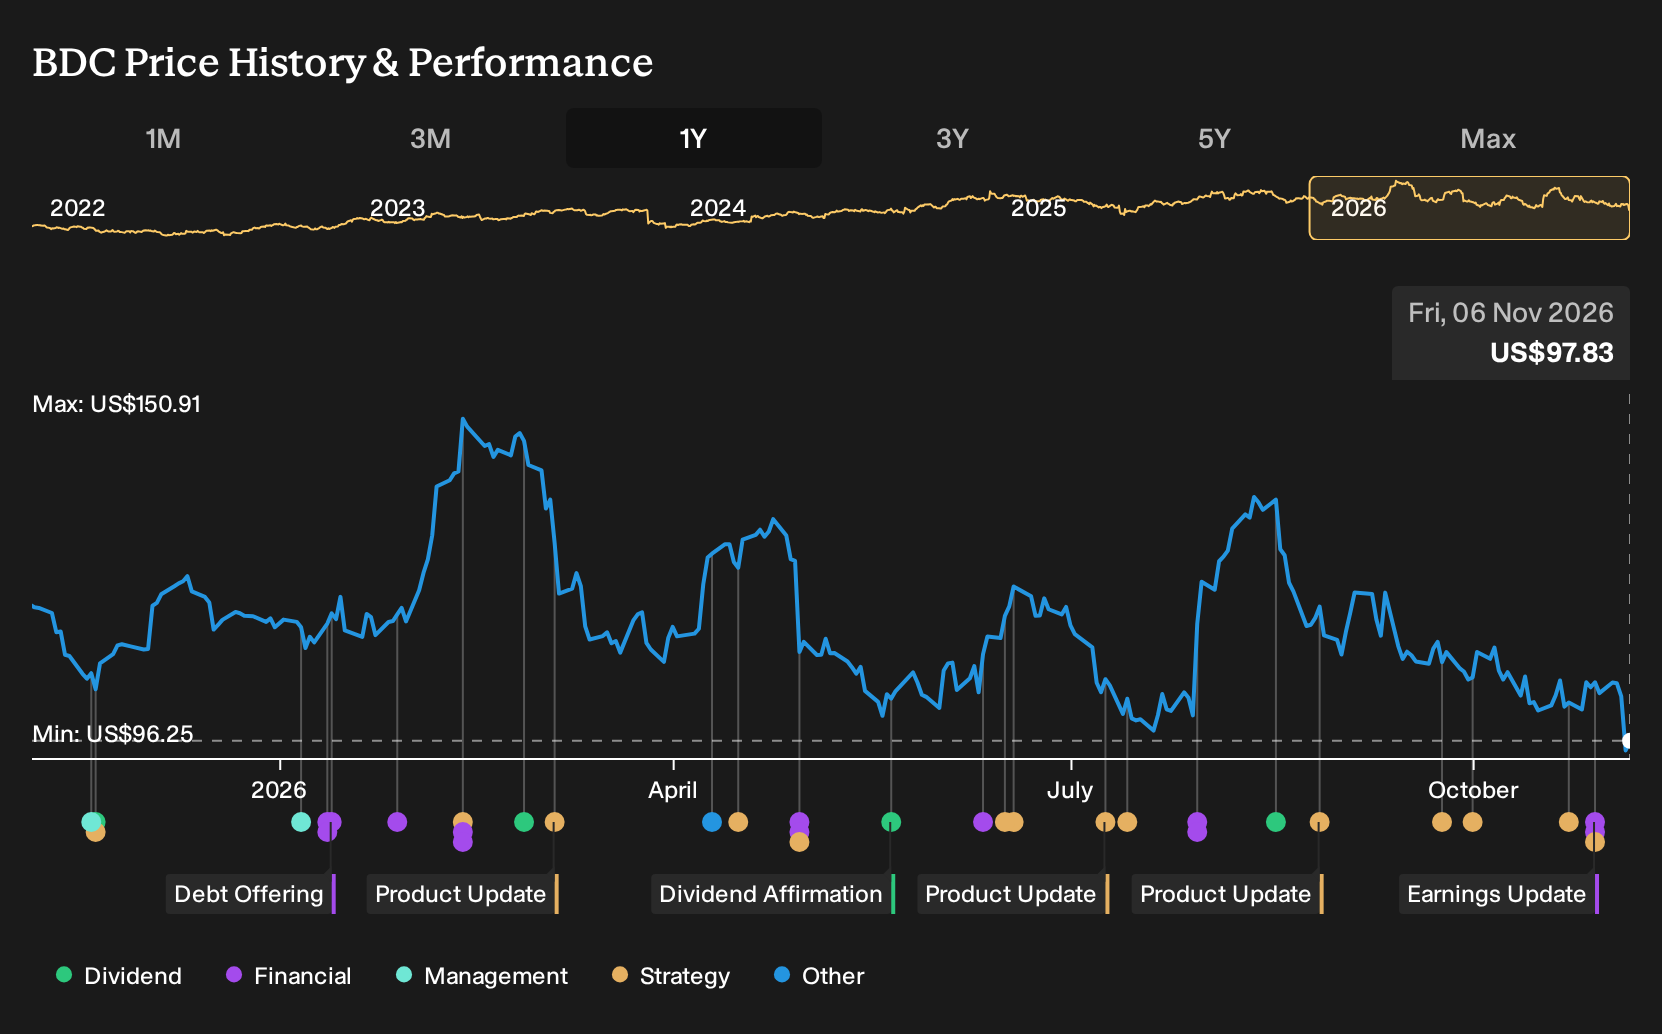
- Belden announced in October 2026 that it signed an agreement to supply US$100 million of fiber assemblies in 2027 and issued fourth quarter 2026 revenue and EPS guidance alongside third quarter results that showed higher sales but a net loss and lower earnings per share than a year earlier.
- The new fiber assemblies deal is expected by Belden to lift its data center activity by more than 50% next year, which highlights how quickly this newer line of business is scaling even as recent profitability metrics have been under pressure.
- We will now look at how Belden's investment narrative could shift given the data center contract and refreshed near term guidance.
Scan how Belden's new data center push compares with peers by reviewing 53 AI infrastructure stocks that are riding the same build out in fiber rich infrastructure and connectivity demand.
Belden Investment Narrative Recap
For Belden, the core belief is that the shift toward higher value connectivity, AI data centers and active networking eventually shows up in cleaner profitability, not just higher sales. The recent fiber assemblies win supports that direction, but the latest quarter reminds you that higher revenue can still coincide with a net loss and thinner earnings per share.
The analyst consensus narrative on Simply Wall St leans on improving earnings over time, yet the immediate swing factor now is execution on mix and cost discipline while data center work scales. The biggest near term risk is that already pressured margins, weaker cash coverage of debt and recent losses persist even as volumes rise.
The US$100 million fiber assemblies agreement for 2027 looks most relevant because it connects directly to the AI data center and Physical AI themes analysts have been watching. It also sits alongside Belden’s guidance for fourth quarter 2026 revenue of US$960 million to US$980 million and GAAP EPS of US$0.24 to US$0.39.
That pairing gives you a clearer test for the current catalyst. Investors can watch whether this larger contract and the existing US$175 million AI run rate begin to show up in steadier earnings and healthier margins, or whether issues like flat operating margin history and weaker operating cash flow coverage of debt remain the bigger story.
Belden's narrative projects US$4.6b revenue and US$404.1 million earnings by 2029. This assumes 17.3% yearly revenue growth and an earnings increase of about US$160 million from US$244.1 million today.
Explore why Belden's fair value suggests a 57% potential upside to its current price before the market closes that gap.
Exploring Other Perspectives
Only two fair value estimates from the Simply Wall St Community cluster between about US$141 and US$153 per share, so the current crowd view on Belden is narrow rather than scattered. Those opinions predate the US$100 million data center contract and fresh guidance, so treat them as a baseline and explore other community viewpoints before forming your own stance.
Explore another Belden fair value estimate, including one that suggests there could be as much as 57% upside from the current price.
Decide For Yourself
Disagree with existing narratives? Investment results often differ when you avoid simply following the herd, so consider trusting your own analysis.
- A great starting point for your Belden research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Belden. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Belden's overall financial health at a glance.
Looking for more Belden sized investment ideas?
Once you have a view on Belden, it often helps to widen the lens and compare it with other companies that share similar qualities or offer very different risk and reward profiles. The Simply Wall St Screener can help you quickly filter for the kind of businesses that match your own preferences rather than someone else's list.
- If you are hunting for more resilience than excitement, you might start with companies that show steadier balance sheets and fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Income focused investors who care about cash returns today rather than only potential price moves tomorrow can review our collection of 7 dividend fortresses that currently clear a 5% yield hurdle.
- Readers who prefer to back firms that look overlooked but financially sound can browse our hand picked 19 high quality undiscovered gems that may not yet be widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com