


EN
The Biggest AI Opportunity May Be Hiding Outside the GPU Market
Broadcom (NASDAQ:AVGO) is the clearest way to own AI compute without owning a GPU. Shares were at $301.58 at noon on November 5, down 7.34% for the session.
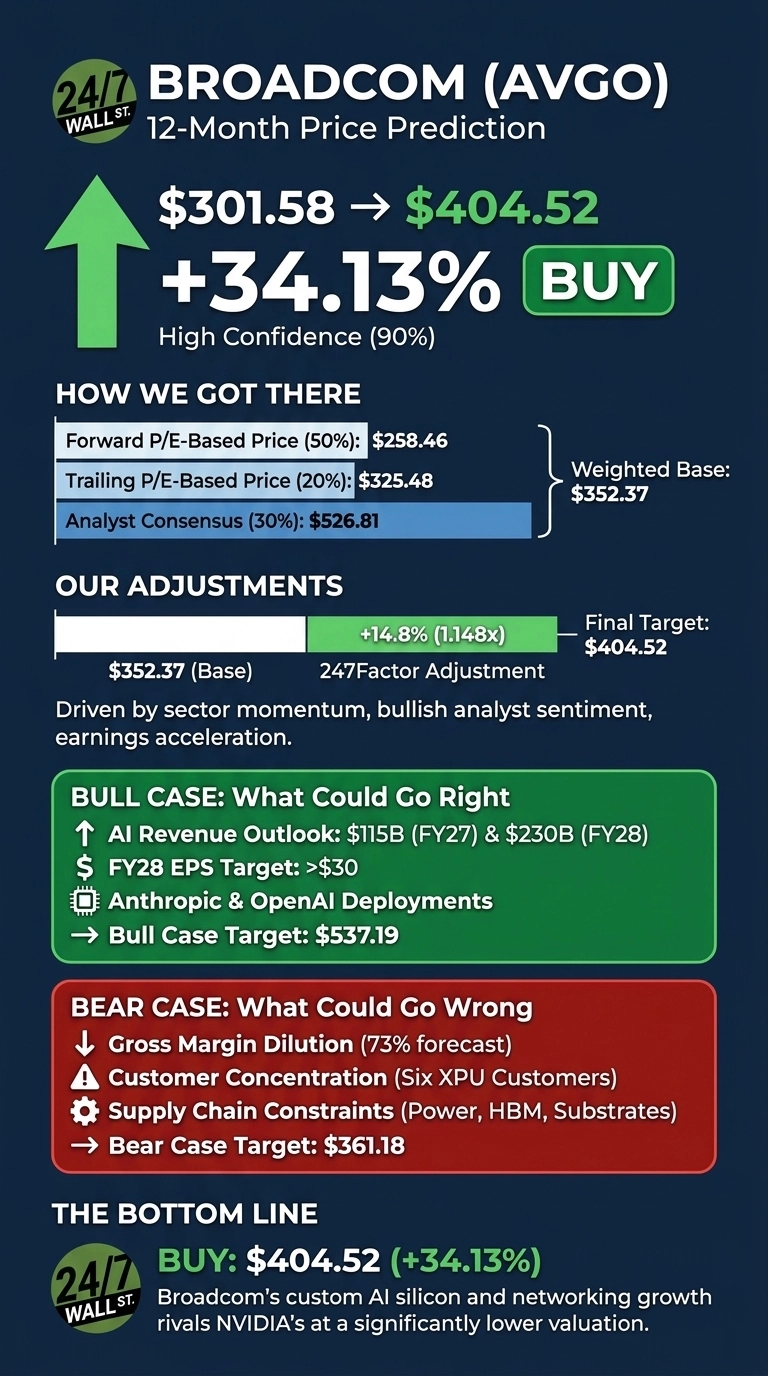
Our 24/7 Wall St. price target is $404.52, which means 34.13% upside from here. Our model rates the stock a buy, with high confidence.
 24/7 Wall St. 24/7 Wall St. Price Target Summary Metric Value Current Price $301.58 24/7 Wall St. Price Target $404.52 Upside 34.13% Model Rating BUY Confidence Level 90%
The model ran off the prior close of $325.48, where it means 24.28% upside. Today’s drop extends that gap. My thesis is that custom accelerators (XPUs) and Ethernet AI networking give Broadcom a growth curve that rivals NVIDIA’s, at a much lower multiple.
Record Quarter Meets a Steep SelloffThe stock is down 14.28% over the past week, 16.81% over the past month and 12.39% year to date. It sits 38.86% below its 52-week high of $493.28 and just 4.37% above its low of $288.95.
Fiscal Q3 revenue rose 85.5% to $29.591 billion, ahead of the $29.435 billion estimate. EPS of $3.32 beat the $3.24 consensus, and AI semiconductor revenue climbed 221% to $16.70 billion. Management forecast Q4 revenue to about $34.8 billion.
Chip stocks also sold off in October after Microsoft (NASDAQ:MSFT) revealed its own AI silicon (Kalkine). On October 26, four major banks and Blackstone (NYSE:BX) announced a $63 billion financing structure to fund AI compute capacity in partnership with Broadcom (the power, networking, and infrastructure names tied to that expansion are the ones we profiled in a free report on seven AI stocks that aren’t chipmakers).
Why Bulls See $537 and BeyondManagement expects AI revenue of about $115 billion in fiscal 2027 and $230 billion in fiscal 2028. They also said they are on target to earn more than $30 per share in fiscal 2028. Anthropic plans to deploy 5 gigawatts of TPU v8i in 2027, and OpenAI plans 1.3 gigawatts of its Jalapeno chip. Broadcom estimates its content at $20 billion to $30 billion per gigawatt.
CEO Hock Tan was blunt: “When you co-develop a chip that is optimized for your particular large language model workloads, you will outperform any GPU.” On the street, 49 analysts rate the stock a buy or strong buy and just 2 rate it a hold. Our bull case is $537.19.
Margin Dilution and Customer Concentration Lead the RisksGross margin fell 210 basis points from Q2 to 75%, and management guides to about 73% in Q4. Operating margin still came in at 67.9%, though, because revenue is growing much faster than expenses. Revenue is concentrated in six XPU customers.
Shipment timing also depends on power, substrates and HBM supply. Broadcom carries $59.6 billion of fixed-rate debt and may offer residual value guarantees through its financing platform. Even so, our bear case of $361.18 sits above today’s price.
How Broadcom Compares to NVIDIA and MarvellNVIDIA (NASDAQ:NVDA) is the GPU benchmark. Revenue rose 105.85% last quarter, and the stock trades at 40x trailing earnings. Broadcom’s AI growth is faster, and its forward multiple of 18 sits well below NVIDIA’s trailing multiple of 40x, though the two measures differ.
Marvell Technology (NASDAQ:MRVL) is the closest custom-ASIC rival. Revenue grew 36.55% to $2.739 billion, with data center at 79% of sales. Next to these peers, our 24/7 Wall St. price target looks conservative.
Company Latest Quarter Revenue Growth AI/Data Center Growth Broadcom 85.5% 221% NVIDIA 105.85% 117% Marvell 36.55% 46% Broadcom’s Discount Looks Too Steep to LastOur 24/7 Wall St. price target of $404.52 comes with a buy rating and 90% confidence. AI semiconductor revenue climbed 221% last quarter.
I would become more constructive if Q4 AI revenue reaches $21.7 billion and operating margins hold. I would turn conservative if a major XPU customer delays its deployments. At these levels, the model’s bear case of $361.18 still sits above the share price.
Here is where our model projects Broadcom could trade if current growth trends and market conditions hold.
Year 24/7 Wall St. Price Target 2026 $335.42 2027 $410.58 2028 $477.98 2029 $542.11 2030 $592.90These projections assume Broadcom keeps executing on its custom silicon roadmap. If the fiscal 2028 AI target is met, prices could land well above these figures. If data center deployments slip, they could land below.