


EN
Linde (LIN), Why Is Its Latest Update Drawing Attention?
Linde (NasdaqGS:LIN) just reported third quarter results that paired higher sales with lower quarterly net income, while nine month figures showed both revenue and profit above the prior year period.
Investors have reacted cautiously to the latest update, with Linde's share price slipping 1.2% on the day and edging 0.9% lower over the past week. The stock still carries a 6.5% 1 month share price return and a 20.1% gain year to date, alongside a 24.1% 1 year total shareholder return that indicates momentum building over a longer window.
Scan for other industrials showing similar earnings momentum and price moves to Linde by zeroing in on the list of solid balance sheet and fundamentals (25 results) that have already cleared a strict quality bar.
Linde shares have already logged a strong run this year; however, the latest quarter mixed higher sales with softer profit. Is most of the easy upside already reflected in the price, or does valuation still leave meaningful headroom?
Most Popular Narrative: 5.4% Undervalued
On the analyst consensus Narrative on Simply Wall St, Linde screens as modestly undervalued, with a fair value of $544.40 against a last close of $515.25, using a discount rate of about 7.9% to bring future cash flows back to today.
The earlier focus on commercial space, electronics and clean hydrogen is now supported by double digit space related growth contributing to manufacturing. The company has a stated path to more than US$1b of space revenue by 2030 and large hydrogen and CCS projects, which together can add higher value revenue streams and support margin mix.
See why 123 investors see Linde as 5% undervalued.
Result: Fair Value of $544.40 (UNDERVALUED)
Still, two pressure points could flip that story for Linde: prolonged industrial weakness in Europe and ongoing margin drag from the U.S. homecare business.
Find out about the key risks to this Linde narrative.
Another View: What Linde’s P/E Is Telling You
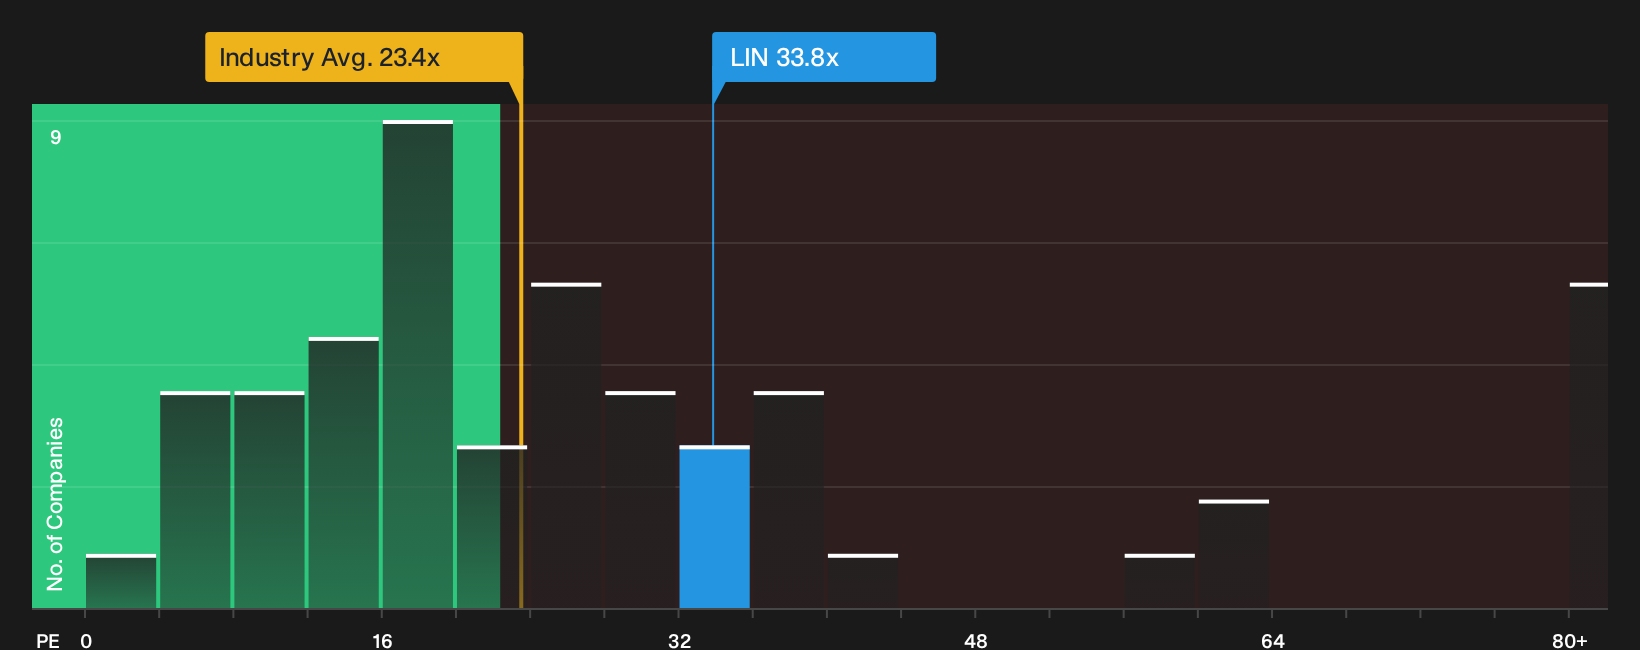
Linde may screen as 5.4% undervalued on the analyst-led fair value of $544.40, yet its 33.8x P/E tells a tougher story. That multiple sits well above the US Chemicals industry on 23.4x and the fair ratio of 22.8x, which points to valuation risk if expectations cool.
The gap between today’s P/E and the fair ratio suggests the market could shift toward a lower earnings multiple if sentiment or forecasts reset. The key question is whether you believe Linde’s future earnings profile justifies staying at a premium or drifting closer to peers and the fair ratio.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of upside and risk around Linde feels finely balanced, move fast on your own homework and pressure test the assumptions that matter most to you. To see both sides of the debate in one place, start with the 1 key reward and 1 important warning sign.
Looking For More Ideas Beyond Linde?
You have fresh context on Linde. Now back it up by scanning a few focused stock shortlists so you are not leaving better risk reward profiles on the table.
- Target stability first and stress test your defensive core against a 31 resilient stocks with low risk scores that highlights resilient businesses with lower risk scores.
- Hunt for mispriced quality and compare Linde with a 40 high quality undervalued stocks that filters for strong fundamentals paired with potentially cheaper entry points.
- Spot early opportunities by reviewing a 19 high quality undiscovered gems packed with under-the-radar companies that already show high quality characteristics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com